Binary options are often marketed as simple, fast, and accessible ways to “trade” the market, but they are Binary options give a trader a contractual payoff tied to a defined event. They do not provide the same economic exposure as owning shares, holding a bond or buying units in an investment fund. A familiar market name on the trading screen does not change that distinction. A contract referencing the ASX 200 is not an investment in the companies within the index.
For Australian retail clients, the regulatory position is also decisive. ASIC banned the issue and distribution of binary options to retail clients from 3 May 2021 and extended the ban until 1 October 2031. This is a product restriction, rather than a warning that consumers can address simply by finding a better broker.
The reason binary options are unsuitable for ordinary wealth building is more precise than saying they involve risk or short holding periods. Their returns depend on a narrowly defined result, often at a fixed expiry, with a capped profit and the possibility of losing the entire amount paid. Understanding those terms explains why predicting a market correctly can still produce a poor financial outcome.
What investing means
Investing generally involves committing money to an asset or financial claim with an expectation of future income, growth in value, or both. The expectation needs an economic basis. It might rest on a company’s capacity to earn profits, a borrower’s obligation to repay debt, or rental income from property.
Putting money at risk and hoping to receive more later is too broad a definition to distinguish investing from speculation. Those conditions also describe a wager. The more useful questions concern what the purchaser owns, what produces the return, what price is being paid and how the exposure fits the intended holding period.
Trading and investment comparison websites such as Investing.co.uk discuss several financial products within the same service. That grouping does not make the products interchangeable. A shareholding, a currency derivative and a binary contract can reference the same economy while giving their holders different rights and outcomes.
Investment returns have identifiable sources
A company can earn profits, reinvest in its operations and distribute some of those profits to shareholders. Investors can benefit through dividends and changes in the share price. The outcome is uncertain, and paying too much for a profitable company can still lead to a disappointing return.
A bond creates a different relationship. As ASIC’s Moneysmart explanation of bonds describes, the investor lends to a government or company. The contractual payments and repayment terms provide a basis for assessing the investment, alongside the issuer’s creditworthiness and prevailing interest rates.
Neither example requires an unlimited potential return. An ordinary fixed rate bond has defined contractual payments, yet it remains an investment. Conversely, the possibility of a large gain does not establish that an activity is suitable for long term saving.
Speculation depends more heavily on resale or event outcomes
Speculation involves accepting risk in anticipation of a favourable price change or event. It can take place in conventional assets as well as derivatives. Someone buying a share solely because they expect it to rise before lunch is using a speculative approach, despite owning a genuine interest in a business.
The distinction therefore concerns both the instrument and its use. Long holding periods do not automatically make a poor purchase sound, and short holding periods do not automatically make every transaction gambling.
For retail binary options, however, the contract itself concentrates the outcome into an event test. The holder’s return does not accumulate through continued ownership of a productive asset. It depends on whether the contract’s condition is satisfied and whether the counterparty honours the settlement.
Ownership and economic exposure
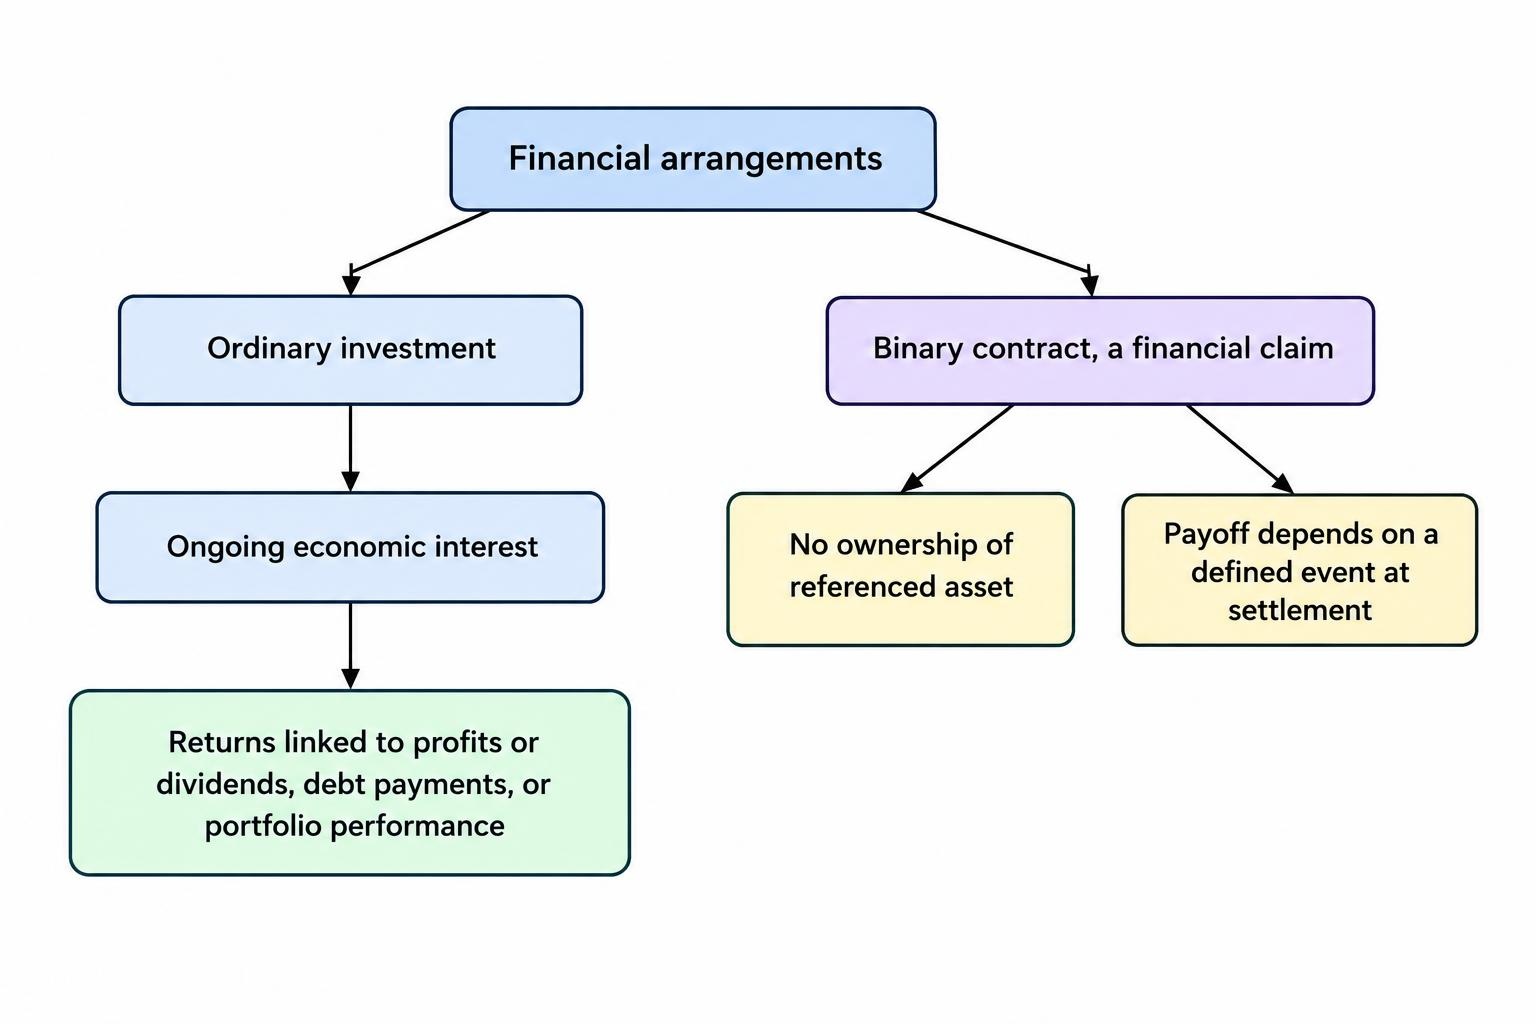
A binary option does not give its holder ownership of the asset used to determine its result. A contract linked to BHP’s share price does not make the holder a BHP shareholder. A contract linked to gold does not provide ownership of bullion. A contract linked to AUD/USD does not create a bank balance in either currency.
That distinction should not be overstated as “no asset exists”. The binary contract is itself a financial claim and can have economic value before expiry. What is absent is ownership of the underlying shares, commodity or currency. The value and rights belong to the contract, not to the referenced asset.
What a shareholder or fund investor holds
A shareholder has an ownership interest in a company. The share can remain in the portfolio while the company continues operating, subject to corporate events and the investor’s own decisions. Its value can fall sharply, but an ordinary share does not become worthless merely because its price is below yesterday’s level at a preselected minute.
An ETF investor generally owns units in a fund, rather than directly owning each asset held by that fund. Moneysmart’s ETF guidance explains this distinction. The units provide exposure to the fund’s assets or strategy, with returns affected by asset values, income, fees and trading costs.
Ownership does not remove risk. A company can fail, a fund can hold unsuitable assets and a bond issuer can default. The relevant difference is that the investor has an ongoing economic interest whose returns can be assessed against the underlying business, portfolio or repayment obligation.
What a binary contract actually measures
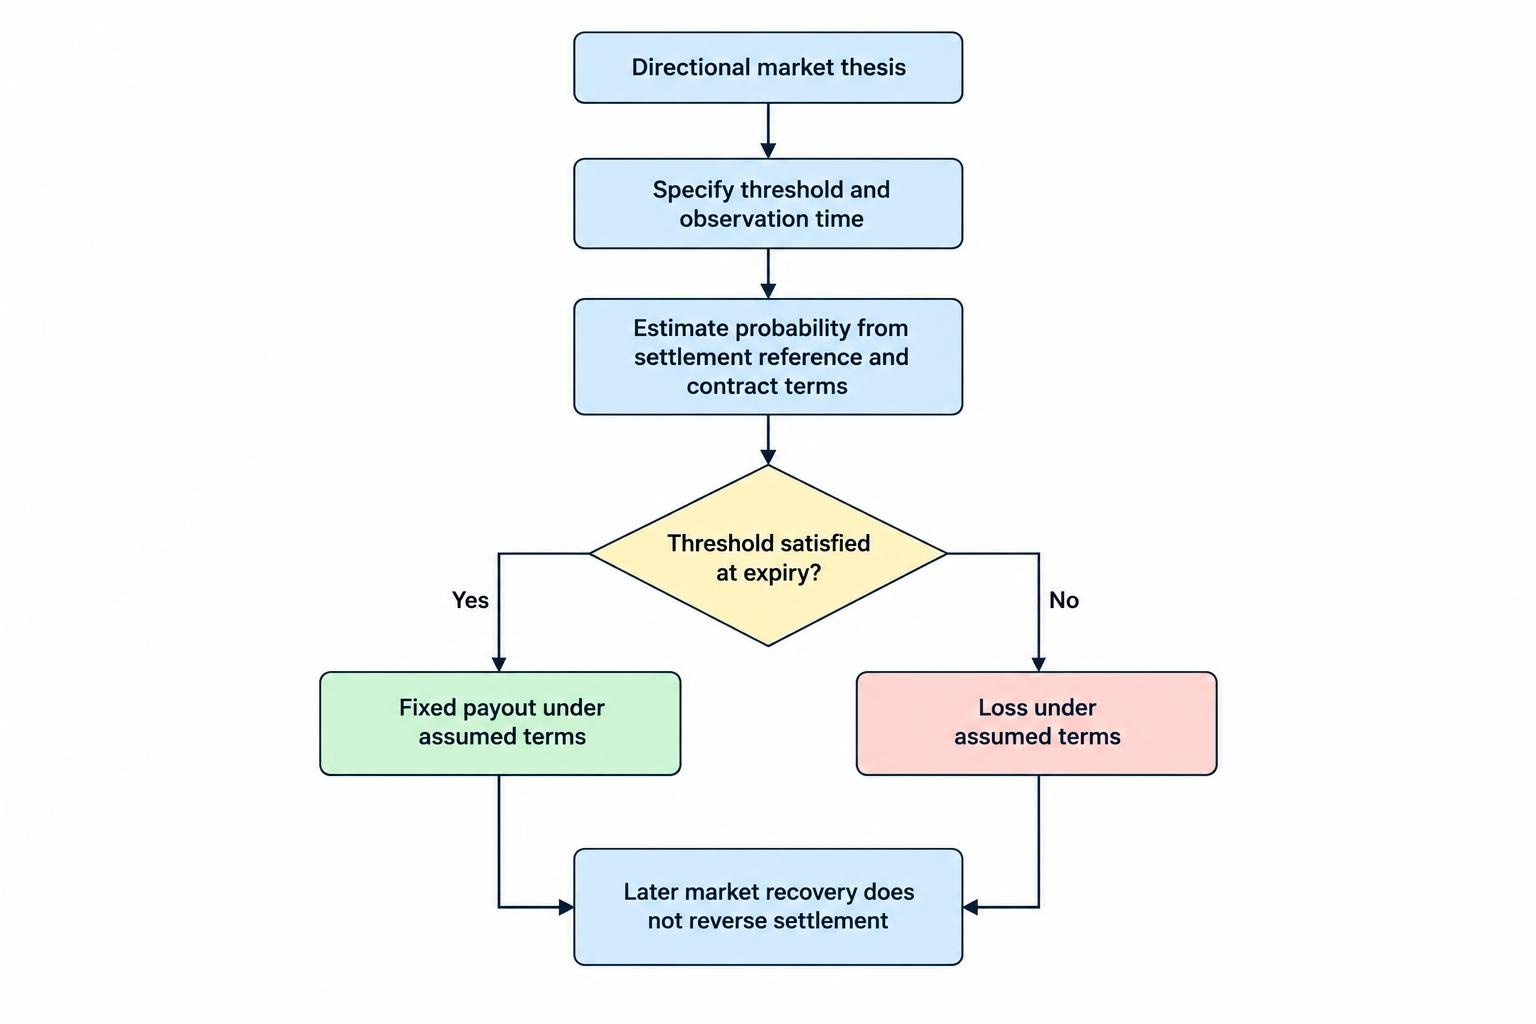
Consider a hypothetical contract paying a fixed amount if an index finishes above 8,000 at 4 pm. If the settlement value is 8,001, the condition is satisfied. If it is 8,300, the same fixed payment applies. The much larger index rise produces no additional contractual reward.
If the index finishes at 7,999, the contract loses under the assumed terms. A recovery to 8,100 after expiry does not reverse that settlement. The trader’s view about the market’s eventual direction may prove correct while the purchased contract still loses.
This is why comparisons between binary options and share dealing need to focus on rights and payoff rules. Referencing the same price does not create equivalent exposure.
Nor does a binary contract necessarily pass through dividends, interest or other benefits associated with the reference asset. An announced dividend may influence the price used for settlement, but that is different from the contract holder becoming entitled to the dividend itself.
Payouts and break even arithmetic
The advertised payout deserves close attention because the terminology can obscure the amount actually earned. An “80% payout” may mean an 80% net profit on a successful stake, with the original stake also returned. It must not be confused with receiving only 80% of the stake back.
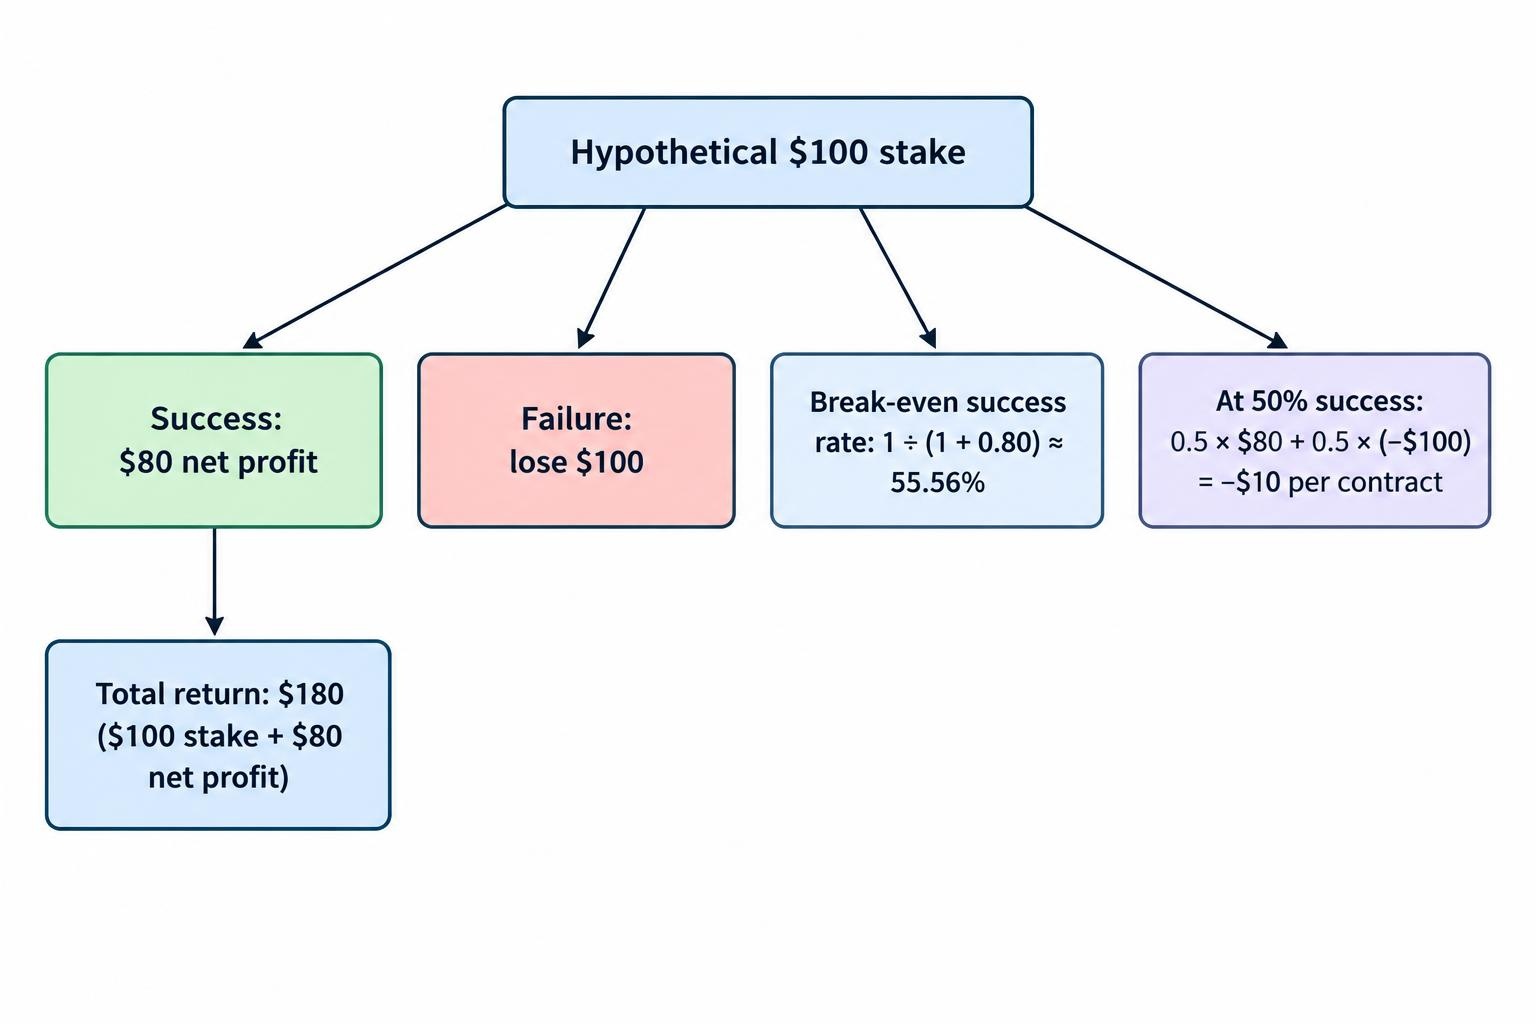
For the following illustrations, assume a $100 stake, an $80 net profit on success and a $100 loss on failure. A successful contract returns $180 in total. An unsuccessful contract returns nothing. These are hypothetical terms, not a statement about every provider or a current offer available to Australian retail clients.
Winning half the time produces a loss
With those terms, ten successful contracts produce $800 in profit. Ten unsuccessful contracts lose $1,000. Across twenty contracts, the net result is a $200 loss, even though the trader was correct half the time.
The arithmetic also shows why counting successful predictions is insufficient. Profitability depends on the size of gains relative to losses. A trader can win more often than they lose and still finish behind if the winning payment is too small.
For a constant stake, a full loss on failure and no additional costs, the break even success rate equals one divided by one plus the net profit rate. At an 80% net profit rate, the calculation is 1 ÷ 1.8, or approximately 55.56%.
| Assumed net profit on a successful $100 stake | Total returned on success | Loss on failure | Success rate needed to break even |
|---|---|---|---|
| 70% | $170 | $100 | 58.82% |
| 80% | $180 | $100 | 55.56% |
| 90% | $190 | $100 | 52.63% |
| 100% | $200 | $100 | 50.00% |
The table isolates the payout structure. It excludes fees, refunds, ties and changes in stake size. If the terms differ, the calculation must change. A quoted percentage alone is not enough to establish the full cost or expected result.
Expected return requires a probability estimate
Expected return is the probability weighted average of the possible results. Suppose the chance of success in the $100 example is genuinely 50%. The expected result is half of an $80 gain combined with half of a $100 loss, producing an expected loss of $10 per contract.
If the true success probability were 60%, the same calculation would produce an expected gain of $8. This does not show that such a probability is achievable. It shows why the payout imbalance alone does not prove that every conceivable trader must lose on every possible contract.
The practical difficulty is establishing a reliable probability estimate before committing money. Seeing an upward trend is not equivalent to demonstrating a 60% chance of satisfying an exact settlement condition. A short record of wins can arise by chance, and results obtained under one set of conditions may not persist.
Changing payouts also changes the required forecasting performance. A strategy with a 55% success rate would have a positive expected result at a 90% net profit rate, before costs, but a negative expected result at an 80% rate. The market signal could remain identical while the economics deteriorate.
A fixed maximum loss is not a low risk product
Knowing the maximum loss on one contract can make the exposure easier to describe. It does not make that loss small or unlikely. Losing a $100 stake is a 100% loss on that position, even if the trader has more money elsewhere.
The same distinction applies to a portfolio. A stake representing 1% of an account caps the direct loss on that contract at 1% of the starting account balance under the assumed terms. Repeating the trade can still produce a much larger cumulative loss.
The details of broker payouts and contract terms therefore matter more than the simplicity of the trading buttons. The settlement threshold, treatment of equal prices, expiry timestamp, refund rules and any early closing facility all affect the actual proposition being purchased.
Expiry and forecasting
A binary option combines a market forecast with a deadline. Being right about direction is only part of the task. The result must meet the stated condition at the relevant observation time, or over the relevant observation period for contracts with different designs.
Not every binary contract lasts seconds or minutes. Moneysmart describes durations ranging from minutes or hours to months. A longer expiry changes the forecasting problem but does not turn the contract into ownership of the underlying asset.
A correct thesis can produce a losing contract
Suppose a trader expects the Australian dollar to strengthen after an economic release. The currency initially falls, then rises over the following afternoon. A contract expiring during the initial decline can lose even if the broader view proves accurate.
An investor with an appropriate ongoing position may retain exposure through that sequence. The binary holder’s position can already be settled and finished. Buying another contract creates a fresh transaction with new terms and another amount at risk.
This does not mean patience always rescues an investment. A falling share may reflect permanent business deterioration. It means that the binary holder cannot rely on later developments to repair an expired contract.
The threshold also matters independently of direction. A market can rise while remaining below the level needed for a successful contract. A forecast that “prices will probably increase” contains less information than a forecast about the probability of finishing above a particular threshold at a particular time.
Timing precision creates additional uncertainty
At a short horizon, a small difference in the reference price or observation time can decide the full payout. A trader may see one price on an independent chart and another on the contract’s settlement record. That discrepancy needs to be assessed against the agreed data source and timestamp, rather than assuming every chart represents the same observation.
The relevant distinction is between the price a trader happens to observe and the price the contract specifies for settlement. Price feeds and benchmarks can differ in construction, update frequency and the market they represent.
A hypothetical contract based on a bid price, for example, need not settle identically to one based on the midpoint between bid and ask. The difference can be financially decisive near the threshold, even if it looks negligible on a chart.
Research into earnings, economic conditions or valuation may inform a directional view. It does not remove the separate need to estimate the timing and distribution of possible prices. That additional requirement is one reason a persuasive investment thesis can be poorly matched to a binary payoff.
Risk controls and repeated trading
Risk management can change how much money is exposed and how losses accumulate. It cannot, by itself, convert an unfavourable contract into a favourable one. Reducing a stake from $100 to $10 reduces the dollars at risk; it leaves the assumed percentage payout and break even success rate unchanged.
The distinction is useful because a disciplined process can still implement a strategy with negative expected returns. Keeping a journal, following predetermined entry rules and avoiding impulsive decisions may improve consistency without establishing that the underlying decisions are profitable.
More trades do not create an advantage
Under the earlier hypothetical assumptions of a 50% success probability and an 80% net profit on wins, each $100 contract has an expected loss of $10. One hundred such contracts have an expected total loss of $1,000 if those assumptions remain valid.
That figure is an average across possible outcomes, not a forecast that every account will lose exactly $1,000. The realised result could be better or worse. The point is that increasing activity increases exposure to the same unfavourable terms.
Reinvesting proceeds does not change that relationship. Compounding magnifies the effect of returns on a changing capital base. It is not an independent source of profit. Repeatedly putting money back into a losing process can compound losses.
A small initial deposit can therefore conceal a large cumulative commitment. If an account is repeatedly replenished, the appropriate performance calculation includes every deposit and withdrawal, rather than comparing the current balance only with the latest top up.
Increasing stakes after losses changes the exposure
A loss recovery system may increase the next stake to recover earlier losses. Under an 80% net profit rate, a $200 winning stake earns $160. If it follows a $100 loss, the combined profit is $60, rather than the $80 earned by an initial $100 win.
After losses of $100 and $200, a $400 winning stake earns $320, leaving only $20 after those earlier losses. After losses of $100, $200 and $400, an $800 win earns $640 and still leaves the sequence $60 behind.
This illustrates the problem with simple doubling under a payout below 100%. The amount exposed grows rapidly, while the recovery arithmetic differs from an even money wager. Discussions of Martingale in binary options trading need to account for this mismatch.
A trader can also reach a platform’s stake limit or exhaust available funds before a recovery occurs. An approach that appears successful through many short sequences may concentrate its losses into a less frequent but much larger event. The frequency of profitable sessions is not a substitute for measuring total returns and maximum losses.
Australian regulation and platform risk
ASIC’s intervention addressed the characteristics of the product as well as the conduct of providers. Its analysis before the extension used data from five licensed issuers. In the 13 months before the ban, 74–77% of active retail clients lost money and retail accounts recorded aggregate net losses of $14 million.
Those figures, reported in ASIC’s ban extension announcement, describe the observed client population and period. They are not a forecast of the exact probability that any individual contract will lose.
The involvement of licensed issuers matters. It contradicts the idea that the problem could be solved entirely by avoiding visibly unregulated websites. A product can produce poor consumer outcomes even when the business offering it operates within a licensing framework.
The Australian restriction concerns retail distribution
The ban applies to issuing and distributing binary options to retail clients. It should not be described loosely as a universal prohibition on every binary derivative transaction everywhere. Legal classifications and product definitions matter, especially when comparing jurisdictions.
An overseas website’s willingness to accept an Australian customer does not establish that its service complies with Australian requirements. Nor does displaying a foreign licence establish permission to supply every financial product to Australian retail clients.
Moneysmart also warns against agreeing to wholesale classification merely to access binary options. Wholesale clients do not receive the same consumer protections as retail clients. Reclassification is not a change to the payout mathematics or an improvement in the underlying financial proposition.
The United Kingdom provides another example of product intervention. The Financial Conduct Authority’s permanent rules, effective from 2 April 2019, prohibited firms acting in or from the UK from selling, marketing or distributing binary options to retail consumers. That is a jurisdiction specific restriction, rather than evidence of one uniform worldwide rule.
Contract losses and platform failures are different risks
Even if a contract is settled accurately and a provider honours withdrawals, the trader can lose money through the payoff structure. Platform misconduct creates another layer of exposure on top of that trading risk.
The joint SEC and CFTC investor alert on binary options fraud records complaints involving withheld funds, identity theft and software manipulation. These are documented categories of alleged misconduct; they do not establish that every binary options provider engages in the same behaviour.
Counterparty risk is the risk that the other party fails to meet its obligations. For a trader, a winning result on screen has little practical value if the amount cannot be withdrawn. Operational records, settlement calculations and the legal identity of the contracting entity matter separately from the direction of the market.
There can also be a conflict of interest where a provider takes the other side of customer contracts and retains exposure to customer losses. The exact economics depend on its business model and any hedging. A conflict is a reason to examine incentives and controls, not proof that a particular quote was manipulated.
These distinctions help separate counterparty and platform risk from an ordinary losing prediction. Better forecasting cannot prevent an insolvent or dishonest counterparty from failing to pay. Equally, an honest counterparty does not make an unfavourable payout attractive.
Comparing binary options with investments
A useful comparison starts with the purpose of the exposure. An investor accumulating retirement savings, a business managing currency risk and a trader speculating on tomorrow’s price move have different objectives. Using the same market as a reference does not mean one instrument can perform all three tasks equally well.
| Feature | Retail style binary contract | Ordinary shares | Conventional fixed rate bond | Broad share ETF |
|---|---|---|---|---|
| Economic interest | Claim on a defined event payoff | Ownership interest in a company | Debt claim against an issuer | Units in a fund |
| Main return source | Contract condition being satisfied | Price changes and possible dividends | Contractual payments and price changes | Portfolio returns less costs |
| Typical exposure | Ends at contract settlement | Continues while shares are held | Continues until sale or maturity | Continues while units are held |
| Effect of a larger favourable move | May leave the fixed payout unchanged | Usually increases the holding’s value | Depends on bond pricing | Usually affects the fund’s value |
| Principal risk | Full stake can be lost | Company value can fall or collapse | Default and market value losses | Underlying investments can fall |
The table describes common structures, rather than every product variation. A concentrated ETF, a distressed bond or a speculative share can be highly risky. Conventional packaging alone does not make an investment appropriate.
Derivatives can have legitimate portfolio uses
Lack of underlying ownership is not sufficient grounds to dismiss every derivative. A derivative can be used to offset an existing exposure. The relevant issue is how its payoff interacts with the risk being managed.
For example, Moneysmart explains that put options can be used to protect an investment against falling prices. These contracts have costs and expiry dates, and their protection depends on their terms. They are not the same as repeatedly buying fixed payout contracts in the hope of growing an account.
The comparison between binary options and vanilla options therefore concerns payoff design and use, rather than whether the word “option” appears in the name. A derivative used for hedging can reduce a portfolio exposure even when the derivative itself loses money.
Wealth building requires a different framework
For a long term portfolio, the relevant questions concern expected income, growth, valuation, costs, liquidity and the ability to tolerate losses. Moneysmart’s diversification guidance explains how spreading exposure across investments can reduce the effect of individual holdings performing poorly. Diversification cannot eliminate market risk or guarantee a positive return.
Placing binary contracts on several different markets does not automatically create the same benefit. Even if their outcomes are independent, combining contracts with negative expected returns does not make the combined expected return positive. It changes the distribution of outcomes while leaving the underlying arithmetic intact.
Binary options can be described accurately as financial contracts used for event speculation. Presenting them as a straightforward substitute for accumulating income producing or growth assets conceals the differences that matter: the rights acquired, the source of return, the expiry condition and the terms of loss. For Australian retail clients, those economic concerns sit alongside a clear restriction on their issue and distribution.
This article was last updated on: October 22, 2026