A binary options broker may be a dealer selling its own contracts, an intermediary providing access to an exchange, or a brand using another company’s trading software. Those arrangements can look similar on screen while creating different pricing, settlement and counterparty relationships.
The most useful distinction is between exchange trading and over the counter dealing. Other descriptions, including offshore, multi-asset and white-label, identify where a firm operates, what it sells or how its technology is supplied. They are not separate legal categories, and they can overlap. One business could be an offshore OTC dealer operating through a white-label platform.
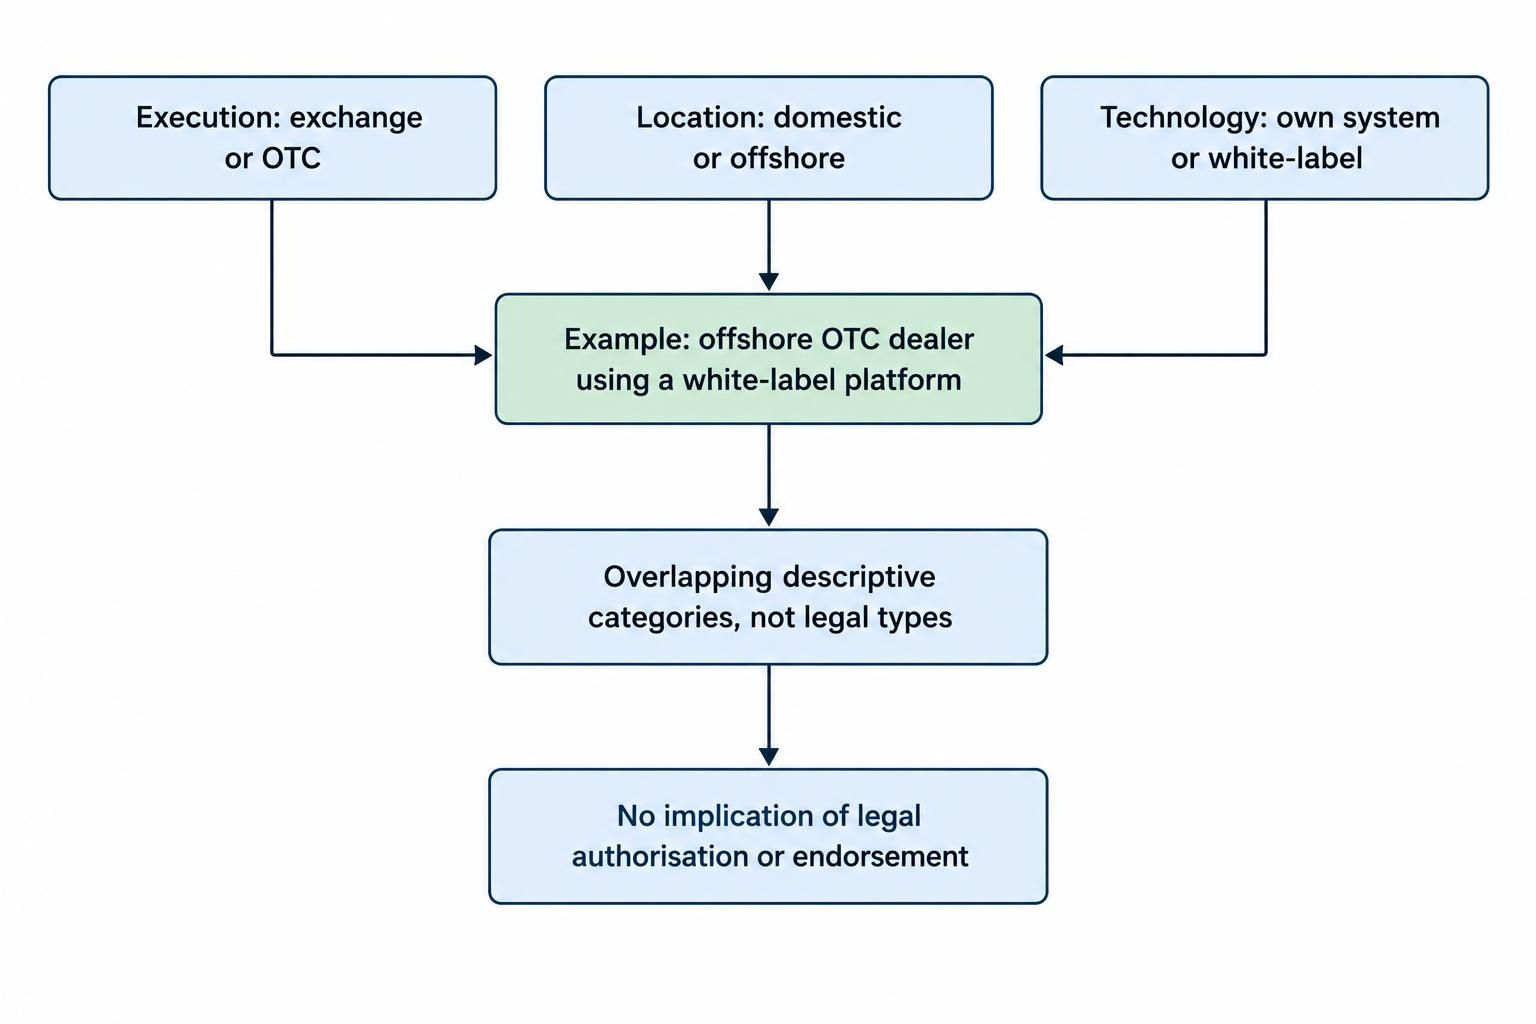
For Australians, the comparison begins with the product restriction. ASIC has banned the issue and distribution of binary options to retail clients, with the order extended until 1 October 2031. An overseas licence, exchange label or familiar brand does not by itself establish that a product can lawfully be offered to an Australian retail customer.
Comparing the main types of binary options brokers
The table compares business models and operating arrangements. Its advantages concern particular features of a structure, rather than an endorsement of binary options or a claim that a provider is available in Australia.
| Broker or platform type | Pricing and execution | Contractual structure | Main advantage | Main limitation |
|---|---|---|---|---|
| Exchange venue and access broker | Orders interact under venue rules; prices may be visible in an order book | Exchange contracts with specified clearing arrangements | More observable pricing and formal market rules | Fees, spreads and liquidity still affect returns |
| OTC binary options dealer | Dealer quotes contract terms and accepts the trade | Customer contracts directly with the issuing dealer | Stake and expiry payoff can be easy to calculate | Dealer incentives and payout terms require scrutiny |
| Offshore broker | Depends on whether it uses an exchange or dealer model | Customer contracts with an overseas entity | Localised services may suit eligible clients in its permitted markets | Foreign incorporation does not establish suitable supervision or Australian authorisation |
| Multi-asset or hybrid broker | Different products may use different execution arrangements | One or several entities provide products under a shared brand | Shared interface and account administration | Protections and risks can differ between product accounts |
| White-label broker | Technology comes partly or wholly from another business | Brand, software supplier and issuer may be different entities | Shared systems can support consistent functionality | Responsibility and shared dependencies can be difficult to identify |
| Crypto and prediction platform | May use an order book, dealer quotes or automated pricing | Structure varies; settlement may use cash or tokens | Some designs expose trading or settlement records | Custody, resolution and legal access can add risks |
A provider’s label answers only part of the question. An order book does not establish regulatory status, and an overseas address does not establish misconduct. The meaningful assessment connects the legal entity, product terms, execution process and arrangements for holding and returning customer money.
Australian rules and overseas regulation
ASIC’s restriction took effect on 3 May 2021. Its later analysis of five licensed binary options issuers found that 74–77% of active retail clients lost money during the 13 months before the ban. Retail accounts recorded aggregate net losses of $14 million. These were observations about those clients and that period, not the probability of losing any particular trade.
The inclusion of licensed issuers matters. It shows why licensing alone did not resolve the consumer harm associated with the products. A firm can satisfy a licensing framework while selling a product that regulators subsequently restrict.
Foreign regulation does not establish Australian access
An overseas regulator may supervise a venue, intermediary or dealer for customers within its jurisdiction. That does not automatically authorise the same business to solicit Australian retail clients or distribute a prohibited product here. Product definitions, client classification and the service being provided all matter.
Moneysmart warns against accepting wholesale classification simply to access binary options. Wholesale clients do not have the same consumer protections as retail clients. Changing classification does not improve a contract’s payout or remove counterparty exposure.
The United Kingdom has its own restriction. The FCA’s permanent rules, effective from 2 April 2019, prohibited firms acting in or from the UK from selling, marketing or distributing binary options to retail consumers.
European history also needs precise wording. The European Securities and Markets Authority, or ESMA, imposed temporary intervention measures. It stopped renewing its temporary binary options prohibition in July 2019 because most national authorities had adopted permanent measures at least as stringent. Describing today’s position solely as an unchanged temporary ESMA ban misses that transition.
These distinctions prevent a common error in broker comparisons: treating “regulated somewhere” as equivalent to “authorised for this customer and product”. A licence must match the entity and activity being assessed. It is also separate from the question of whether the trading proposition is economically attractive.
Exchange venues and access brokers
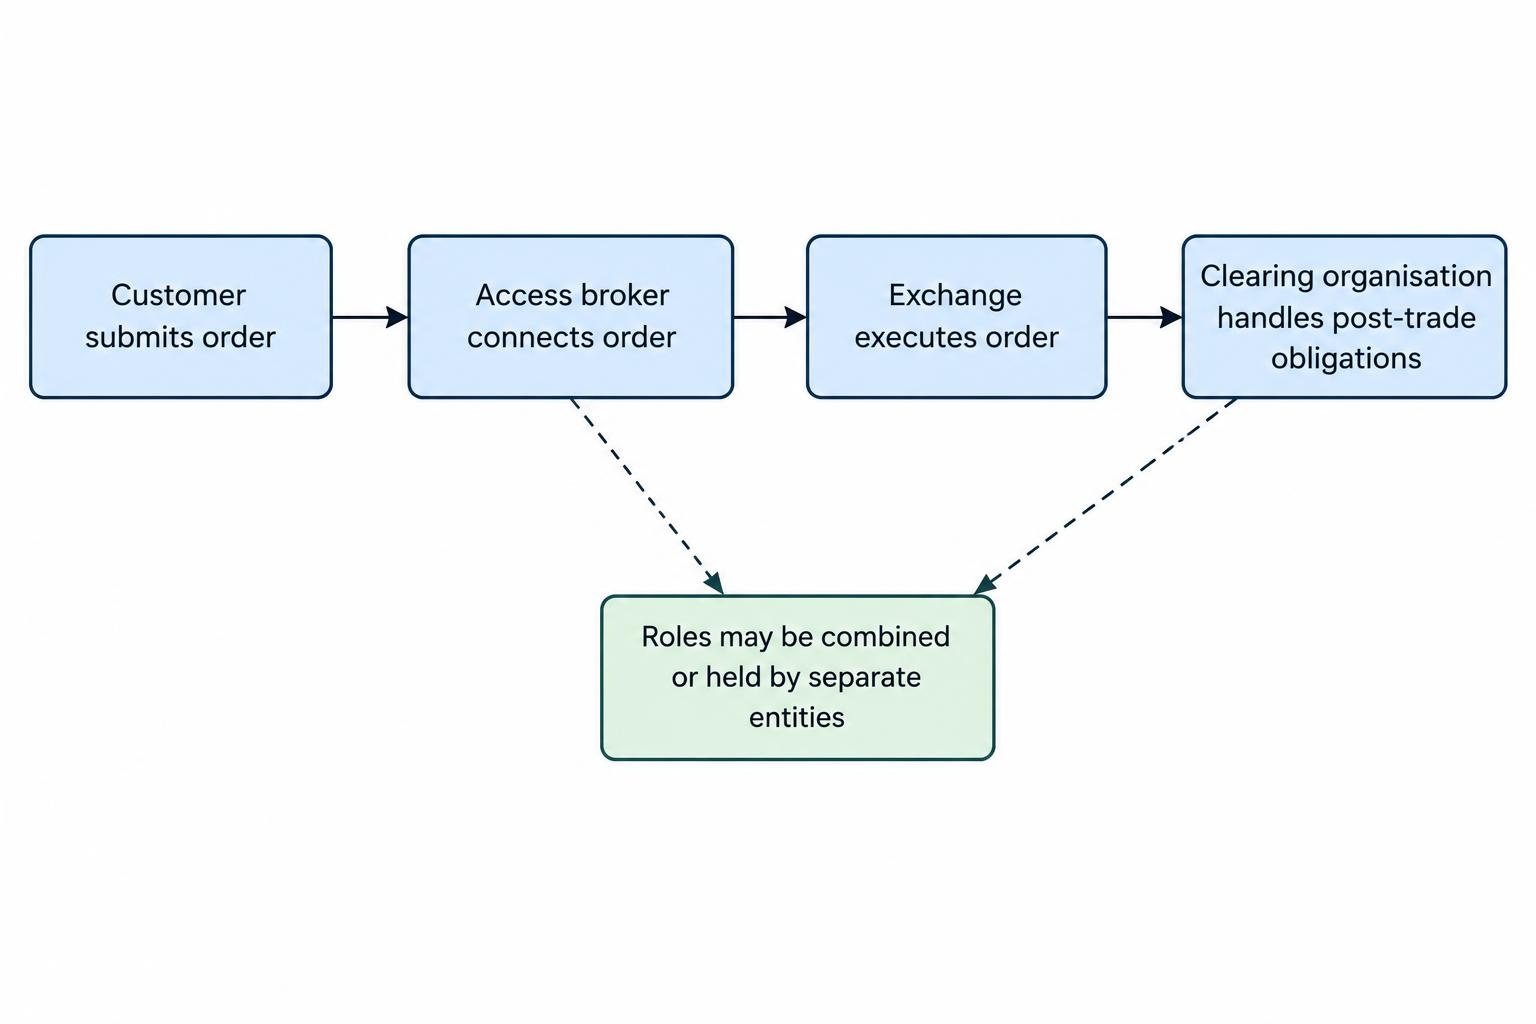
An exchange establishes the rules under which contracts trade. An access broker receives customer orders and connects them to the venue. A clearing organisation handles specified obligations after execution. Some businesses combine roles, while others use separate entities.
Calling all of them “brokers” conceals those differences. A customer may interact only with an app, yet the trading venue, account provider and clearing arrangements can sit elsewhere in the transaction chain.
Pricing comes from the market structure
In a conventional order book, participants submit prices at which they are willing to buy or sell. The best displayed buying price is the bid, and the best displayed selling price is the offer. Their difference is the bid–ask spread.
Consider a hypothetical contract paying $100 if an event occurs and zero otherwise. Buying it for $40 creates a possible $60 profit or $40 loss before fees. Paying $70 for the same terminal payoff changes the possible profit to $30 and the possible loss to $70.
CME Group’s event contract example illustrates this distinction between the purchase price and the fixed settlement payment. A fixed final payout does not mean every buyer receives the same percentage return.
A $40 price on a $100 payoff is sometimes described as a 40% implied probability. That interpretation requires care. Fees, liquidity, participants’ risk preferences and market imperfections can separate a traded price from the actual likelihood of the event. The price is observable; the true probability is not.
Clearing changes the counterparty arrangement
It is inaccurate to say that a customer in a centrally cleared market simply relies on an anonymous trader to pay. As CME explains its clearing model, the clearing house stands between buyers and sellers.
The customer’s direct legal rights still depend on the access arrangement and any intermediary. Central clearing manages counterparty risk through rules and financial safeguards. It does not eliminate operational failures, intermediary risk or losses from the trade itself.
Market makers may supply much of the available liquidity. A displayed order book therefore does not imply equal bargaining power or guarantee that a retail participant can exit a large position at the quoted price.
Pros and cons of exchange venues and access brokers
| Pros | Cons |
|---|---|
| Published contract rules make the settlement condition and market procedures easier to inspect. | A clearly written contract can still produce a full loss of the purchase price. |
| Displayed bids and offers allow comparison of available prices and spreads. | Thin liquidity can make entry or early exit expensive; displayed quantities may be small. |
| Formal clearing arrangements can reduce dependence on one trading counterparty. | Clearing safeguards do not remove broker, custody, operational or market risk. |
| Trading charges can be disclosed separately from contract prices. | Commissions and spreads can absorb a large share of the expected profit on small contracts. |
Suppose a trader pays $40 for the hypothetical $100 contract and incurs a $1 entry fee, with no other charges. The event must have a probability above 41% for the expected net result to be positive. A belief that the contract is “cheap” is insufficient without a defensible probability estimate.
An exchange structure can improve transparency and enforce trading rules. Those benefits should be assessed separately from access eligibility and profitability. They do not turn a short term event position into an investment in the underlying shares, currency or commodity.
OTC binary options dealers
OTC means over the counter: the contract is agreed outside an exchange. In the familiar retail binary model, the provider issues the contract, quotes its payout and takes the other side of the customer’s transaction.
This makes “dealer” a more informative description than “broker” when the firm acts as principal. A broker acting as an intermediary arranges a transaction; a principal enters it for its own account. The account agreement should identify which role applies.
The dealer sets the offered terms
An OTC platform might offer a $100 stake with an $80 net profit if the condition is satisfied and a $100 loss if it is not. A successful result returns $180 in total, including the original stake.
That is different from an exchange contract purchased for $40 and paying $100 at settlement. Comparing an “80% payout” with a “$100 payout” without adjusting for the purchase cost would compare different quantities.
For the $100 stake example, the break even success rate is 100 ÷ 180, or approximately 55.56%, before additional costs. Ten winning trades earn $800; ten losing trades lose $1,000. Being correct half the time leaves a $200 loss across those twenty equal stakes.
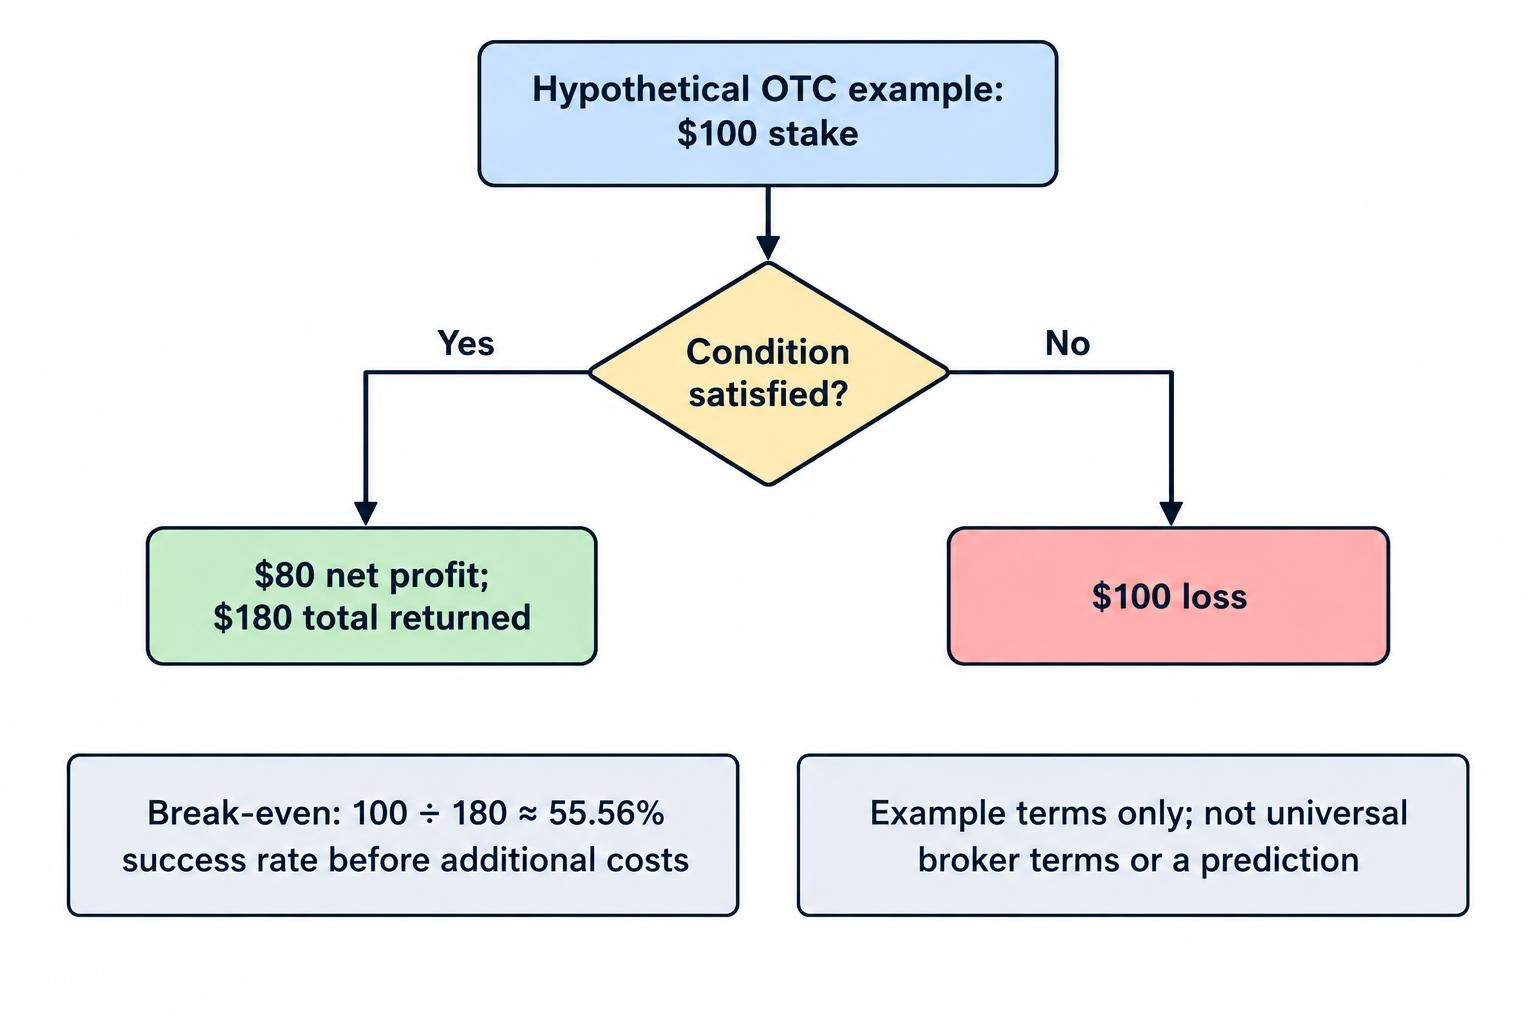
The success probability is an assumption requiring evidence. A binary outcome does not automatically mean a 50% chance of either result. An event can have two outcomes while one is much more likely than the other.
Dealer incentives and hedging
If a dealer retains customer exposure, customer losses contribute to its trading result and successful customer contracts create payment obligations. The firm may offset some exposure through other transactions or hedges. That can change its net financial incentives without changing the customer’s contractual counterparty.
These mechanics explain how binary options brokers make money. A dealer may incorporate a margin in the quoted terms even when there is no separately itemised commission.
A conflict of interest is not proof of manipulation. The concern is that a firm may control several parts of the transaction while benefiting from customer losses. Pricing methods, settlement records, complaints handling and supervision become especially relevant.
The joint SEC and CFTC investor alert records complaints about withheld funds, misuse of personal information and software manipulation. Those documented allegations should not be turned into a claim that every OTC provider engages in fraud.
Pros and cons of OTC binary options dealers
| Pros | Cons |
|---|---|
| An accepted contract can specify the stake and expiry outcome clearly. | A simple payoff can still have an unfavourable expected return. |
| A dealer quote can be accepted without waiting for a matching customer order. | The dealer controls the terms it offers and may reject or change quotes before acceptance. |
| Contract sizes may be flexible where the provider supports them. | Small stakes do not prevent large cumulative losses through repeated trading. |
| A straightforward interface can make the basic transaction easy to understand. | Early exit may be unavailable or depend entirely on the dealer’s quoted price. |
The distinction between a quote changing before acceptance and a confirmed contract changing afterwards is important. A live offer need not remain available indefinitely. Once accepted, however, the applicable terms determine what can be amended, cancelled or corrected.
Detailed broker payouts and contract terms should explain the reference price, expiry time, treatment of equal prices and any correction provisions. An attractive headline percentage cannot substitute for those details.
Offshore binary options brokers
“Offshore” describes location relative to the customer. It does not identify one trading model or one standard of regulation. A foreign firm might be closely supervised, lightly supervised or operating without the permissions its activities require.
The relevant questions concern the actual jurisdiction and entity. A company registration certificate establishes incorporation; it does not, by itself, establish permission to provide financial services.
The contracting company determines the relationship
A group can operate several companies under one brand. The company named in an advertisement may differ from the entity named in the customer agreement. A licence held by one group member does not automatically cover another member’s activities.
Consider a hypothetical brand with a licensed domestic securities business and a separate overseas derivatives company. Opening the derivatives account may create a relationship only with the overseas company. The domestic business’s reputation does not establish which safeguards govern that account.
Moneysmart’s guidance on checking an investment provider stresses verifying the licence holder, its permissions and its identity. It also warns that scammers can impersonate genuine licensed firms.
The same reasoning applies to website domains and payment instructions. A familiar trading name, copied licence number or professional design cannot establish that the person receiving the deposit represents the authorised business.
Recourse depends on more than distance
Cross-border disputes can involve foreign complaint procedures, courts, languages and enforcement costs. The size of a claim may be small relative to the cost of pursuing it. An enforceable judgment also has limited practical value if the relevant assets cannot be located.
These difficulties are not unique to binary options, and they do not justify assuming that every foreign provider is dishonest. They explain why contractual protections and realistic recovery routes matter before money is transferred.
Pros and cons of offshore brokers
| Pros | Cons |
|---|---|
| Some overseas firms provide language, currency or service arrangements suited to their permitted customer base. | Those features do not establish lawful access for Australian retail clients. |
| A foreign entity may operate under a recognised supervisory framework in its home market. | The exact licence and permissions can differ from what a brand’s advertising implies. |
| Separate regional entities can adapt services to local requirements. | Customers may be assigned to an entity with different protections from the one they expected. |
There is no inherent customer advantage in weaker oversight. Any claimed benefit should be traced to a concrete service feature, not to the absence of restrictions.
The practical exposure is counterparty and platform risk: whether the contracting company can and will honour its obligations, and what remedy exists if it does not. A high displayed account balance is not equivalent to accessible money.
Multi-asset and hybrid brokers
A multi-asset broker offers several product categories under one brand or interface. A hybrid arrangement may also combine execution models, routing some orders to outside venues while dealing as principal in others.
Neither description establishes how the binary options account works. Shares, CFDs, conventional options and binary contracts can appear in adjacent menus while creating different rights and losses.
Shared screens can conceal separate arrangements
The difference between binary options and CFDs begins with the payoff. A conventional CFD tracks changes in the underlying price, subject to position size and its terms. A binary contract pays according to a specified condition.
Putting both products in one app does not remove that difference. A charting tool may be shared, while the settlement source, issuer, fees and customer protections remain separate.
A hypothetical customer could hold a share account with one company and a derivatives account with another group company. A transfer between the two may involve more than moving a number between screen tabs. It can change the entity holding the funds and the legal terms that apply.
An available balance also needs interpretation. Money allocated as collateral or committed to an open position may not be freely withdrawable. A dashboard combining several balances can be convenient without representing one legally interchangeable pool.
Pros and cons of multi-asset and hybrid brokers
| Pros | Cons |
|---|---|
| Shared navigation, charting and reporting can reduce administrative effort. | A common interface can obscure different issuers, account agreements and protections. |
| Customers may be able to compare several product structures in one place. | Familiarity with one product can create misplaced confidence in another. |
| Consolidated records may help track deposits, trades and withdrawals. | Combined balances can be misunderstood if some funds are committed or held by separate entities. |
Convenience is the main potential benefit. It should not be treated as evidence that the binary product inherits the protections attached to another service.
The word “regulated” needs the same precision here as elsewhere. A firm’s permission to arrange share transactions does not establish permission to issue every derivative. The product, service, legal entity and customer location must all fit the claimed authorisation.
Where a platform provides early exit, the mechanism also matters. Selling a position into a market is different from accepting a discretionary repurchase quote from the issuer. Similar interface buttons can perform economically different transactions.
White-label binary options brokers
A white-label arrangement allows a business to offer technology or services developed by another company under its own branding. The supplier might provide charts, account administration, pricing tools, payment integrations or a complete trading system.
White-labelling describes outsourcing and presentation. It does not establish whether the branded firm acts as broker or dealer, whether it holds a licence, or who owes money to the customer.
Technology and contractual responsibility can be separate
The platform operator, branded customer service team, contract issuer and payment processor may be different businesses. Their roles need to be established through the agreements and disclosures, rather than inferred from the logo.
Two websites using similar software are not necessarily owned by the same group. Conversely, different designs do not prove independent ownership. Shared technology creates a connection, but the nature of that connection requires evidence.
The model has appeared in enforcement cases. In its 2021 action concerning Spot Option, the SEC alleged that the supplier licensed a trading platform and related services to white-label partners that marketed binary options. It also alleged that customers were not told the partners acted as counterparties. These were allegations described in that enforcement announcement, not a finding that all white-label arrangements are fraudulent.
The broader lesson is about accountability. Outsourcing software does not answer which company must correct a settlement error, process a withdrawal or respond to a complaint.
Shared systems create shared dependencies
A white-label operator may rely on its supplier for pricing, account records or technical support. If that supplier suffers an outage, changes its service or becomes insolvent, several brands can be affected.
For example, changing from Brand A to Brand B may leave a customer using the same technology provider. That does not necessarily leave the customer with the same counterparty, but it may preserve the same operational dependency.
This is relevant when assessing closed and renamed broker brands. The history of an entity and its suppliers can be more informative than the age of a newly registered website.
Pros and cons of white-label brokers
| Pros | Cons |
|---|---|
| An established software supplier may provide tested account and trading functions. | Software quality does not establish honest dealing, solvency or regulatory permission. |
| Shared systems can reduce duplicated development costs. | Lower operator costs are not necessarily passed through in customer pricing. |
| A common platform can provide familiar controls across brands. | Several brands may share outages, pricing dependencies or other technical weaknesses. |
| Outsourcing can let the operator focus on customer administration. | Customers may struggle to identify which business is responsible when problems arise. |
Signal sellers and copy trading services can sit alongside this structure without being brokers themselves. A referral service may introduce customers to the issuer; a signal service may supply suggested entries; a copying tool may transmit orders. Each role has different incentives.
A hypothetical referral payment based on deposits rewards account acquisition, while a payment based on trading volume rewards activity. Neither necessarily rewards customer profitability. The actual remuneration agreement matters more than a promoter’s description of the service as free.
Likewise, copy trading changes who selects or transmits a trade. It does not change the contract’s payout or the identity of the issuer. Delays and differing entry prices can also make a copied result diverge from the displayed performance being followed.
Crypto platforms and prediction markets
Crypto funding and prediction markets are related to the broker discussion because they can package similar event payoffs in different forms. They should not be treated as a single legal category or assumed to share one execution model.
A platform might offer contracts referencing cryptocurrency prices while settling in ordinary currency. Another might accept tokens as collateral or pay winnings in tokens. The reference asset and the settlement asset are separate features.
Token settlement adds another exposure
Suppose a hypothetical account increases from ten tokens to eleven through trading. If each token falls from A$100 to A$80, the account’s value declines from A$1,000 to A$880 despite the larger token balance.
A token denominated profit is therefore not necessarily an Australian dollar profit. Stablecoins aim to track a reference value, but the design and supporting arrangements still matter. Moneysmart’s explanation of crypto assets distinguishes these designs and describes risks associated with holding and storing crypto.
Custody is another separate question. A platform balance may represent a claim against an operator, while a wallet controlled by the user involves responsibility for access credentials. Neither arrangement establishes how an event contract’s outcome will be determined.
Resolution rules determine the event outcome
Prediction contracts can concern economic data, policy decisions or other events. The wording must identify the authoritative source, observation date and treatment of revisions or cancellations.
For example, a contract based on the first published inflation figure can settle differently from one based on a later revised series. Both may use official data, but they answer different questions.
As checked on 21 October 2026, Moneysmart states that no prediction market operators are licensed as financial markets in Australia. It also identifies similarities between event contracts and binary options. An overseas platform’s popularity does not establish Australian authorisation.
Pros and cons of crypto and prediction platforms
| Pros | Cons |
|---|---|
| Some platforms make prices, transaction records or settlement rules publicly observable. | Observable records do not guarantee correct data, lawful access or recoverable funds. |
| Clearly specified event contracts can express a narrow view on an outcome. | Ambiguous wording, revisions and disputed results can complicate settlement. |
| Token transfers can support settlement outside traditional banking hours. | Token value, custody, network costs and transfer errors add separate risks. |
The comparison between binary options and prediction markets therefore requires examination of the actual contract and venue. Changing the funding method or marketing label does not automatically change the economic exposure.
Assessing the firm behind the platform
The starting point is the company named in the account agreement. Its role should be consistent with the execution description, product issuer and payment destination. A discrepancy needs an explanation before the brand can be assessed meaningfully.
Commercial directories such as BinaryOptions.net publish broker reviews and comparisons. A review can describe a platform, but its ranking does not establish authorisation, contractual rights or the customer’s protection if the firm fails. Those matters require the relevant regulator records and legal documents.
The same separation applies to performance. A dealer can honour every contract and still offer terms under which a customer’s strategy loses money. An exchange can provide transparent execution without making a trader’s probability estimates accurate. Good administration and profitable speculation are different questions.
Settlement and withdrawal terms deserve separate attention
The contractual record should make clear which price or event determines the result and how an error is handled. Price feeds and benchmarks matter because a chart from another source may not reproduce the specified settlement observation.
Deposits and withdrawals involve a separate process. An account showing a winning contract does not establish when the proceeds become available, what verification is required or which company must return them.
Broker type is useful because it identifies where to look for these answers. Exchange and OTC models explain execution and contractual exposure. Offshore status identifies a jurisdictional relationship. Hybrid and white-label arrangements reveal possible divisions between products, entities and suppliers. None of those labels substitutes for the underlying documents or changes Australia’s restriction on issuing and distributing binary options to retail clients.
This article was last updated on: October 22, 2026