Basic timeline of binary options
Binary options developed through several different markets: privately negotiated derivatives, listed exchange contracts and online retail products. Australia’s prohibition concerns the issue and distribution of binary options to retail clients. Overseas exchange developments do not, by themselves, change that position.
Evolution of Binary Options & Event Contracts
From options-market foundations to global retail prohibitions and modern exchange contracts
Context: Provides part of the market and analytical foundation for later contracts, rather than a launch date for retail binaries.
Context: Establishes an early regulated US venue for small contracts linked to economic and market outcomes.
Context: Fixed-outcome contracts enter established securities-market infrastructure.
Context: The US exchange model develops alongside the separate online OTC market.
Context: Brings relevant services within a financial licensing framework in Cyprus.
Context: Withdrawal complaints, identity theft and alleged software manipulation receive explicit regulatory attention.
Context: Demonstrates an approach based on product and conduct requirements rather than a general prohibition.
Context: Binary options supplied through electronic platforms become subject to a national consumer distribution ban.
Context: Enforcement initially concentrates on authorisation, promotion and distribution channels.
Context: Marketing controls become another tool alongside licensing and enforcement.
Context: Restrictions address both the location of operators and the customers they target.
Context: Binary options become a prominent test of financial product intervention.
Context: Restrictions move from temporary intervention to continuing national rules.
Context: Australia moves towards intervention in the product itself.
Context: Licensed issuers must stop issuing and distributing the covered products to retail clients.
Context: Australia and US exchange markets continue along different regulatory paths.
Context: Event-contract development increasingly involves disputes about the boundary between derivatives and gambling.
Context: Exchange-based binary structures continue developing despite prohibitions elsewhere.
The detailed sections below explain these milestones and their different legal scopes. A separate Australian timeline follows the international history.
Pricing foundations and early exchange contracts
The options market foundation
Cboe began trading listed options on 26 April 1973. Its account of the creation of the exchange places that development alongside the Black–Scholes–Merton pricing model. Standardised contracts, organised trading and clearing helped options become established financial instruments.
This was the foundation of the modern listed options market, rather than the invention of the binary payoff. A conventional call option’s terminal value generally increases as the underlying price rises above its strike. A cash-or-nothing binary instead pays a specified amount when its condition is satisfied, regardless of how far the market moves beyond the threshold.
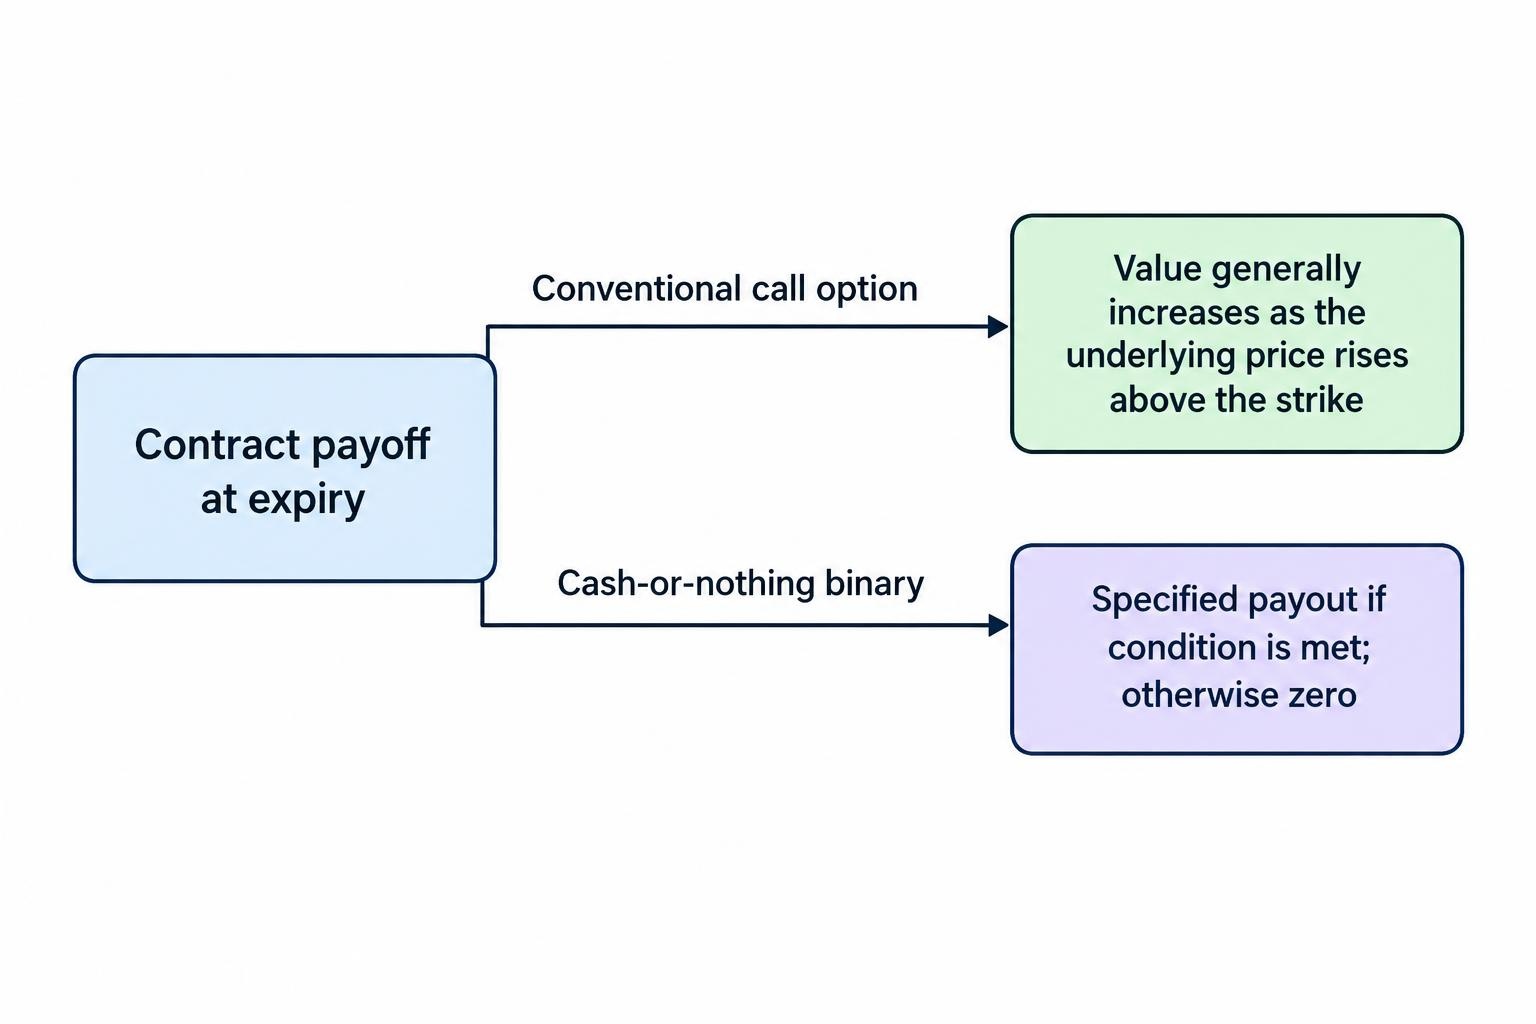
That distinction concerns the payment formula. It does not determine whether the contract is traded privately, listed on an exchange or marketed through a retail website. The same broad payoff idea can appear in different legal and operational arrangements.
“Digital option” is another term used for binary structures. Institutional derivatives can incorporate conditional payments into larger transactions, while a retail platform can present the condition as a standalone yes-or-no trade. Those uses should not be treated as one continuous market with identical participants or safeguards.
HedgeStreet and the US exchange route
The CFTC’s exchange record dates HedgeStreet’s original designation to 18 February 2004. It records the subsequent acquisition by IG Group and the change to the Nadex name in June 2009.
This provides a firmer historical starting point than claims that binary trading began universally in 2008. A regulated US venue already existed before the later securities-exchange listings and the expansion of offshore websites.
An exchange model also changes the meaning of the price. A contract with a fixed settlement payment can trade at a changing purchase price. The buyer’s potential profit is the settlement payment less the amount paid and applicable costs. That differs from a platform quoting a fixed percentage profit against a stake.
The distinction is discussed further in the guide to types of binary options brokers. An exchange, an OTC issuer and a website using another firm’s software perform different functions, even when their interfaces display similar predictions.
The 2007 and 2008 clearing developments
US rule changes were incremental. An OCC filing published in August 2008 records earlier 2007 approvals for clearing credit-default options and credit-default basket options. It also identifies American Stock Exchange fixed-return options and Cboe index binaries among the products OCC cleared.
The SEC approved Cboe’s broad-based index binary option rules on 22 May 2008. Cboe’s June 2008 product circular announced an expected trading start of 1 July for S&P 500 and VIX binaries.
The initial calls were designed to pay US$100 when the relevant settlement value was at or above the strike, and zero when it was below. They used defined index settlement values and exchange rules covering the contracts.
These approvals concerned specified exchange products. They did not authorise every website using the term “binary option”, create a worldwide retail permission or establish that the product was suitable for Australian investors.
Online retail growth and early enforcement
Licensing the product in Cyprus
The online retail market made a conditional financial payoff accessible through a simple trading screen. Selecting a direction and expiry required little operational knowledge, although evaluating the contract still required an understanding of probability, pricing and payment terms.
Cyprus became an important jurisdiction in this phase. In an announcement dated 4 May 2012, CySEC stated that binary options fell within its financial-instrument framework. Providers of relevant investment services had to obtain the necessary Cyprus Investment Firm authorisation, subject to the announcement’s transitional arrangements.
Classification answered which regulatory framework applied. It did not establish that all providers were authorised, or that a licensed firm’s contracts offered favourable expected returns.
The early regulatory response therefore differed from the later bans. Authorities were initially bringing services within financial regulation and checking compliance. The later debate concerned whether the product should be distributed to ordinary retail clients at all.
The 2013 US warning
On 6 June 2013, the SEC and CFTC issued their joint Investor Alert on Binary Options and Fraud. It described complaints involving withheld customer funds, identity theft and software allegedly manipulated to generate losing trades.
That distinction between market loss and misconduct matters. Losing under a disclosed contract is different from a platform changing the result or refusing to return money. The historical record contains both concerns, and one does not explain away the other.
The SEC also announced proceedings against Banc de Binary, alleging unregistered securities offerings and unregistered brokerage activity in the United States. The allegations concerned US legal requirements despite the company being based overseas.
Together, the warning and enforcement action showed that internet distribution did not remove national jurisdiction. A foreign website could solicit customers across borders, but the operator still needed to comply with the rules applicable to those customers.
Criminal cases exposed the sales practices
Later prosecutions documented more than inadequate disclosure. In December 2019, the US Department of Justice announced that former Yukom Communications chief executive Lee Elbaz had been sentenced to 22 years in prison following her conviction for a binary options fraud scheme.
The trial evidence concerned BinaryBook and BigOption. It included false representations about staff identities and qualifications, expected returns and withdrawals. This was a finding about a particular criminal scheme, rather than proof that every binary contract or issuer was fraudulent.
The case helps explain why the industry’s history cannot be reduced to unsuccessful speculation. Some customers were evaluating a risky payoff; others were being deceived about the business, the people contacting them or their access to funds.
It also explains the importance of counterparty and platform risk. Correctly forecasting a price does not resolve whether the entity controlling the account will calculate and pay the contractual amount.
Different national responses before the European ban
Japan introduced product and conduct rules
Japan followed a different route from the later Australian prohibition. The Financial Futures Association of Japan records regulatory amendments on 3 July 2013 and the adoption of its retail OTC binary option business-conduct rules on 18 July.
The framework covered repeatedly tradable currency-related OTC binaries supplied to individuals by member firms. It addressed the way those products were offered, rather than treating every binary structure as prohibited.
Japan’s example matters because the international history was never a single coordinated worldwide ban. Authorities could impose product conditions, restrict advertising, act against unlicensed sellers or prohibit retail distribution. Those approaches sometimes overlapped, but they had different legal effects.
Belgium restricted distribution and France restricted advertising
Belgium’s FSMA regulation took effect on 18 August 2016. It prohibited distribution of certain OTC derivatives, including binary options, to consumers through electronic trading platforms.
The measure also addressed aggressive distribution techniques. Its stated scope excluded derivatives admitted to trading on a regulated market or multilateral trading facility, so describing it as a ban on every possible binary contract would be too broad.
France subsequently used advertising controls under the Sapin II framework. The AMF’s January 2017 announcement explained restrictions on electronic promotion of certain highly speculative products.
An advertising prohibition affects how customers are reached. A distribution prohibition addresses whether the product can be supplied. This distinction becomes important when comparing national measures that are often described simply as “binary options bans”.
Canada’s maturity threshold and Israel’s overseas sales restriction
Canada announced Multilateral Instrument 91-102 in September 2017, with an effective date of 12 December 2017. The measure prohibited advertising, offering, selling or otherwise trading binary options with a maturity shorter than 30 days with individuals.
The Canadian regulators’ announcement separately stated that no registered firms or individuals were permitted to trade binary options in Canada at that time. The maturity threshold should therefore not be presented as permission for any website to sell longer contracts.
Israel addressed the operator side of international distribution. On 23 October 2017, the Knesset approved legislation extending the prohibition to binary options platforms serving customers abroad.
That mattered because restrictions in a customer’s country and restrictions in an operator’s country address different parts of the same transaction. Moving sales activity overseas does not necessarily remove the legal obligations of the business running it.
Europe and the UK move to product intervention
ESMA’s temporary prohibition begins in July 2018
ESMA’s EU-wide retail prohibition began on 2 July 2018. It covered marketing, distribution and sale, initially for three months, under the product-intervention powers in the Markets in Financial Instruments Regulation.
The intervention was broader than a warning about individual fraudulent firms. It addressed investor-protection concerns arising from the product’s characteristics and distribution to retail customers.
ESMA also restricted CFDs, but with a different response: conditions on leverage, close-out arrangements, negative balances and incentives. The parallel measures should not be described as identical bans. This distinction later appeared in Australia’s response to the same two product categories.
National measures replace temporary European action
The temporary prohibition was renewed, with changes to its scope, before ESMA ceased renewing it in July 2019. National authorities had introduced continuing measures, so the expiry did not signal a general reopening of the European retail market.
The UK’s history also included a change of regulator. ESMA’s opinion on the UK measure records that binary options had been supervised as gambling products before 3 January 2018, when the FCA framework took over.
The FCA then announced its permanent prohibition on 29 March 2019, effective from 2 April. Its scope included securitised binaries excluded from ESMA’s measure.
Commercial resources such as BinaryOptions.co.uk remain part of the online publishing market, but their existence does not establish that a promoted service is permitted. For the historical UK change, the FCA’s decision establishes the date and scope.
Australian timeline towards the binary options ban
Australia’s prohibition followed several years of enforcement and review. The timeline below contains Australian events only, including the policy developments that gave ASIC the power to intervene.
| Date | Australian development | Role in the process |
|---|---|---|
| 2014 | The Financial System Inquiry recommends stronger product-intervention powers. | Establishes a policy basis for action beyond disclosure and enforcement against individual misconduct. |
| July 2016 | ASIC reports contacting more than 40 unlicensed OTC derivatives providers and related businesses. | Targets unauthorised services reaching Australian customers. |
| March–August 2017 | ASIC reviews binary-related mobile apps and publishes its findings. | Identifies distribution through app stores, misleading promotion and missing risk warnings. |
| June 2018 | ASIC publishes Report 579 following its 2017 sector review. | Reports poor pricing transparency and high proportions of unprofitable binary options clients. |
| April 2019 | New legislation gives ASIC product-intervention powers. | Enables intervention where financial products cause or are likely to cause serious retail harm. |
| April 2019 | ASIC warns licensees about services supplied unlawfully into overseas jurisdictions. | Challenges the use of an Australian licence to evade foreign restrictions. |
| 22 August 2019 | Consultation Paper 322 proposes a retail binary options ban; Report 626 accompanies it. | Begins the public consultation on a market-wide order. |
| 1 April 2021 | ASIC announces its binary options product-intervention order. | Sets out the prohibition and reasons for acting. |
| 3 May 2021 | The prohibition takes effect. | Stops the issue and distribution of covered binary options to retail clients. |
| 26 May 2022 | ASIC consults on extending the order through Consultation Paper 362. | Reviews the effect of the initial intervention. |
| September 2022 | ASIC extends the order, with ministerial approval. | Continues the prohibition to its scheduled sunset on 1 October 2031. |
How Australia moved from enforcement to prohibition
The initial focus was on authorisation
ASIC’s July 2016 enforcement announcement described concerns raised with more than 40 unlicensed providers. Most were binary option issuers, although the group also included review sites, signal services, affiliates and other derivatives businesses.
Twenty-one agreed to take remedial steps. These included stopping Australian marketing, blocking registrations and closing existing Australian accounts where appropriate.
The emphasis at this stage was whether businesses were authorised to provide the services they offered. That is different from the later conclusion that retail distribution should be prohibited even within the licensed sector.
It also shows that the distribution chain extended beyond the issuer’s trading website. Advertising, referrals and supposed educational services could all contribute to attracting customers. The relevant business was not always the brand most visible to the reader.
Mobile apps widened the distribution problem
ASIC’s March 2017 review identified more than 330 binary-related apps offered to Australians by entities or individuals that appeared unlicensed. Its published findings in August reported that 80% of the apps had no risk warning.
The regulator also identified apparently misleading profitability claims and unclear referral arrangements. Apple and Google removed the relevant apps identified by ASIC.
This episode is an Australian milestone in the history of financial distribution. A product could reach consumers through a familiar technology platform without the underlying financial service having the required authorisation. App-store availability was therefore a separate question from financial-market compliance.
Reviews supplied evidence about customer outcomes
ASIC’s Report 579, published in June 2018, identified nine binary option issuers. It reported that up to 80% of clients were unprofitable and highlighted weaknesses in transparency around underlying prices, strikes and payouts.
These findings shifted attention from whether customers received information to whether the market’s actual outcomes justified further intervention. They also showed that concerns were not confined to obviously unlicensed websites.
A loss-rate statistic needs careful interpretation. The proportion of accounts or clients losing over a review period is not the probability that every individual contract will lose. It also does not mean that every unsuccessful customer experienced fraud. The data describe outcomes within the reviewed market.
The 2019 reforms changed ASIC’s available powers
In April 2019, ASIC welcomed legislation introducing a product-intervention power. The regulator linked the reforms to the 2014 Financial System Inquiry and described a shift away from relying predominantly on disclosure.
That was a practical change in regulatory approach. A disclosure regime explains risks and imposes obligations on providers. Product intervention can address the availability or distribution of a product where the statutory harm threshold is met.
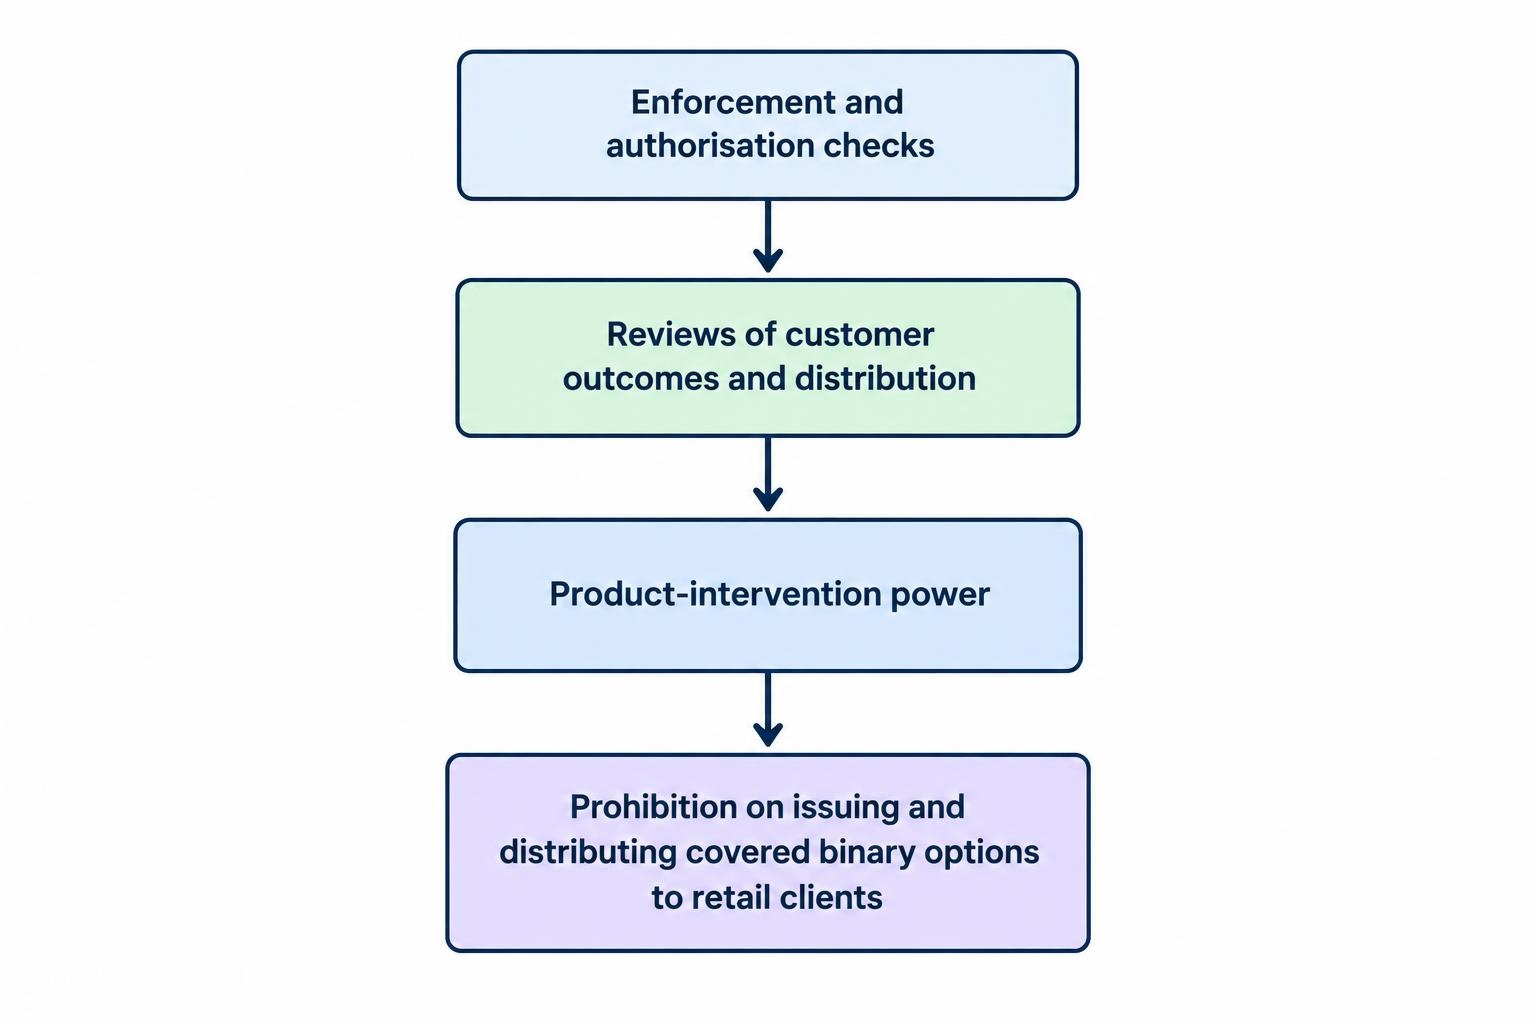
The difference matters for binary options because improved warnings do not alter the payment formula. A customer can understand the possibility of losing a stake and still be exposed to a product that produces persistent aggregate losses.
The site’s explanation of ASIC regulations on binary options trading provides related Australian regulatory context. The historical change was from controlling how providers operated to restricting the retail supply of the covered product.
Overseas restrictions affected Australia’s market
ASIC’s April 2019 warning to AFS licensees addressed the possibility that Australian firms were supplying derivatives unlawfully into foreign jurisdictions.
The regulator was concerned about marketing that encouraged overseas clients to use Australian accounts to avoid restrictions in their own countries. An Australian licence was not a substitute for complying with those countries’ laws.
This also affects how the historical financial figures should be read. ASIC’s August 2019 consultation announcement reported A$490 million of binary options gross trading revenue received by licensed issuers during 2018. It described the wider binary-options and CFD customer base as predominantly offshore.
The figure should not be relabelled as a measured loss suffered exclusively by Australian residents. ASIC’s later 2021 announcement described approximately A$490 million in retail net losses for 2018, while separately estimating Australian retail clients’ 2019 losses at more than A$6.7 million. These statements have different populations, periods and accounting descriptions.
Consultation led to the May 2021 prohibition
Consultation Paper 322, released on 22 August 2019, proposed prohibiting retail binary options and imposing conditions on CFDs. The consultation documents formed the public process leading to the orders.
ASIC announced the binary options prohibition on 1 April 2021, with commencement on 3 May. Its reasons included the all-or-nothing payment structure, short durations and negative expected returns.
The economic concern can be illustrated without assuming misconduct. Suppose a hypothetical contract produces an A$80 profit when successful but loses A$100 when unsuccessful. With a genuine 50% chance of each outcome, its expected result is a loss of A$10 per contract before separate costs.
A 50% winning rate therefore would not break even under those assumptions. The required rate is approximately 55.56%. Short durations can allow this exposure to be repeated frequently; they do not improve the arithmetic.
The guide to why binary options traders lose money discusses this distinction between predicting direction and earning a positive return after the payment structure is considered.
The 2022 review supported continuation
On 26 May 2022, ASIC consulted on extending the prohibition. It reported that retail clients had made neither profits nor losses from binary trading with licensed issuers after the order took effect.
That finding has a defined scope. It measures the removal of retail trading from licensed issuers; it does not prove that Australians stopped encountering offshore offers or scams.
ASIC’s September 2022 extension announcement drew on data from five licensed issuers. During the preceding 13-month pre-ban period, 74–77% of active retail clients had lost money, with aggregate net losses of A$14 million.
The extension continued the order until 1 October 2031. That scheduled end date does not guarantee that retail distribution will resume then; subsequent legislation or regulatory action can change the position.
Retail classification remains central
The intervention addressed retail clients. It did not convert wholesale binary trading into a low-risk activity or establish that experience alone makes a customer eligible for different treatment.
Moneysmart warns against accepting wholesale classification simply to gain access to binary options. Wholesale customers do not receive the same consumer protections.
The historical sequence therefore changes how old broker guides should be read. A description of a licensed Australian retail offering before May 2021 is not evidence that the same offering remains available. The guide to assessing a binary options broker in Australia explains the relevance of the entity, authorisation and proposed client category.
Event contracts and the position in the 2020s
Exchange-based products continued developing
Australia’s prohibition did not end the use of fixed-outcome contracts internationally. On 19 September 2022, CME announced the launch of event contracts linked to benchmark futures markets.
These were daily options on futures, sized at US$20 per contract. Their conditions concerned end-of-session market outcomes. They should not be described generally as paying whenever a price touches a level during the day; a touch condition and an expiry condition are different contractual events.
Nadex’s corporate history also continued. The CFTC’s exchange record identifies its acquisition by Foris DAX Markets in March 2022 and subsequent operation under the Crypto.com name. Historical references to Nadex should consequently distinguish the exchange’s regulatory lineage from a particular brand or product menu at a later date.
Prediction markets brought further legal disputes
Binary-style payments also appear in contracts tied to political or other events. Their legal treatment depends on the contract, venue and jurisdiction, rather than the yes-or-no presentation alone.
In its 2 October 2024 Kalshi decision, the US Court of Appeals for the District of Columbia Circuit refused the CFTC’s request for a stay pending appeal concerning congressional-control contracts. The decision turned on the required showing of irreparable harm.
That procedural ruling allowed trading to proceed while the appeal continued. It was not a worldwide authorisation of election betting or a decision that every event contract falls outside gambling restrictions.
The policy debate includes arguments about whether such contracts serve the hedging and price-discovery purposes of derivatives law. Ilya Beylin’s article, Event Contracts Are a Step Too Far for Derivatives Regulation, advances that argument. It is an academic position, rather than a ruling that CME’s entire event-contract offering is unlawful.
The October 2026 US approval
On 13 October 2026, the SEC approved a rule change allowing specified binary options on company key performance indicators. The SEC chair’s accompanying statement described standardised, cash-settled securities options traded under exchange rules.
The statement expressly confined the approval to those particular contracts and their structure. Similar contracts built differently could raise different jurisdictional questions.
This is a continuation of the US exchange route, rather than a reversal of Australia’s policy. A company metric can replace a market price as the event being predicted while the questions of authorisation, distribution, settlement and customer protection remain.
What the history means for Australian readers
As at 22 October 2026, Australia’s retail prohibition remains in force, with its scheduled sunset on 1 October 2031. The governing Australian framework must be assessed separately from a US listing, a European licence or a platform’s chosen terminology.
The history shows why those distinctions matter. The same broad fixed-payment idea has been used in regulated exchange contracts, dealer products and fraudulent sales schemes. Regulators responded to different problems with different tools.
For Australia, the decisive development was the evidence that licensing, warnings and enforcement had not adequately addressed retail harm. The resulting order restricted distribution of the product itself. Changing the label to “digital”, “turbo” or “event” does not, by itself, settle its legal classification or make it suitable for a retail investor.
This article was last updated on: October 27, 2026