A binary options trading robot is software that selects or submits trades according to programmed rules. Depending on its design, it may choose the reference asset, direction, stake, contract duration and minimum acceptable payout. Some systems only produce suggestions; others can commit money without approval for each transaction.
Automation changes how decisions are made and executed. It does not change the underlying contract or establish that the decisions have a profitable basis. A robot can apply an effective rule consistently, but it can also repeat a weak rule more quickly than a person.
The term “robot” covers several different arrangements. A downloadable program, a broker-hosted strategy builder, a remote subscription service and a tool that copies another account can all be advertised under the same label. Their account access, operating costs and failure risks differ.
For an Australian reader, product access must be considered before software features. ASIC’s prohibition on issuing and distributing binary options to retail clients took effect on 3 May 2021 and has been extended until 1 October 2031. Using a robot does not create an exception.
Australian authorisation and automated services
A software seller, signal provider and binary options issuer may be separate businesses. Each may have a different role in collecting money, generating recommendations or executing transactions. A familiar platform name does not identify all of those relationships.
An Australian financial services licence should not be interpreted as permission to offer every financial product to every client. The retail binary options prohibition remains relevant even where a business holds other authorisations. The explanation of ASIC’s binary options regulations covers that distinction.
Automation is not a general exemption from financial services regulation either. ASIC’s guidance on digital financial product advice addresses advice delivered through algorithms and technology. Whether a particular software service involves regulated advice or another financial service depends on what it actually does.
Nor should an invitation to become a wholesale client be treated as an ordinary software upgrade. Moneysmart’s binary options warning explains that wholesale clients do not have the same consumer protections and cautions against changing classification merely to obtain access.
These restrictions do not mean every form of automated trading is prohibited. They mean that automation, product availability and provider authorisation are separate questions. A system used in another market or jurisdiction does not establish that a binary options robot can lawfully be offered to Australian retail clients.
Signals, execution and types of automation
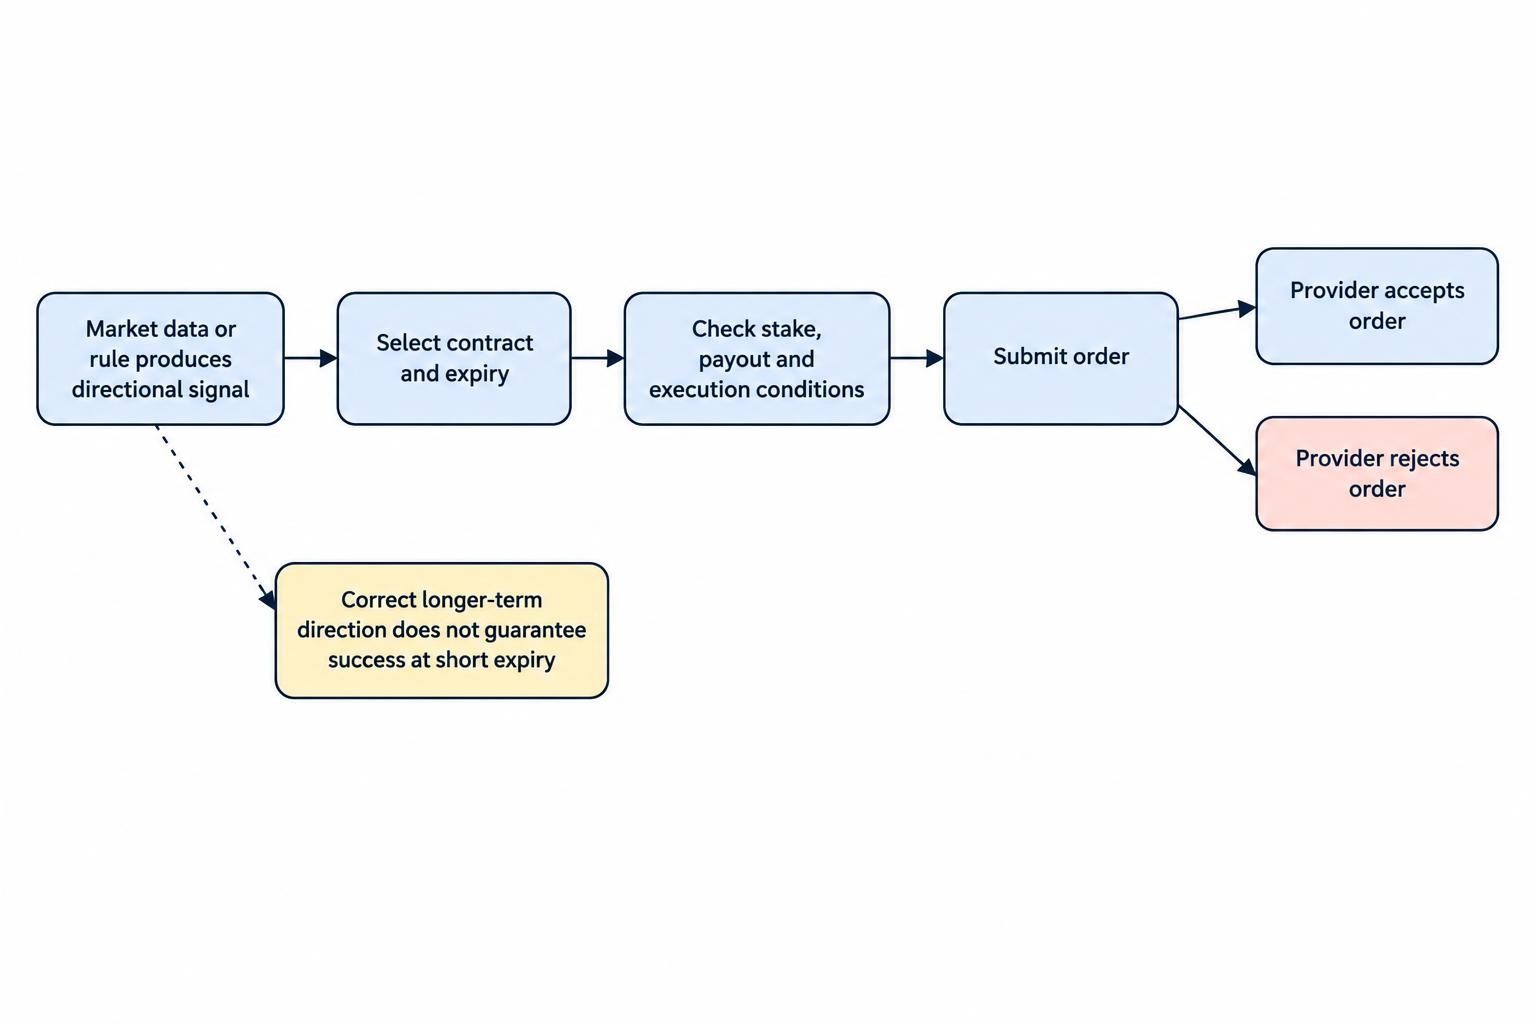
A signal is an instruction or condition suggesting a possible trade. It might be generated by a moving-average rule, a comparison of prices, an economic release or a statistical model. The robot’s execution component then decides whether and how to convert that signal into an order.
A complete system needs more than an indication that a price may rise. It also needs to establish the contract being considered, the relevant timing, the stake and the terms available when the order is accepted.
For example, a signal that an exchange rate may rise over an hour does not automatically support a contract expiring in thirty seconds. The direction could eventually prove correct while the shorter contract loses.
| Automation arrangement | How decisions reach the account | Main issue to examine |
|---|---|---|
| Signal service with manual approval | Software proposes a trade; the user decides whether to submit it | The subscriber’s timing and terms may differ from the published signal |
| Locally installed robot | Software on the user’s device submits orders through a supported connection | Device uptime, credentials and execution reliability |
| Hosted robot service | A remote system operates using granted account permissions | Control over access, ongoing operation and service changes |
| Platform strategy builder | Rules assembled within a trading platform generate orders | Available controls, platform dependence and visibility into execution |
| Copy-trading service | Transactions or instructions from another account are replicated | Different balances, stakes, execution times and risk settings |
These are descriptions of software arrangements, not endorsements of providers or routes around Australian restrictions.
A published strategy needs operational detail
Technical analysis uses market data to calculate indicators or identify patterns. A statement that a robot uses technical analysis reveals little about its rules.
A moving-average strategy, for example, needs a data source, chart interval, averaging method and exact entry condition. It also needs to specify whether it acts during a forming price bar or waits for that bar to close. Those choices can produce different signals.
Execution filters are equally relevant. A system may reject a signal if the offered payout is too low, the quote is stale or the account already has sufficient exposure. Without those filters, a theoretically attractive signal can become an unattractive accepted trade.
The provider does not necessarily need to disclose its entire source code for users to understand the service. It should still be possible to identify the markets, operating conditions, stake policy and circumstances in which trading stops. Commercial secrecy does not explain why basic risk behaviour must be hidden.
The broader guide to automatic binary options trading explains how signal generation and order handling fit together.
AI changes the model, not the need for evidence
“AI-powered” can describe many different processes, from statistical classification to a language model interpreting news. The label does not establish which process is used or whether it improves net results.
A model may identify historical relationships without those relationships persisting. It may also perform differently when market conditions, data quality or the provider’s implementation change.
The US Commodity Futures Trading Commission has warned about AI trading bots promoted with unrealistic or guaranteed returns. Its warning concerns misleading promotion, including claims that automated systems can produce exceptionally high returns or perfect winning records.
For a binary options robot, the relevant evidence remains the same: what it does, what exposure it creates and how complete results compare with its costs. An AI label cannot supply missing transaction records.
Payouts, win rates and trading costs
Why being right more often can still lose money
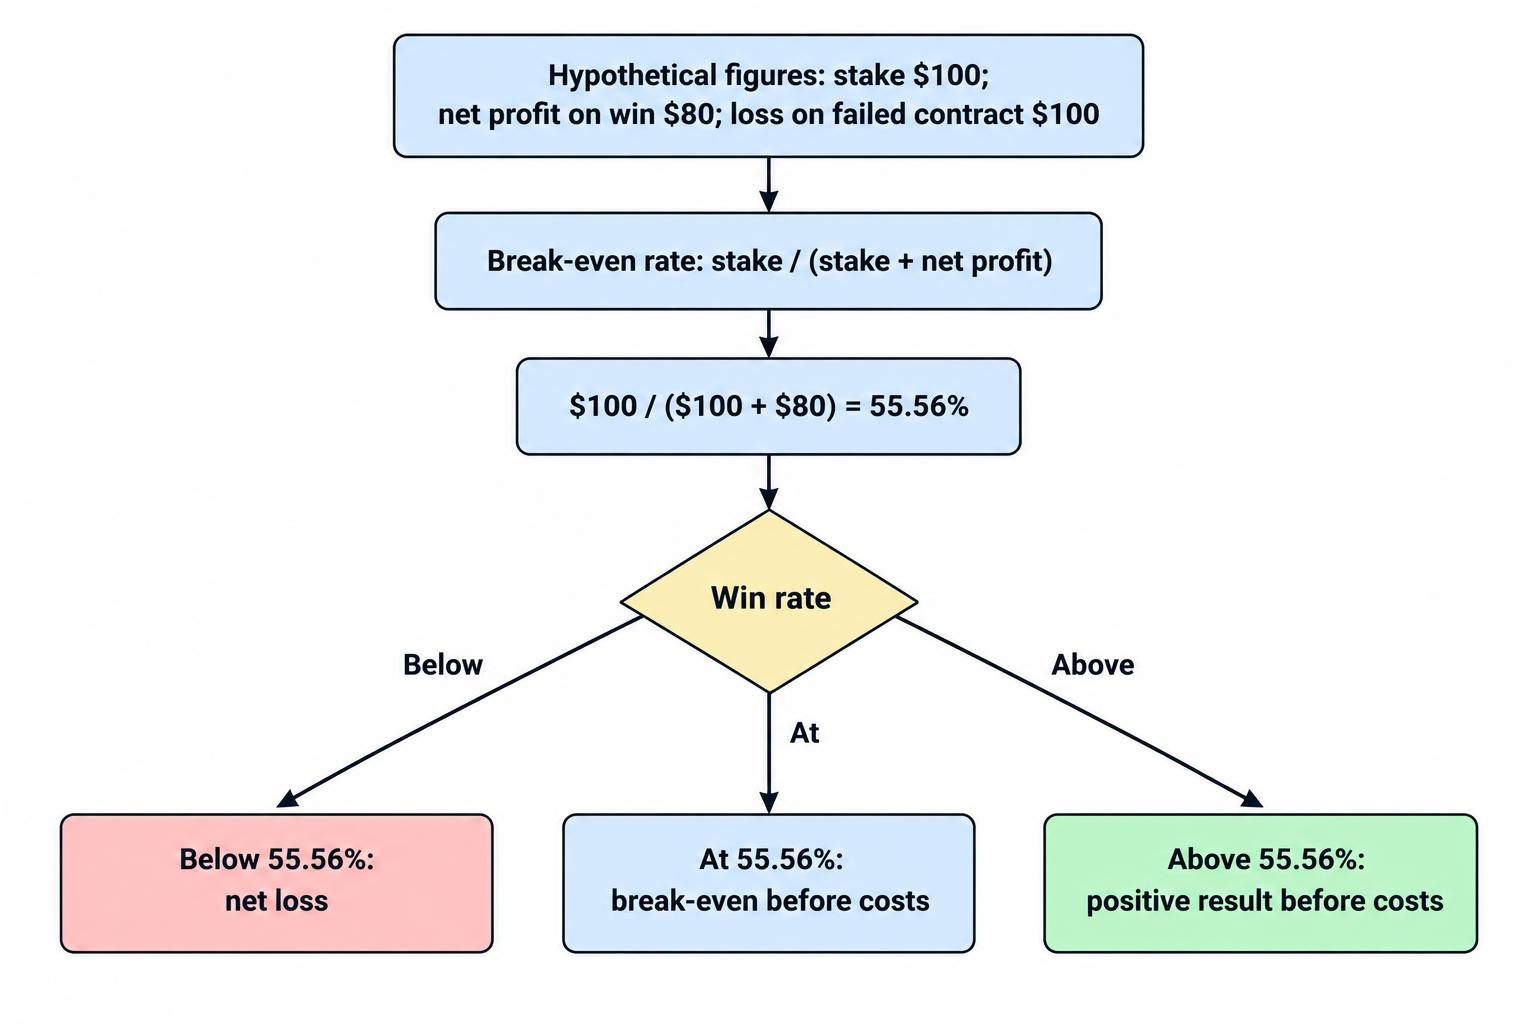
For a common fixed-return binary option, a successful contract earns a specified profit and an unsuccessful contract loses the stake. If the profit on success is smaller than the loss on failure, the system must win more than half its trades to break even.
Suppose a hypothetical contract risks $100 and earns an $80 net profit if successful. Five wins produce $400, while five losses cost $500. The ten contracts therefore lose $100 before subscriptions or other charges.
The return percentage must also be defined correctly. An 80% net profit on a $100 stake means total proceeds of $180 when successful, including the returned stake. Reporting the $180 as profit would overstate the result.
The following figures assume equal stakes, a constant payout, complete loss of the stake on failure, and no ties, refunds or additional costs. They are mathematical examples, not current broker offers.
| Net profit on a successful $100 contract | Loss on an unsuccessful contract | Success rate needed to break even |
|---|---|---|
| $70 | $100 | 58.82% |
| $80 | $100 | 55.56% |
| $90 | $100 | 52.63% |
The break-even rate is the stake divided by the stake plus the potential net profit. The explanation of binary options payouts provides further context.
Accuracy claims need the corresponding stakes
A reported winning percentage is incomplete without the amounts won and lost. A system can record many small wins followed by one much larger loss.
Variable stakes make this particularly important. If a robot increases its stake after losing, its financial result cannot be reconstructed from the count of wins and losses alone. The sequence and amount of every contract matter.
Payouts may also differ across assets and times. A historical success rate measured when successful contracts earned 90% of the stake cannot be assessed using an assumed 70% payout without recalculating the result.
A credible record therefore needs the actual accepted payout for each trade. The provider’s maximum advertised payout is not an adequate replacement.
Subscriptions can remove a small trading gain
Consider a hypothetical month with 100 contracts, each using a $20 stake and earning 80% net profit on success. Sixty wins earn $960, while forty losses cost $800. The trading gain is $160.
If the robot and signal subscription together cost $100 for that month, the remaining gain is $60 before any other charges. With only fifty-five wins, the same trading assumptions produce a $20 loss, which becomes a $120 loss after the subscription.
These examples use a constant stake and payout to make the arithmetic visible. Real records need to include changing terms, payment charges and any currency conversion costs.
Increasing trade frequency does not solve a negative expectation. It increases the number of times the same unfavourable economics are applied. More activity is useful only if the additional trades have sufficient expected value after costs; the software’s capacity to place them is a separate matter.
Backtests, demonstration accounts and performance evidence
What a backtest actually measures
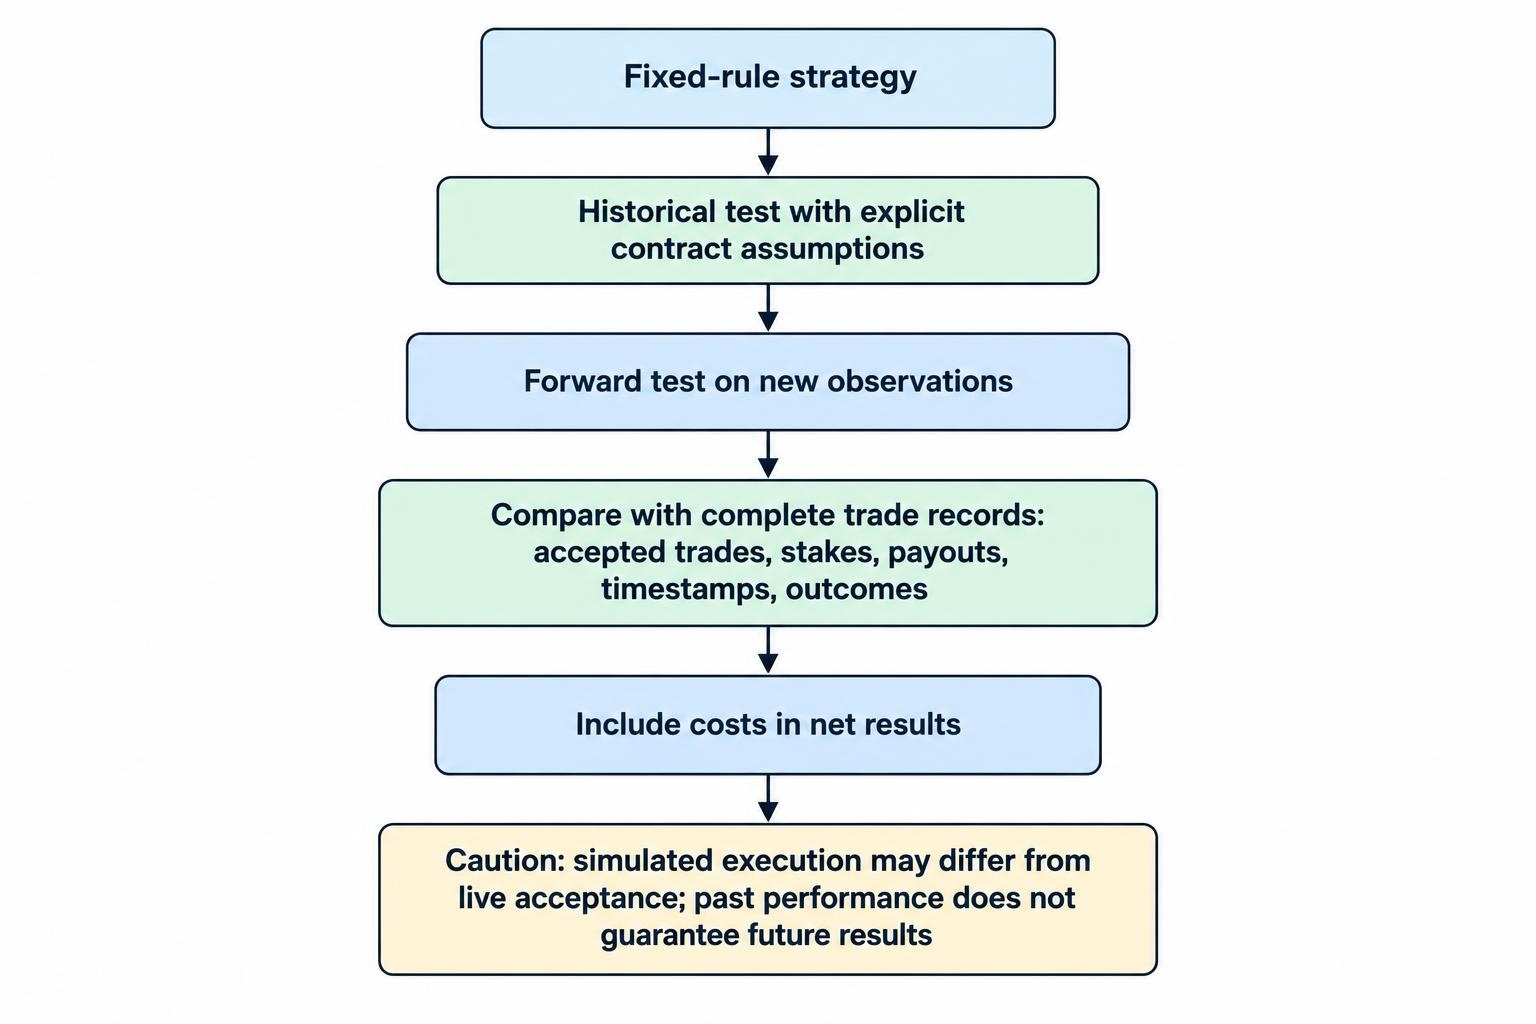
A backtest applies a strategy to historical data and calculates what would have happened under the test’s assumptions. It is a simulation, even when the source prices are genuine.
For binary options, the assumptions extend beyond market direction. The test needs a reference price, entry timing, expiry, settlement rule and payout. A chart-based test that guesses these terms can produce an accurate calculation for a contract that was never available.
Data frequency matters. Minute-by-minute prices cannot reliably reconstruct every event within a one-minute contract. The difference becomes more pronounced for products whose outcome depends on whether a level was touched at any point.
The simulation must also avoid using information unavailable at the supposed decision time. Selecting an entry using the final high or low of a price bar, before that bar would have finished, introduces knowledge of the future into the test.
The guide to backtesting binary options strategies explains why data and contract assumptions need to match.
Overfitting and repeated experimentation
Overfitting occurs when rules are adjusted to fit historical observations too closely, including patterns that arose by chance. A strategy may then look convincing on the development data but perform poorly on later observations.
Testing hundreds of combinations and publishing only the winner conceals how much searching took place. The winning result cannot be assessed as though it came from a single rule selected in advance.
This is a recognised problem in investment research. Bailey, Borwein, López de Prado and Zhu examine it in The Probability of Backtest Overfitting. Their work also cautions against treating a simple hold-out test as a complete answer to repeated strategy selection.
Keeping development and evaluation periods separate is useful, but it does not remove every source of bias. If the supposedly untouched period is repeatedly examined and used to revise the strategy, it has become part of development.
A provider should be able to explain when the rules were fixed, which observations were used to develop them and whether unsuccessful versions were excluded from the advertised history.
Demonstration results and forward testing
A demonstration account can show whether software submits the intended instructions and respects its configured limits. It can also expose timing errors, incorrect stake calculations and missing records.
It cannot establish that the same orders would receive the same terms in a live account. Simulated acceptance, payouts and execution may differ. Demonstration balances also say nothing about withdrawals.
Forward testing applies a fixed strategy to new observations as they arrive. This avoids some hindsight problems, although a simulated forward test still has the limitations of its execution model. The distinction is explained in the guide to forward testing.
For Australian retail readers, testing software with simulated data should not be presented as a progression towards a prohibited binary options offering. Researching automation and funding a real-money product are separate decisions.
Complete records are more useful than screenshots
A performance record should identify every accepted contract, its stake, payout, timestamps and outcome. Rejected or missed signals also matter when comparing the strategy’s theoretical record with an executable version.
Deposits and withdrawals need to be separated from profits and losses. An account balance that rises after additional funding is not evidence of a successful strategy.
The period covered matters as much as the headline return. A few profitable days may reflect one market condition. A large number of overlapping trades may also provide less independent evidence than the trade count suggests.
Drawdown, meaning the decline from a previous capital peak, shows how much account value was lost during the period. It should be considered alongside net returns and the largest stakes. An attractive final balance can conceal an exposure level that the user would not have accepted.
A verified record is stronger evidence than an anonymous screenshot, but it remains a record of past activity. It cannot guarantee future performance or establish that future withdrawals will be honoured.
Stake controls, losing streaks and martingale
A fixed-loss contract can still exhaust an account
In a standard fully paid binary-option purchase, the contractual trading loss is generally limited to the amount paid and applicable fees. Ordinary margin leverage should not be assumed simply because the product is a derivative or the order is automated.
Borrowing money to fund an account introduces a separate debt. A service that also trades CFDs or other margined products introduces a different loss structure. Those arrangements must be assessed on their own terms.
The main account risk from a conventional binary options robot is repeated commitment of funds. It can lose one stake, submit another contract and continue until the available balance is exhausted.
Simultaneous positions create another problem. Ten open contracts with $20 at risk each represent $200 of committed stakes, even if the robot describes its individual trade risk as only $20. Contract-by-contract limits need an account-level counterpart.
Loss limits must include open exposure
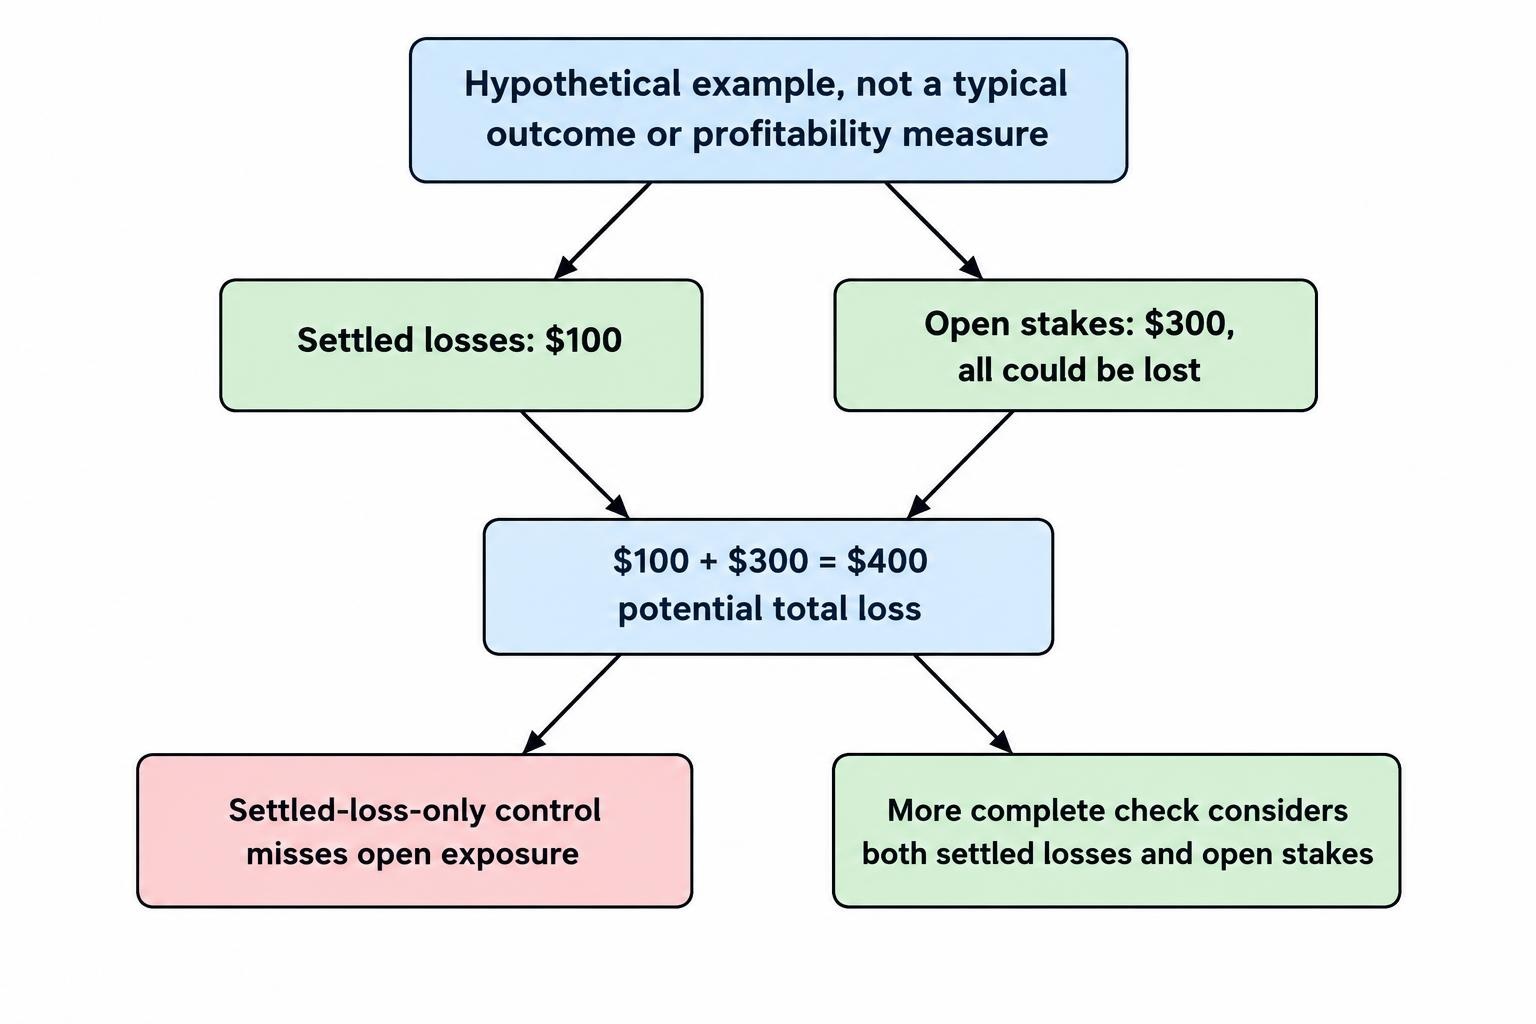
A daily realised-loss threshold does not necessarily cap the day’s eventual loss. Suppose a hypothetical robot stops submitting new orders after recording $100 of settled losses, but still has $300 in open stakes. If all those positions lose, the total reaches $400.
A control that considers both realised losses and money still at risk provides a more complete view. It should also account for orders awaiting confirmation, rather than assuming that an unanswered request was rejected.
The reset rule matters. A threshold that resets at midnight in the provider’s time zone may permit a new block of exposure minutes after the previous limit was reached. The relevant time zone and reset behaviour need to be explicit.
Limits also need to work when several strategies share an account. Each robot may remain within its own allowance while their combined exposure exceeds what the account holder intended.
These are control-design questions, not evidence that a strategy is profitable. The guide to stake sizing separates exposure decisions from signal quality.
Martingale does not guarantee recovery
A martingale approach increases stakes after losses, commonly by doubling them. Its appeal rests on the assumption that a later win will recover the earlier losses.
For binary options with a net winning payout below 100% of stake, simple doubling can fail to recover the sequence even when a win eventually occurs.
Assume an 80% net winning payout and successive stakes of $10, $20, $40, $80 and $160. If the first four contracts lose, the accumulated loss is $150. A win on the fifth earns $128, leaving the sequence $22 down before fees.
If all five lose, the loss is $310. The next doubled stake would be $320, requiring total funding of $630 to reach that point. Continuing the sequence requires rapidly increasing capital and may encounter stake limits before a recovery trade is possible.
A progression designed specifically to recover losses at an 80% payout would require different increases, but it would not eliminate losing streaks or finite capital. The discussion of martingale in binary options trading explains that exposure.
A robot that labels the same behaviour “recovery mode” or “adaptive money management” still needs to disclose how stakes change. Renaming the rule does not change its arithmetic.
Correlated signals can concentrate losses
Multiple signals may originate from the same market event. Trades on related currency pairs or several contracts with nearby expiries can fail together.
Different asset names do not establish independent risk. The practical question is how the positions respond to the same news, volatility change or data problem.
A pause after losses may slow further depletion, but it does not repair a weak strategy. Its purpose is to constrain operation while the cause of the losses is examined.
Account access, execution failures and security
Trading permission is access to capital
An automated service needs a way to communicate with the account. Where supported, this may use an application programming interface, or API: a defined connection through which software can request information or submit instructions.
Permissions determine what that connection can do. Read-only access differs from permission to trade, and trading permission differs from permission to withdraw. A robot should not require broader authority merely because it is described as convenient.
Restricting withdrawals reduces one form of exposure, but a trading-only connection can still create substantial losses through authorised transactions. Permission controls and trading risk controls address different problems.
The account holder also needs an independent way to revoke the service’s access. Deleting a local application may not stop software operating on a remote server.
Failed acknowledgements and duplicate orders
An execution failure can occur between order submission and the return of a confirmation. If the robot retries without checking whether the first order was accepted, it may create duplicate exposure.
A well-controlled system needs to reconcile its records with the provider’s accepted orders. Treating every timeout as a failed trade is inadequate.
Stale prices create a similar problem. The signal may be calculated correctly from the data received, yet the data may no longer represent the conditions at acceptance. Short contract durations leave less time for such delays to be absorbed.
The guide to execution and latency explains why a fast calculation does not guarantee a timely transaction.
Stopping the software and changing its rules
A stop control should have a defined effect. Preventing new orders is different from cancelling pending instructions or closing accepted contracts. Some binary options cannot be exited early, while others offer an exit only under specified conditions.
Software changes also require scrutiny. A provider may alter signal logic, default stakes or supported instruments. The performance record of an earlier version does not automatically describe the revised system.
The operating record should identify the version and settings used. Otherwise, a user may be comparing current results with a historical strategy that is no longer running.
Account credentials and authentication methods need protection throughout this process. The Australian Government’s personal cyber security handbook recommends current software, strong unique passwords and multi-factor authentication or passkeys where available. These measures support account security; they cannot prevent losses from trades the user has authorised the robot to make.
Fees, commercial incentives and fraud claims
The cost of a free robot
“Free” may mean no separate software subscription. The provider may instead receive payment when a user opens an account, deposits funds or generates trading activity. The actual arrangement needs disclosure.
A referral relationship can influence which broker the service supports. The selected broker may be necessary for the seller’s remuneration rather than because its terms suit the user.
Paid systems can add a different set of costs. A licence fee, monthly signal charge, data subscription and hosting expense may all apply to the same setup. The guide to signal and software costs explains why these should be assessed together.
Cancellation terms also matter. Stopping a robot, revoking account access and cancelling a recurring subscription are separate actions. Completing one does not necessarily complete the others.
Profit guarantees and fabricated accounts
A promise of fixed daily income is not substantiated by a moving account balance or a video of profitable trades. Both the transactions and the money behind the display need to be real.
The US Securities and Exchange Commission’s binary options fraud warning describes complaints involving withheld funds, identity theft and software manipulation. These are risks associated with fraudulent operators, not proof that every losing strategy is fraudulent.
A genuine program can lose money because its rules are ineffective. A fraudulent service may never perform the advertised trading at all. Distinguishing those situations requires transaction evidence and independent verification of the provider.
A refund promise does not necessarily cover market losses. It may apply only to a subscription and may contain conditions. Similarly, a successful small withdrawal is evidence of that payment alone, rather than a guarantee about the remaining account balance.
What automation can reasonably deliver
Software can apply specified rules consistently, maintain records and reduce the need for manual order entry. It can also help researchers compare rule-based decisions using simulated data.
Those functions have value only within a clearly defined process. A robot needs understandable exposure limits, reliable execution, accessible records and a strategy whose results remain credible after costs.
Removing manual decisions can reduce some impulsive actions, but it also allows errors to repeat without hesitation. The user remains responsible for deciding which rules and permissions the system receives.
For Australian retail clients, the product prohibition remains the first constraint. Beyond that legal position, the central financial test is unchanged: automation needs evidence of a durable advantage after costs. Speed, an AI label and the ability to operate unattended do not provide that evidence.
This article was last updated on: October 22, 2026