Australian readers comparing binary options brokers need to establish whether the proposed service can lawfully be offered to them before considering its trading features. A recognisable brand, a detailed website or an Australian contact number does not answer that question.
Binary options are contracts whose payment depends on a specified event, such as a market price finishing above a stated level at expiry. In a common arrangement, a correct prediction produces a fixed profit and an incorrect prediction loses the stake. The trader does not acquire the underlying shares, currency or commodity.
Assessing a provider therefore involves several separate questions. These concern its legal identity, authority to provide the service, contractual obligations, pricing methods and ability to return money. Platform convenience becomes relevant only after those matters have been established. The following discussion explains how to evaluate broker claims and documents, including offers encountered through overseas websites.
Australia’s retail binary options restriction
What ASIC’s ban covers
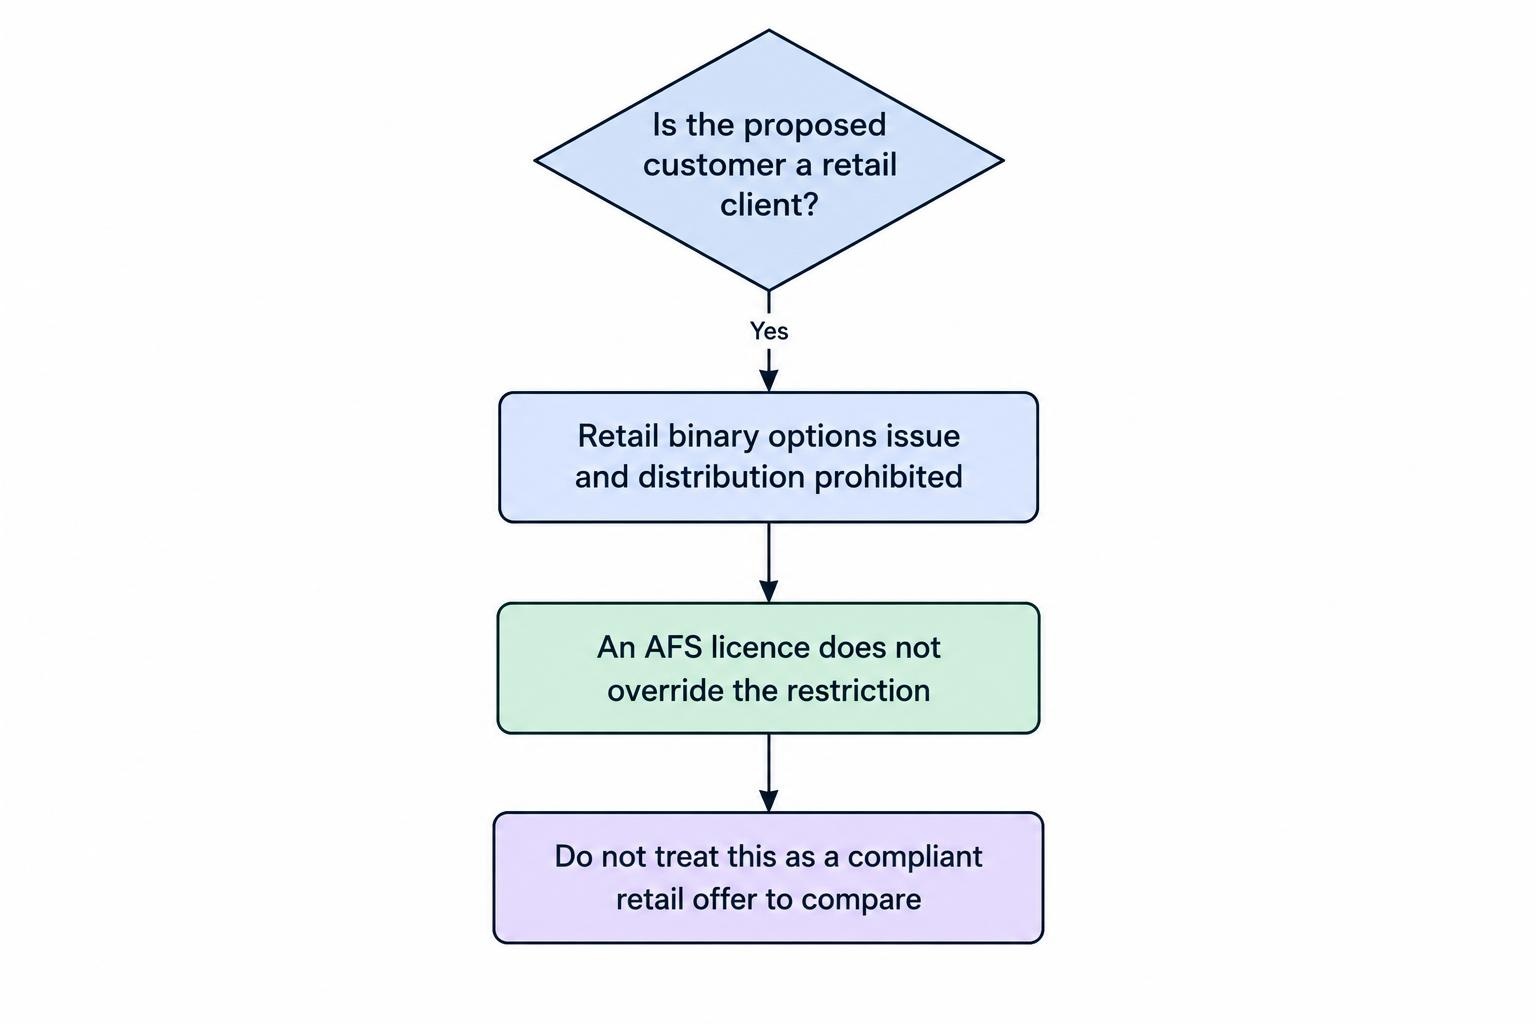
ASIC’s product intervention order prohibits the issue and distribution of binary options to retail clients. It took effect on 3 May 2021 and has been extended until 1 October 2031. An Australian financial services licence does not override this restriction.
This changes the premise of a broker comparison for an Australian retail client. There is no compliant retail binary options offering to select merely by finding an ASIC licensee with favourable payouts. An accessible website or a registration form that accepts an Australian address is not evidence that the offer is lawful.
ASIC’s pre-ban analysis used information from five licensed issuers. During the 13 months before the prohibition, 74–77% of active retail clients lost money and retail accounts recorded aggregate net losses of $14 million. These findings concern that historical sample and period, rather than every account at every provider.
Why the distinction matters when reading broker reviews
A review can describe a platform accurately while drawing an unsupported conclusion about its availability to Australians. Screenshots may show functioning charts and payment methods without establishing which company would enter the contract or whether the proposed customer can legally be served.
Publication dates also matter. A review written before May 2021 may describe a domestic retail offering that no longer exists. Changing its heading to the current year does not demonstrate that its regulatory analysis has been updated.
A useful assessment should identify the intended customer category and the legal entity behind the offer. If those details are missing, comparisons of minimum deposits, indicators and promotional payouts are premature. The same applies to reviews that refer broadly to an international group while leaving the actual contracting subsidiary unnamed.
Establish the broker’s identity and authority
Match the company to the account agreement
The trading brand, software provider, payment processor and contract issuer may be different businesses. The issuer is particularly significant because it owes the contractual payment. Its identity should be apparent from the account agreement, rather than inferred from the logo above the registration form.
Read the company name, registered address and governing-law provisions together. A footer naming an Australian company does not establish that an account agreement with an overseas subsidiary carries the same protections. If documents identify different entities, the relationship needs an explanation.
A payment recipient with a different name also requires clarification. It might be a disclosed processor, but that cannot be assumed. Written documents should explain who receives the money, on whose behalf it is received and which entity remains responsible for the account balance.
Understand what a licence establishes
Moneysmart’s guidance on checking an investment provider explains that company registration is different from financial services authorisation. It also warns that scammers impersonate licensed businesses and misuse genuine licence details.
A licence check therefore needs to match the named business and relevant authorisations to the proposed service. Verification should use independently obtained contact information. Finding a genuine licence number somewhere on a website is insufficient.
An AFS licence is not ASIC’s endorsement of the company, product or advice, and it does not guarantee that an investment is safe. In the binary options context, checking the licence must also be considered alongside the retail prohibition.
Treat wholesale classification as a material change
Retail and wholesale are legal client categories, not measures of confidence or familiarity with trading software. A platform label such as “professional” does not, by itself, establish a person’s legal classification.
Moneysmart’s binary options warning specifically cautions against agreeing to wholesale treatment simply to obtain access. Wholesale clients do not receive the same consumer protections as retail clients.
Any proposed classification should have a clear basis that can be independently assessed. A sales representative’s assertion that completing a questionnaire makes the account suitable does not resolve the issue. Nor does a record of trading shares establish that every derivative product is appropriate for the same person.
The practical question is what rights and protections would change under the proposed agreement. A genuine wholesale client still needs to assess the issuer and contract; classification does not improve the product’s expected return or remove counterparty risk.
Separate financial crime controls from product permission
Anti-money laundering and counter-terrorism financing controls address different matters from permission to issue a financial product. For example, AUSTRAC’s virtual asset service provider register allows the public to verify registration for the services covered by that regime.
That registration should not be read as authorisation to offer binary options to Australian retail clients. Similarly, a statement that a business performs identity checks does not establish that its investment claims are accurate. Each regulatory claim needs to be connected to the particular activity it actually covers.
Examine contract terms before comparing payouts
Define the event that determines the result
A contract needs to specify more than an asset name and an expiry countdown. Its outcome depends on the event definition, reference price, observation time and settlement rules. These determine whether an apparently correct market forecast produces a contractual payment.
For a high/low contract, the relevant level may be the opening reference price or another specified strike. “Above” and “at or above” are different conditions. A result exactly equal to the strike might be treated as a loss, refund or another outcome, depending on the agreement.
A touch contract also needs an observation rule. Whether a price touches a barrier cannot be assessed reliably without knowing the authorised data source and how observations are recorded. The guide to settlement and ties explains why these details can matter even when the interface appears simple.
Distinguish net profit from money returned
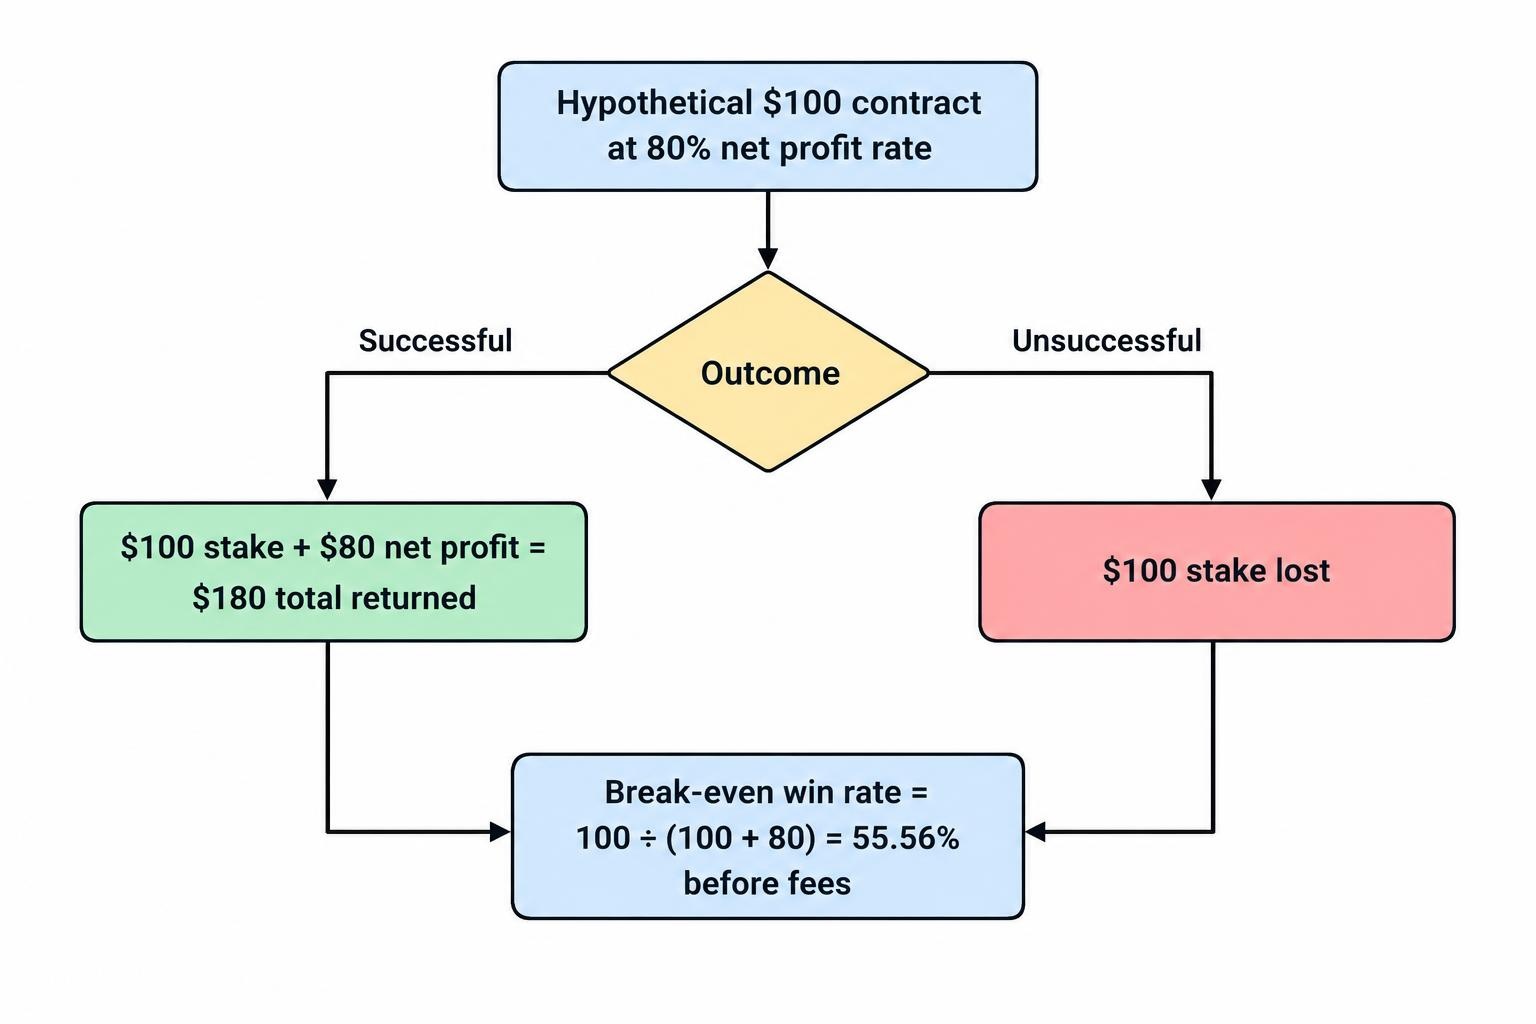
A quoted payout percentage is ambiguous unless the provider explains whether it refers to profit or total proceeds. A hypothetical 80% net profit on a $100 stake means an $80 gain and $180 returned after a successful contract. It does not mean that only $80 is returned.
If an unsuccessful contract loses the whole $100, the winning and losing amounts are unequal. Fifty wins and fifty losses would produce $4,000 in gains and $5,000 in losses: a net loss of $1,000 before any separate charges.
For equal stakes, a fixed profit rate and full loss on unsuccessful contracts, the break-even win rate is 1 divided by 1 plus the profit rate expressed as a decimal. The table uses that calculation. It is a hypothetical comparison, not a survey of current broker offers.
| Net profit on a successful $100 contract | Total returned on success | Loss on an unsuccessful contract | Break-even win rate before fees |
|---|---|---|---|
| $60 | $160 | $100 | 62.50% |
| $70 | $170 | $100 | 58.82% |
| $80 | $180 | $100 | 55.56% |
| $90 | $190 | $100 | 52.63% |
These thresholds assume no refunds, ties, early exits or changes in stake size. Different contractual outcomes require a different calculation. The underlying reasoning is explained in probability and expected value.
Compare equivalent contracts
A larger advertised payout does not establish a better opportunity. A more distant target or a more demanding condition may be less likely to occur. Comparing the payout alone excludes the probability of receiving it.
Even within one platform, rates may differ by market, expiry or time of day. An advertised maximum should not be treated as the rate available on every contract. A meaningful comparison records the actual accepted terms for the same type of event.
The expected result depends on both probability and payment. With an 80% profit rate and a true success probability of 50%, the expected result per dollar staked is negative ten cents. That follows from half of 80 cents minus half of one dollar. It is an illustration, not an estimate of any individual trader’s accuracy.
Include costs outside the contract
“No commission” is a narrow claim. It does not establish that deposits, withdrawals, currency conversion, inactive accounts, data subscriptions or third-party software are free.
An Australian dollar deposit converted into a foreign account currency may incur a conversion charge. A later withdrawal may involve another conversion and a different exchange rate. These effects should be distinguished from the trading result.
The guide to payouts and contract terms should be read alongside the complete account fee schedule. Costs need to be assessed over the intended account lifecycle, including closure, rather than only at the point of placing a contract.
Assess the platform’s records and pricing
A clear interface should expose the agreement
Usability matters when it helps users understand exactly what they are accepting. An order ticket should make the stake, direction, strike, expiry, profit and maximum contractual loss readily visible. Confirmation should preserve the accepted terms.
A dashboard that hides material details behind promotional messages or defaults to a larger stake creates avoidable ambiguity. Customisable colours and multiple chart windows are less useful than a reliable record of what was agreed.
Exportable transaction histories are particularly important. A record should allow a completed contract to be reconstructed from its identifier, timestamps, reference values and settlement result. Screenshots can supplement those records, but a picture of a moving chart may not show the data used for settlement.
Identify the reference price
Different screens can display different prices without either necessarily being fraudulent. A chart might show a last traded price, while the agreement uses a bid, offer, midpoint or calculated benchmark. Sampling intervals and timestamps can also differ.
The relevant question is whether the contract identifies its reference and applies it consistently. A statement that prices come from “the market” is too vague to resolve a dispute about a final decimal place.
For example, an apparent price of 1.0500 on a rounded chart could conceal a more precise settlement value. Whether that value satisfies the condition depends on the contract’s precision and rounding rules. The discussion of price feeds and benchmarks provides context for interpreting these differences.
Examine execution and disruption rules
Clicking an order button and having an order accepted are separate events. The agreement should explain when a contract becomes binding and which timestamp determines its terms. This is especially significant when the market changes during transmission.
Policies should also cover rejected orders, stale quotes, unavailable reference data and platform outages. If the provider reserves a right to cancel contracts because of pricing errors, the circumstances and consequences should be explained.
Automated execution does not eliminate these issues. Software can submit an instruction quickly while still relying on the provider’s acceptance process. A claim about speed is therefore incomplete without information about execution and latency, order rejection and the records available afterwards.
Put asset choice and expiry times in context
A long market menu does not establish diversification
Binary options referencing shares, currencies and commodities provide contractual exposure to specified events. They do not create ownership of the underlying assets. Selecting several market names therefore should not be equated automatically with building a diversified investment portfolio.
Contracts can share the same economic exposure. Several currency trades might all depend heavily on a move in the US dollar. An index contract and a contract on one of its major constituents can also respond to the same news.
There is a separate concentration in the provider. Holding contracts across many markets on one platform still leaves payment dependent on that provider’s obligations. Counterparty and platform risk remains even when the referenced assets differ.
The useful question is whether each market has an identifiable reference, intelligible terms and a reason for inclusion. A large menu alone establishes none of these.
Understand what the expiry changes
Expiry specifies the time at which, or the period during which, the contractual event is assessed. It should be stated in an unambiguous time zone. A countdown is convenient, but the recorded expiry and observation convention are what allow the result to be checked.
Shorter contracts increase the importance of timing, transmission delays and small price changes around the threshold. A correct longer-term view about a business or currency does not imply an ability to predict its next minute of price movement.
Longer expiry does not remove risk either. More time allows additional information to affect the price and may leave funds committed for longer. Comparing expiries therefore requires considering what is being forecast and how settlement occurs, rather than assuming that faster trading provides more opportunity.
Review deposits, withdrawals and verification
Identify the complete movement of money
Payment convenience should be assessed separately from the safety of the arrangement. A familiar card logo, bank transfer option or local payment service does not establish the identity of the issuer or its ability to meet withdrawals.
The documents should explain the account currency, accepted funding sources, applicable charges and permitted withdrawal destinations. They should also identify whether different rules apply to returning the original deposit and paying amounts above that deposit.
Processing time needs a precise starting point. A promise of payment within two business days might refer to internal approval, transfer initiation or receipt by the customer. Those are different stages. The terms should make clear when the stated clock begins and which circumstances can interrupt it.
Records of deposits and withdrawals should reconcile with the trading ledger. A displayed balance is only an entry in the platform’s records until the relevant money has actually been received.
Understand verification before sending documents
Identity checks can be a legitimate part of providing regulated financial services. The need for verification should nevertheless be distinguished from proof that the recipient is legitimate. A fraudulent operator can also request a passport or bank statement.
Before submitting documents, establish the organisation receiving them, the stated purpose and the secure submission channel. The account verification policy should explain what information may be requested and how incomplete verification affects the account.
A business may need further information after an account is opened, so an additional request is not automatically evidence of misconduct. However, contradictory demands, unexplained recipients and pressure to send documents through informal messaging channels warrant independent checking.
Read withdrawal conditions alongside promotions
A deposit bonus can change withdrawal conditions if the agreement imposes turnover requirements or distinguishes promotional credit from withdrawable cash. The headline account balance may then overstate the amount available to withdraw immediately.
A hypothetical requirement to trade thirty times a $200 bonus means $6,000 of turnover if the multiplier applies only to the bonus. If it applies to the deposit plus bonus, the required turnover could be much higher. The base used in the calculation is therefore material.
A successful small withdrawal is also limited evidence. Scamwatch’s investment scam guidance explains that scammers may allow early withdrawals to build trust before refusing larger requests. That is a reason to avoid treating a single payment as proof of continuing reliability.
Examine security and the limits of risk controls
Protect access without confusing it with solvency
Security measures address unauthorised access to accounts and information. They do not establish that a provider has sufficient assets, applies settlement rules fairly or is permitted to offer a particular product.
Australian Government guidance on multi-factor authentication explains how an additional verification step can protect accounts when passwords are compromised. Relevant controls also include clear account recovery procedures and notifications of sensitive changes.
A secure connection protects data during transmission; it does not validate the commercial claims on the website. Similarly, an assertion that a platform undergoes security audits needs a defined scope and date. An audit of software controls would not necessarily address customer money, financial statements or contractual compliance.
Read early-exit features as contract terms
An early-close button may offer a way to exit before expiry, but its value depends on availability and price. It should not be assumed to operate continuously or return the original stake.
A provider might withdraw quotations during volatility or stop offering early closure near expiry. Those possibilities need to be assessed from the agreement. If an exit value is discretionary, the trader cannot treat it as a guaranteed loss limit.
Other features can increase exposure. “Double up” typically describes adding another position, while a rollover may extend exposure under new conditions. The guide to early close, rollover and double-up features distinguishes their mechanics. A feature should be judged by its effect on money at risk, rather than by the platform’s risk-management label.
Evaluate support and complaint arrangements
Test the substance of support
A fast response is useful only if it addresses the question accurately. The strongest operational test is whether support can explain a specific contractual provision and provide a durable written answer.
For example, an enquiry about a disputed settlement should identify the governing price source and observation time. A reply that simply repeats that the platform is reliable does not resolve the issue. The same applies when questions about withdrawal eligibility produce requests for a larger deposit.
An account manager’s title does not establish independence or qualification to provide personal financial advice. Their role may be customer service, sales or retention. The distinction matters when a conversation shifts from explaining account administration to encouraging particular trades.
Support hours should be stated with a time zone and realistic response expectations. Markets have different trading sessions, holidays and maintenance periods; the general claim that global markets operate continuously is too imprecise to establish useful coverage.
Establish who can handle a dispute
Internal complaint handling should identify where complaints are sent, how they are acknowledged and how a final response is delivered. This creates a record separate from routine sales or support conversations.
Moneysmart’s complaint guidance describes raising the issue with the business and escalating unresolved financial complaints to an appropriate independent body, including AFCA. Eligibility needs to be established for the actual firm and circumstances; a logo on a website is insufficient.
Keep the agreement applicable at the time, transaction records, payment receipts and correspondence. These documents help distinguish a disagreement about contractual settlement from an unauthorised payment or a refusal to return funds.
An overseas address can add practical difficulty to pursuing a claim. A governing-law clause should therefore be considered together with available dispute processes and the identity of the business against which any decision would need to be enforced. A promise of “international protection” needs specific supporting details.
Assess education and demo accounts critically
Evaluate what educational material actually explains
Educational content is useful when it makes the contract and its limitations easier to understand. A sound explanation addresses losing outcomes, payout asymmetry, settlement rules and costs alongside chart patterns.
The quantity of webinars or downloadable guides does not establish their accuracy. Content that attributes losses exclusively to poor discipline can obscure the role of the payment structure. Even a consistently applied method can have negative expected returns.
Claims about signals require particular care. A reported win rate is incomplete without the sample period, number of observations, payout assumptions and treatment of rejected or unavailable trades. For example, a 60% success rate has different implications at a 50% net profit payout than at a 90% payout.
The discussion of evaluating track records is relevant to both paid signals and broker education. Selected screenshots of profitable outcomes do not establish the results of all recommendations over a defined period.
Use demos to understand mechanics
A demonstration account can show how an interface handles order entry and account records without risking trading capital. It cannot demonstrate that a live provider will honour withdrawals or that simulated conditions match executable contracts.
The comparison should consider the displayed payouts, available expiries, order acceptance and reference data. A profitable demo sequence provides little evidence if the live account uses materially different terms.
Simulation also changes behaviour. A resettable balance does not create the same financial consequences as losing money needed for other purposes. This limits what can be inferred from a user’s willingness to take risk in practice.
The guide to demo versus live accounts should therefore be read as a comparison of conditions and evidence. A demo is a tool for understanding software, not certification of the provider or proof of a profitable strategy.
Weigh the evidence before making a decision
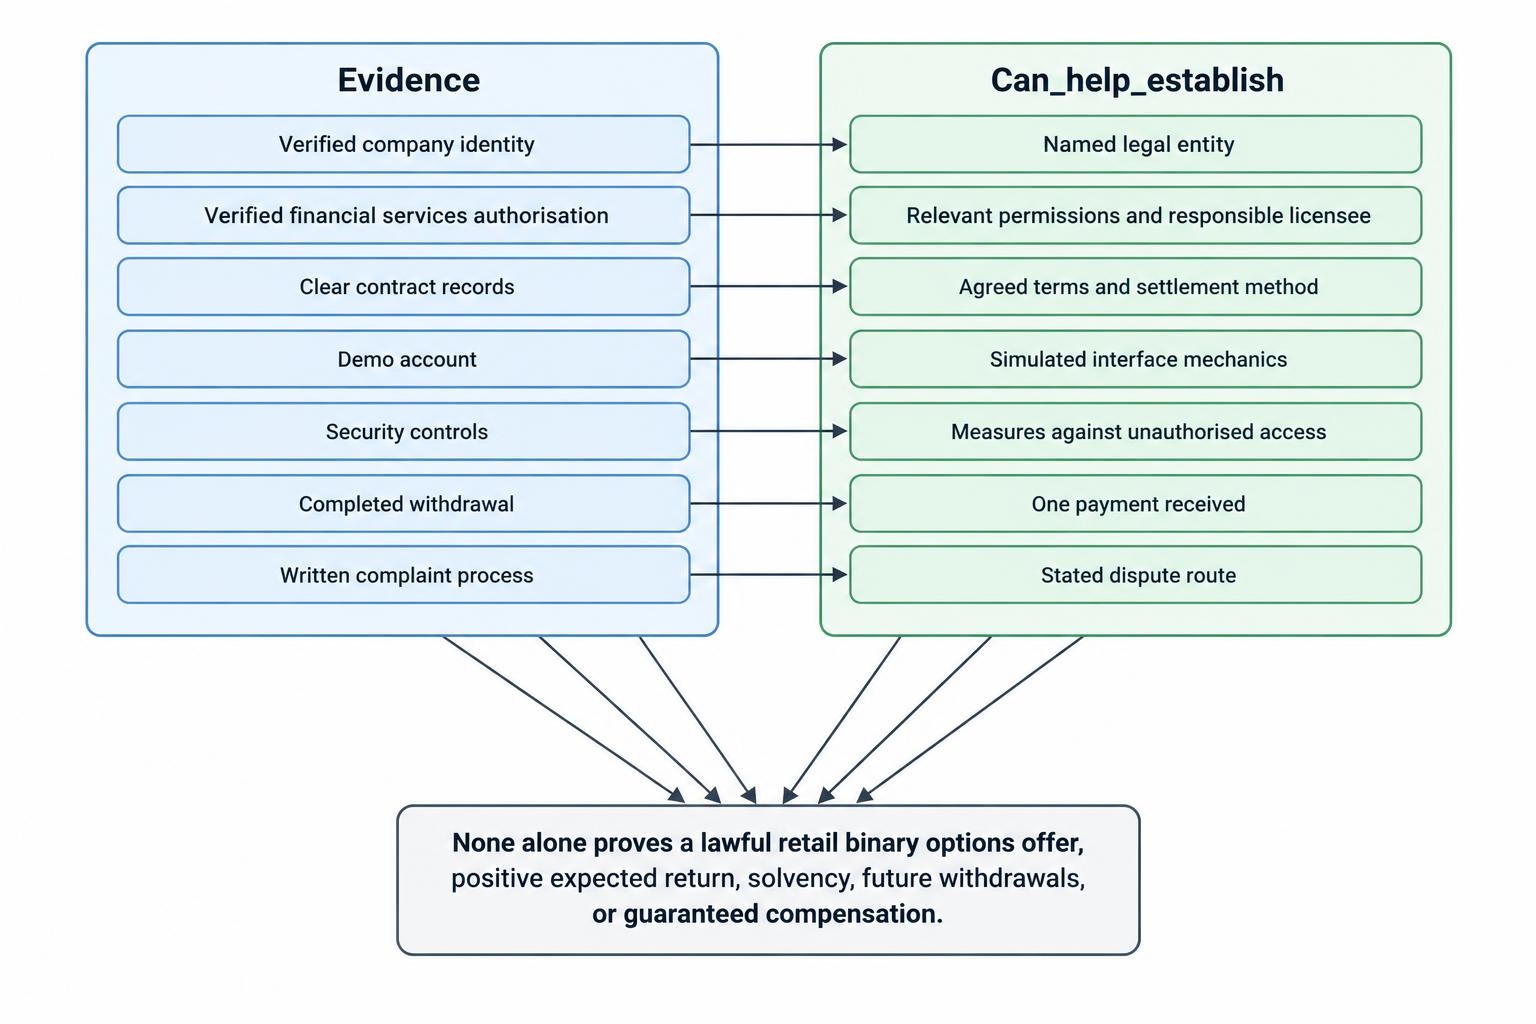
Different broker features support different conclusions. They should not be combined into a general impression of trustworthiness without considering what each one actually verifies.
| Evidence or feature | What it can help establish | What it does not establish |
|---|---|---|
| Verified company identity | Which legal entity is named in the documents | Authority to offer every advertised product |
| Verified financial services authorisation | The relevant permissions and responsible licensee | An exception to the retail binary options ban |
| Clear contractual records | The agreed event, payment and settlement method | A positive expected trading return |
| Demonstration account | How the simulated interface operates | Live execution quality or withdrawal reliability |
| Account security controls | Measures against unauthorised access | Solvency or fair contract administration |
| A completed withdrawal | That one payment was received | That future withdrawals will be honoured |
| Written complaint process | A stated route for raising a dispute | Guaranteed recovery or compensation |
For Australian retail readers, the product restriction determines whether the broker-selection exercise can proceed. Attractive features cannot compensate for an offering that cannot lawfully be provided to that customer category.
Where the underlying objective is market exposure, alternatives to binary options need to be assessed on their own terms. Ownership, time horizon, fees and capacity for loss are more useful starting points than similarity to a binary options interface.
CFDs should not be presented as an automatically suitable substitute. Moneysmart describes CFDs as complex, costly and high risk, with most users losing money. Their variable profits and losses, leverage and funding costs require a separate assessment.
The purpose of reviewing broker claims is to establish what can be verified and what remains uncertain. A decision grounded in the exact entity, applicable rules and contractual obligations is more defensible than one based on promotional payouts, a polished platform or responsive sales staff.
This article was last updated on: October 22, 2026