Automatic binary options trading uses software to turn market observations into contract decisions and order instructions. The system may select an asset, direction, stake and expiry, submit an order, record its acceptance and monitor the eventual settlement. A person defines or approves the rules, even when individual trades require no further intervention.
Automation can reduce repetitive work and apply rules consistently. It also allows a faulty assumption, programming error or inappropriate stake rule to affect many contracts before anyone responds. The relevant question is therefore whether the complete process is reliable and economically sound, rather than whether it operates without manual input.
A binary option links its payout to a defined condition, such as a reference price finishing above a specified level at expiry. The accepted terms determine what constitutes success, how ties are treated and whether an early exit is available. Automatic trading does not change those terms.
General background is available through the Binary Options Australia index page. Binary Options.Net also provides international coverage. Product availability and regulatory requirements still need to be checked against the rules applying to the reader.
The Australian retail restriction comes first
ASIC prohibited the issue and distribution of binary options to retail clients from 3 May 2021. The prohibition has been extended until 1 October 2031. Using a script, hosted robot or copying service does not create an exception.
An overseas website accepting Australian registrations is not evidence that the offer complies with Australian requirements. Nor does a provider’s licence for other financial services override the binary options restriction. The article on ASIC’s binary options regulations explains that distinction.
Automation also should not be confused with a regulatory category of its own. A service may provide software, financial product advice, dealing or other functions depending on its actual operation. ASIC’s digital advice guidance addresses financial advice delivered using algorithms and technology.
For Australian retail readers, researching a system through historical data or simulation is different from funding a prohibited product offering. The software principles discussed here describe how automation works and how its claims can be assessed.
How an automated trading system is organised
A signal is only one part of the process. A complete system also needs to decide whether the proposed contract is available on acceptable terms and whether the account has capacity for the exposure.
These functions should be distinguishable in the system’s records. Otherwise, a disappointing result may be attributed to the strategy when the actual cause was delayed execution, an incorrect expiry or a duplicated order.
| System component | What it does | What its records should establish |
|---|---|---|
| Data handling | Receives and checks prices and other inputs | Source, timestamp, freshness and missing observations |
| Strategy logic | Converts observations into a proposed trade | Rule version, relevant inputs and intended contract |
| Risk controls | Approves or rejects the proposed exposure | Stake, open commitments and remaining limits |
| Execution | Sends instructions and checks their status | Submitted request, acknowledgement and accepted terms |
| Settlement and reconciliation | Records outcomes and checks account movements | Contract result, fees and differences between records |
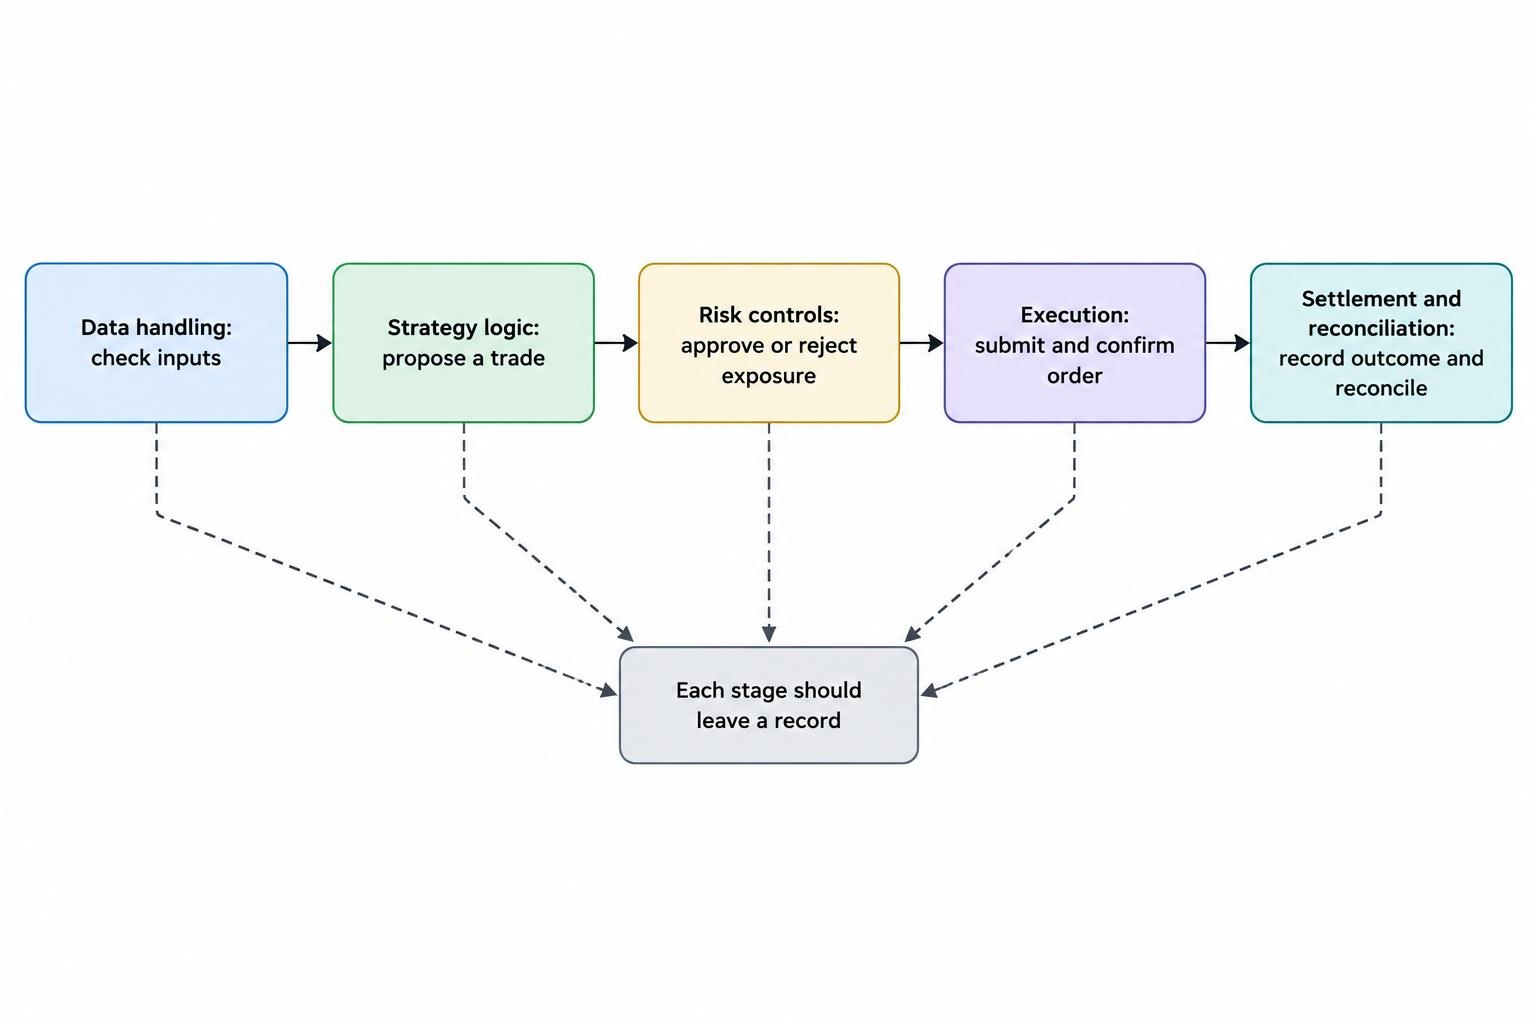
A robot may combine these functions in one application. That does not remove the need to understand them separately.
Strategy rules need to match the contract
Trend-following systems attempt to act on continuing price movement. Mean-reversion systems attempt to act on a return towards a reference level. Breakout systems respond when a price moves beyond a defined boundary. Each is a description of an idea, rather than a complete trading rule.
The same idea can behave differently across contract durations. A signal associated with an upward move over several hours may provide little information about where the price will be after thirty seconds.
The system also needs to distinguish a chart level from a contractual threshold. An analysis tool may identify a price at the time of the signal, while the available contract uses a threshold determined later.
Indicator settings, data intervals and entry timing must therefore be specified. Saying that software uses moving averages or artificial intelligence leaves these questions unanswered.
Execution automation and strategy automation
Execution automation carries out instructions already selected by a person or another system. Strategy automation also decides which instructions to generate. Copy trading adds a further dependency because another account’s activity becomes the input.
These arrangements create different responsibilities. An execution tool can work correctly while carrying out a poor decision. A strategy can generate a reasonable proposal that becomes unattractive by the time the order is accepted.
The related guide to binary options trading robots discusses packaged software and signal services. The broader operating process matters because a robot’s advertised strategy explains only part of the result.
The economics automation must overcome
Payouts determine the required success rate
Consider a hypothetical fixed-return contract with a $100 stake. A successful outcome earns $80 net profit and returns the stake; an unsuccessful outcome loses the $100.
At a 50% success rate, the average result is a $10 loss per contract before other costs. Half of $80, less half of $100, equals minus $10.
The break-even success rate is approximately 55.6%, assuming identical stakes and payouts, no ties and no additional costs. A different payout produces a different threshold. The guide to binary options payouts explains the calculation.
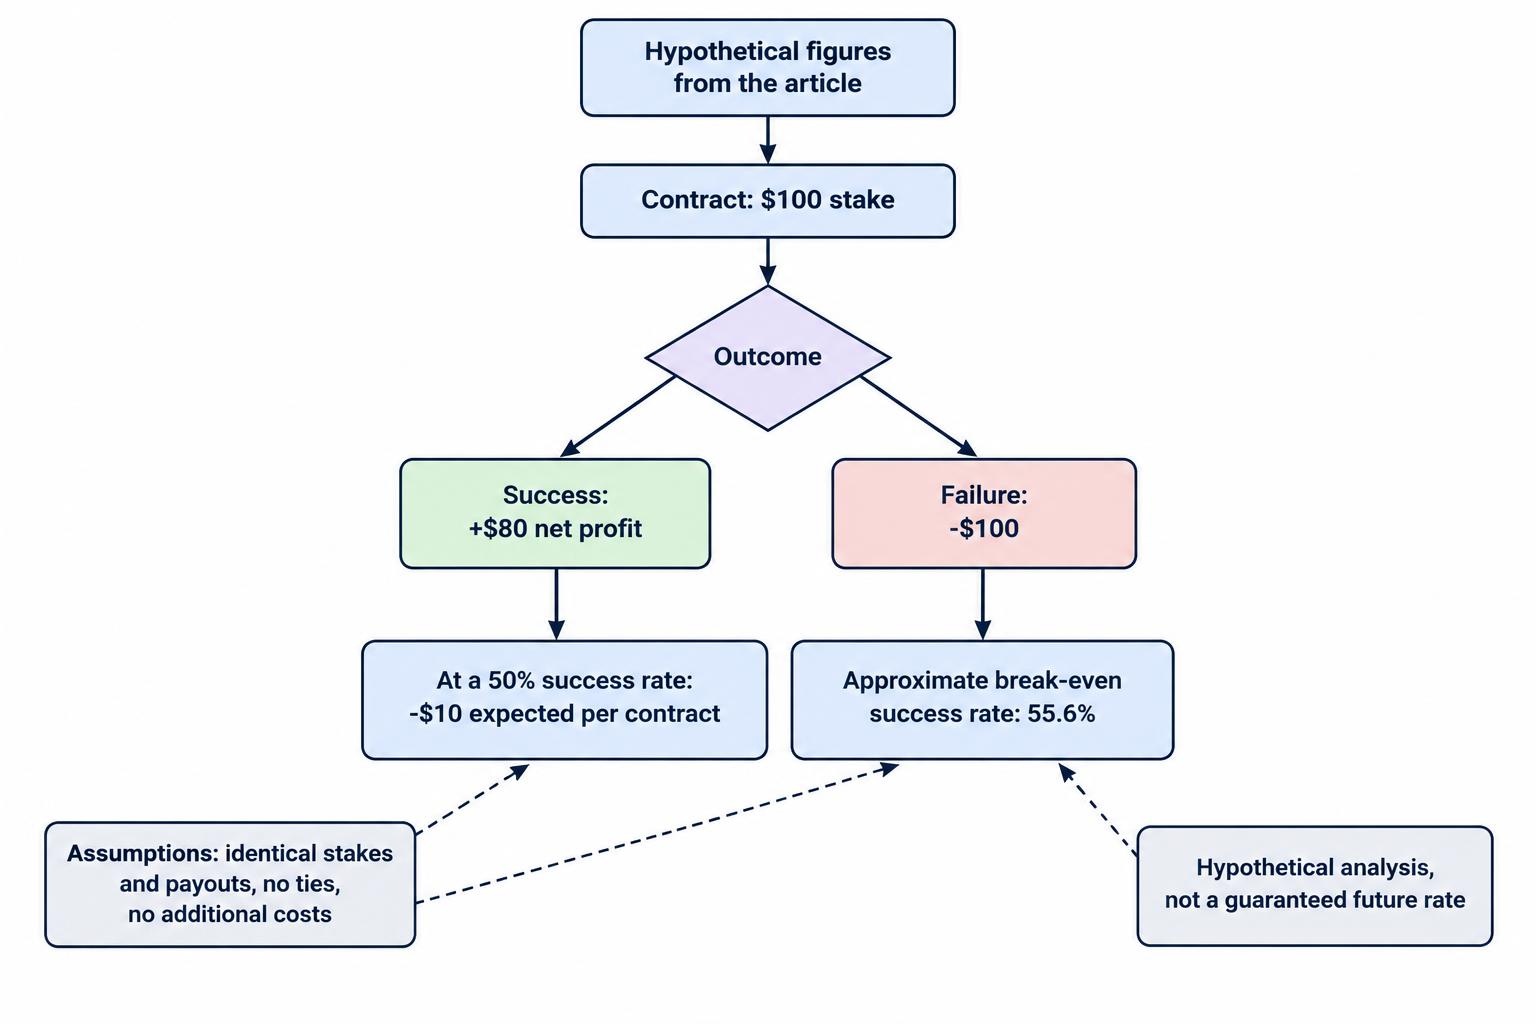
This structure creates a hurdle. It does not mathematically prove that every possible strategy has negative expected value. A strategy would need sufficiently accurate conditional forecasts, available on executable terms, to exceed the hurdle after costs. Claiming such an advantage is much easier than demonstrating it.
A historical win rate also is not a known future probability. It is an estimate drawn from a particular sample and can change when the market, data or execution conditions change.
Accepted terms matter more than advertised terms
A provider’s maximum advertised payout may be unavailable for the asset or expiry selected by the system. A strategy tested using that maximum will overstate results if actual contracts offer less.
The system’s decision rule should therefore evaluate the terms available for the proposed transaction. An old payout stored in a settings file is not enough if the offer changes during operation.
Costs should be modelled according to the product. A conventional fixed-return over-the-counter contract is not necessarily charged through the same spread and commission structure as an exchange-traded option. Applying a generic fee model can be as misleading as omitting costs.
Subscriptions, hosting, data charges and currency conversion remain relevant even when there is no separately labelled trading commission.
More trades do not establish a better strategy
Suppose a hypothetical system earns $120 from its contracts in a month but costs $150 in subscriptions and hosting. Its result is a $30 loss before other expenses.
Increasing the number of contracts might spread fixed software costs over more activity. It also increases exposure to the strategy’s weaknesses. Additional trades improve the outcome only if their expected contribution is positive after their own costs.
A useful performance report therefore separates gross contract results, direct charges and recurring operating expenses. A single percentage labelled “accuracy” cannot replace that information.
Price data, settlement and execution
Independent data is a comparison, not a replacement for the contract
An automated system needs to know which price determines the outcome. The contract may reference an exchange price, a published benchmark or a provider-defined quotation process. Its terms should also explain the observation time and treatment of equality.
An independent feed can help identify stale data or unusual differences. It cannot automatically override the agreed settlement reference.
For example, two currency feeds may publish different quotes because they use different contributors or quote conventions. A midpoint, a bid and an offer are not interchangeable. A discrepancy needs investigation before being described as manipulation.
The appropriate comparison uses equivalent instruments, timestamps and price definitions. Comparing a stock’s last trade on one venue with a derivative provider’s indicative quote on another may reveal little.
The guide to settlement and ties explains why the precise condition matters. Automation needs those rules encoded explicitly; a chart that looks correct is insufficient.
Data quality has several dimensions
A feed can be connected while supplying old observations. The system therefore needs to distinguish connection status from data freshness.
Missing observations, out-of-order messages and changes in decimal precision can also affect calculations. A strategy interpreting a price in the wrong units may generate perfectly consistent decisions from incorrect inputs.
The relevant timestamps should be identifiable. The time an event occurred, the time a feed published it and the time the application received it can differ. Those distinctions become more consequential as contract durations shorten.
A sensible response to uncertain data is often to prevent new instructions while the discrepancy is assessed. Substituting another feed without accounting for its different definitions can introduce a new error rather than resolve the first one.
APIs and screen-based automation
An application programming interface, or API, provides a defined way for software to request information and submit instructions. Where officially supported, documentation can clarify valid order parameters, permissions, limits and responses.
An API is not evidence that a financial product is authorised or that the provider is reliable. It is a technical connection.
Screen-based automation instead interacts with buttons, fields or page elements. A changed layout, an unexpected message or an expired session can cause such software to act on the wrong control or stop functioning.
The existence of a working script also does not establish that the platform permits that use. Access methods should comply with the provider’s documented terms. An integration should not depend on bypassing authentication or platform restrictions.
Submission is not acceptance
An order can be created locally, transmitted, received and accepted at different times. A reliable record distinguishes each stage.
Suppose a hypothetical instruction is transmitted shortly before a purchase deadline. If the acknowledgement is delayed, the software cannot safely conclude that the order failed. The provider may already have accepted it.
Submitting the same instruction again without checking status may create another contract. Systems need a documented way to identify requests and reconcile uncertain outcomes before retrying.
Order handling also depends on the market structure. Partial fills may be relevant on an order-book venue, while another platform may accept or reject a fixed-stake contract in full. Testing should reproduce the actual arrangement.
The explanation of execution and latency covers these timing differences. The decisive evidence is the accepted contract record, including its terms, rather than the speed of an on-screen animation.
Backtesting and simulated forward testing
Historical prices alone are insufficient
A backtest calculates what a set of rules would have produced using historical inputs and stated assumptions. For binary options, the required assumptions include available expiries, payout rates, entry conditions and settlement treatment.
A price series may not contain that information. If historical payout quotes are unavailable, the test should identify the assumed payouts and examine how different values change the result.
Data resolution also constrains what can be reconstructed. A minute’s opening and closing prices do not establish every movement within that minute. Even a recorded high and low may not establish the order in which levels were reached.
That distinction matters for contracts whose outcomes depend on a touch or a path rather than only the final observation. The test must match the type of binary option being analysed.
Hindsight can enter through ordinary settings
A strategy must use only information available at its decision time. Acting on the final closing price of a candle before that candle would have completed introduces information from the future.
Revised economic data, indicators that alter historical signals and retrospective selection of favourable trading sessions can create similar problems.
A test may also select instruments because they are known to have behaved favourably during the period. The resulting performance reflects that selection as well as the strategy itself.
These issues are not resolved by making the simulation faster or more detailed. The chronological availability of information needs to be correct.
Repeated optimisation can produce misleading winners
Trying many parameter combinations and publishing only the best result hides the number of opportunities for a chance finding.
Bailey, Borwein, López de Prado and Zhu analyse this problem in The Probability of Backtest Overfitting. Their research explains why selecting strategies through repeated historical testing can produce impressive results that do not persist.
Separating development data from evaluation data is useful, but repeated inspection can contaminate that separation. Once an evaluation period influences the next version of the strategy, it is no longer an untouched test.
The provider should disclose how the strategy was selected and whether the advertised record excludes unsuccessful versions. The guide to backtesting binary options strategies discusses the practical implications.
Testing adverse conditions
A system should be examined under less favourable assumptions, including lower payouts, delayed acceptance, interrupted feeds and longer losing sequences. The purpose is to identify where its behaviour becomes unacceptable.
Randomly reordering historical trades can illustrate sensitivity to sequences, but it cannot invent market conditions absent from the sample. It can also obscure relationships between trades that occur together.
Similarly, a walk-forward exercise develops rules on one period and evaluates them on a later period, then repeats the process. It provides a structured test, not a guarantee that the next market environment will resemble the earlier ones.
The useful output is more than a final return. It includes drawdowns, largest committed stakes, rejected instructions and the frequency with which controls stopped activity.
Shadow operation without funded orders
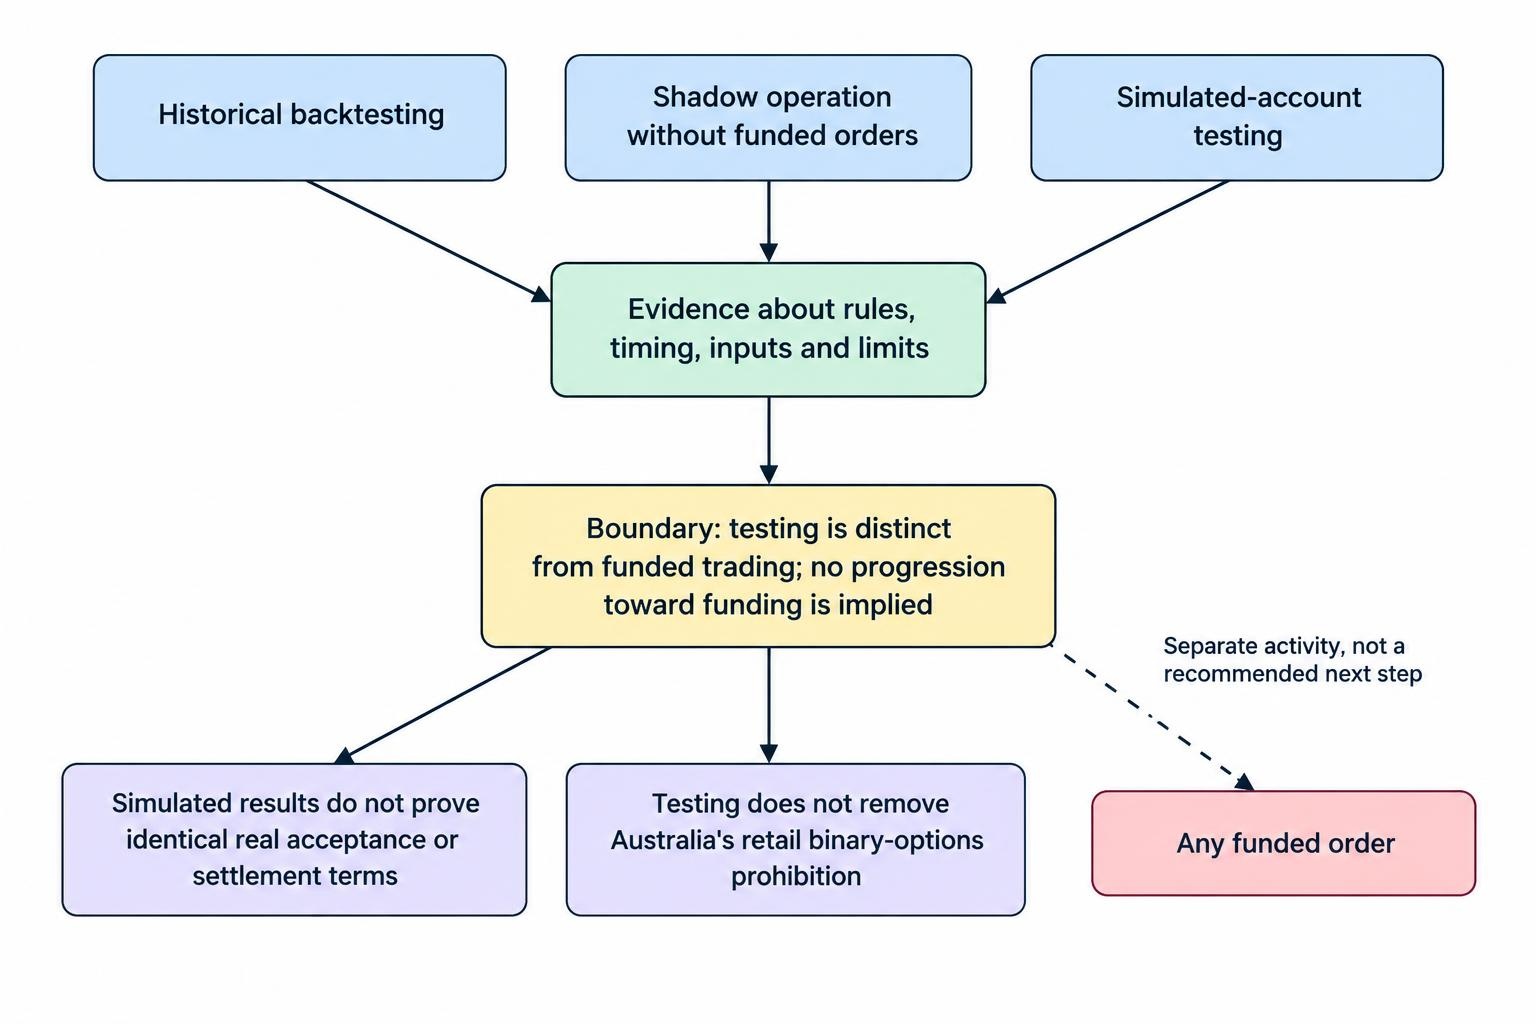
In shadow mode, software receives new data and records the orders it would propose without submitting funded transactions. This can expose timing errors, stale inputs and inconsistent settings.
A simulated account can also check whether the system respects its limits. Neither method proves that real orders would receive identical acceptance or settlement terms.
For Australian retail readers, these are research methods rather than a recommended path towards funding binary options. No successful simulation removes the retail prohibition.
Exposure limits and operational failures
Define exposure in money at risk
For a standard fully paid binary-option purchase, the contractual trading loss is generally limited to the purchase amount and applicable fees. The value of the referenced share, index or currency exposure should not be confused with that amount.
A robot can nevertheless exhaust an account by repeatedly committing new stakes. If money was borrowed to fund it, the borrowing obligation remains separate from the contract outcome.
Controls need to cover both individual instructions and aggregate exposure. Several strategies operating within their own settings may collectively commit more money than intended.
Suppose an account contains $2,000 and permits no more than $100 in additional contract losses. If $80 is already committed to open contracts, the remaining allowance is at most $20 under that simplified worst-case calculation, before fees or uncertain pending orders.
A realised-loss limit is incomplete
A daily limit triggered by settled losses alone may react too late. Several contracts can be accepted before earlier ones expire, leaving substantial exposure after the threshold is reached.
The system needs to account for open stakes and requests whose status remains uncertain. It should also specify the time zone and conditions used to reset limits.
Funding an account or restarting the software should not silently erase the record of an already reached threshold. Otherwise, an operational action can change the intended risk allowance.
The guide to stake sizing explains why these limits need a monetary basis.
Recovery systems can increase the problem
Increasing stakes after losses does not improve the underlying forecast. It changes the distribution of financial outcomes and the amount required to continue.
At an assumed 80% net winning payout, losses on stakes of $10, $20 and $40 total $70. A subsequent win on an $80 stake earns $64, leaving the sequence $6 down before costs.
A rule that increases stakes further to target full recovery still faces finite capital, contract limits and the possibility of another loss. A high proportion of completed profitable sequences can conceal the size of an unfinished losing sequence.
The discussion of martingale strategies provides more detail. Terms such as recovery mode do not change the exposure created by the rule.
Stopping software does not necessarily close contracts
A kill switch can prevent new instructions. It does not automatically reverse instructions already accepted or create an early-exit right.
The system’s stop procedure must therefore distinguish new orders, uncertain submissions and open contracts. Some contracts remain exposed until expiry even after automation has been disabled.
Closing a laptop also may leave a hosted service running. Revoking an authorised connection and stopping a remote process are separate from shutting the local interface.
A restart should begin by comparing account records with the software’s stored state. Resuming from an old balance or assuming that previously submitted orders disappeared can create duplicate or excessive exposure.
Concentrated signals and shared failures
Several trades may depend on the same economic event or price source. Different instruments do not necessarily provide independent outcomes.
A single data error can also affect every strategy using that feed. Diversifying strategy names does not diversify a shared technical dependency.
Controls should therefore consider related exposures and shared infrastructure. A limit on the number of contracts is useful only when the stakes and common risks are also understood.
Providers, records and ongoing oversight
Commercial incentives need to be visible
An automated service can earn subscription fees, referral payments or remuneration linked to account activity. These arrangements may affect which platforms it supports and how strongly it encourages trading.
A free robot can therefore have an economic cost even without a software invoice. The important question is who pays the supplier and what behaviour generates that payment.
The guide to signal and software costs covers recurring charges. Hosting, data and conversion costs also belong in the assessment.
Terms should explain how subscriptions end, what happens to stored credentials and whether the service continues operating after the user closes its interface. Cancelling payment and revoking trading access should not be assumed to be the same action.
Verification has practical limits
Full source-code disclosure is not available for every commercial system. Its absence does not itself prove fraud. However, the operator should still explain account permissions, stake behaviour, supported contracts, fees and stopping conditions.
Raw transaction records are more useful than selected screenshots, but their origin needs checking. A dashboard can display simulated or fabricated activity.
The US SEC’s binary options fraud warning describes complaints involving withheld funds, identity theft and manipulated software. These are reasons to examine the provider as well as the trading model.
The CFTC has also warned about automated systems promoted through unrealistic AI profit claims. A technical label is not performance evidence.
An account balance and a successful small withdrawal establish less than continuing access to all funds. Software quality cannot solve a counterparty’s refusal to pay.
Reconciliation and records
Reconciliation means comparing records that should agree. The system’s accepted orders should match the provider’s transaction history, and the resulting cash movements should match the account ledger after charges and transfers.
A difference may result from fees, time-zone treatment, missing records or an unresolved transaction. It should be explained rather than silently removed from the report.
Useful records preserve the strategy version, settings, relevant inputs, instructions, acknowledgements and settlement outcomes. Credentials and authentication secrets do not belong in ordinary logs.
Records also support tax reporting. Using an offshore account does not by itself make income exempt from Australian reporting requirements. The ATO explains the general position for Australian tax residents in its guidance on foreign and worldwide income.
The treatment of a particular contract or loss depends on its circumstances; automation alone does not determine it. Material uncertainty warrants advice from a registered tax agent familiar with the transactions.
Changes require a new assessment
A strategy update can alter exposure even if the interface looks unchanged. New parameters, instruments or stake rules mean the previous record may no longer describe the operating system.
Version records make that change visible. They also allow an investigation to distinguish a market-related loss from a software change or configuration error.
Review should include the conditions under which the system is paused or retired. Continuing because development work was expensive is not evidence that the current process remains worthwhile.
Automation can also serve narrower purposes in markets available to Australian retail clients, such as research, alerts or administrative records. The guide to alternatives to binary options explains product differences; exchange trading or central clearing does not remove market risk.
A credible automated process has explicit rules, matched contract data, controlled permissions and results measured after costs. Its ability to continue without human input increases the need for those features. It does not replace them.
This article was last updated on: October 22, 2026