What counts as a legal alternative in Australia
Australian retail investors can access shares, exchange-traded funds and, through providers with the relevant authorisations, several types of derivatives. These products offer different ways to invest, hedge or speculate. Their availability does not make them interchangeable or guarantee that any particular account application will be accepted.
ASIC prohibited the issue and distribution of binary options to retail clients from 3 May 2021 and has extended the prohibition until 1 October 2031. Moving to an offshore website, using an automated system or changing the product’s marketing name does not establish an exemption.
A legal alternative needs to be assessed through both the product and the service supplying it. The relevant legal entity must have the authority needed for its activities, and the offer must comply with Australian requirements. A foreign licence or an accessible website does not settle that question.
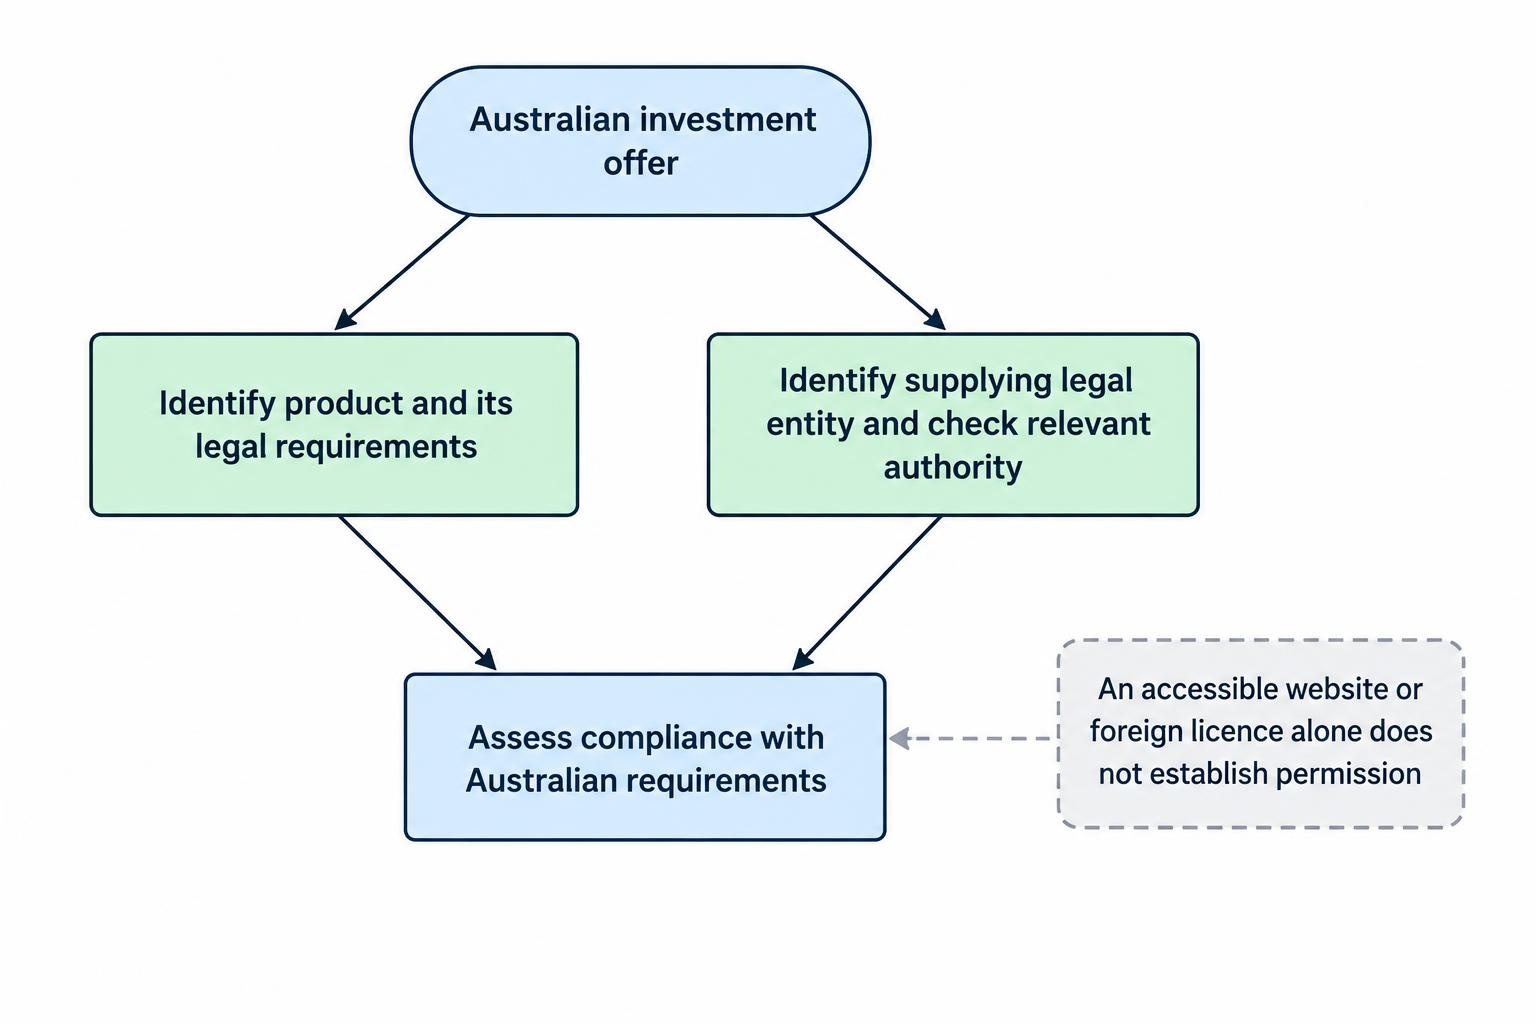
The most useful starting point is the purpose of the money. Someone seeking long-term capital growth has different requirements from someone hedging an existing shareholding or speculating on an intraday currency move. Someone who mainly wants to preserve savings may not need a trading product at all.
Legal availability does not mean lower risk
A standard fully paid binary-option purchase can have a contractual loss limited to its purchase amount, even though repeated losses can exhaust an account. Some alternatives, particularly futures and written options, can create losses beyond the initial amount committed.
Conversely, buying ordinary shares with available cash does not require borrowing or a contractual expiry. A diversified fund can provide exposure to many assets without requiring a prediction about the next few minutes.
These differences matter more than whether a platform resembles a familiar binary options interface. The guide to ASIC’s binary options regulations explains the Australian restriction. The comparisons below describe other structures, using rules and regulator guidance checked on 22 October 2026.
Comparing the main alternatives
The following comparison assumes ordinary cash purchases for shares and conventional ETFs. Borrowing, short selling and specialised fund structures can change the risks. Derivatives access remains subject to the provider’s authorisations, account terms and customer assessment.
| Product | What the customer holds | Main difference from a binary option | Main loss consideration |
|---|---|---|---|
| Cash-funded shares | Ownership of shares in a company | Variable price exposure without a contractual expiry | The purchase amount can be lost, plus costs |
| Conventional ETFs bought with cash | Units in a fund holding a portfolio or following a strategy | Exposure to underlying investments rather than a fixed yes-or-no payout | Market losses and fund-specific risks; no guarantee against loss |
| Purchased standard options | A contractual right acquired for a premium | Outcome depends on the underlying price and option terms | Premium and costs are at risk; exercise can create further exposure |
| Written options | A contractual obligation | Premium received in exchange for accepting obligations | Losses can exceed the premium; some positions have unlimited loss potential |
| Exchange-traded futures | A standardised derivative contract | Variable gains and losses on a defined contract size | Losses can exceed initial margin |
| Retail CFDs and margin forex | Contractual exposure through an issuer | Gains and losses vary with the referenced price | The funded CFD account can be lost despite retail protections |
| Eligible savings accounts and term deposits | A deposit with an authorised institution | Interest income rather than short-term price speculation | Inflation, access conditions and protection limits matter |
You can find a reliable broker for trading all this asset classes by visiting BrokerListings.com, a reliable website that make it easy to find and compare honest locally regulated brokers.
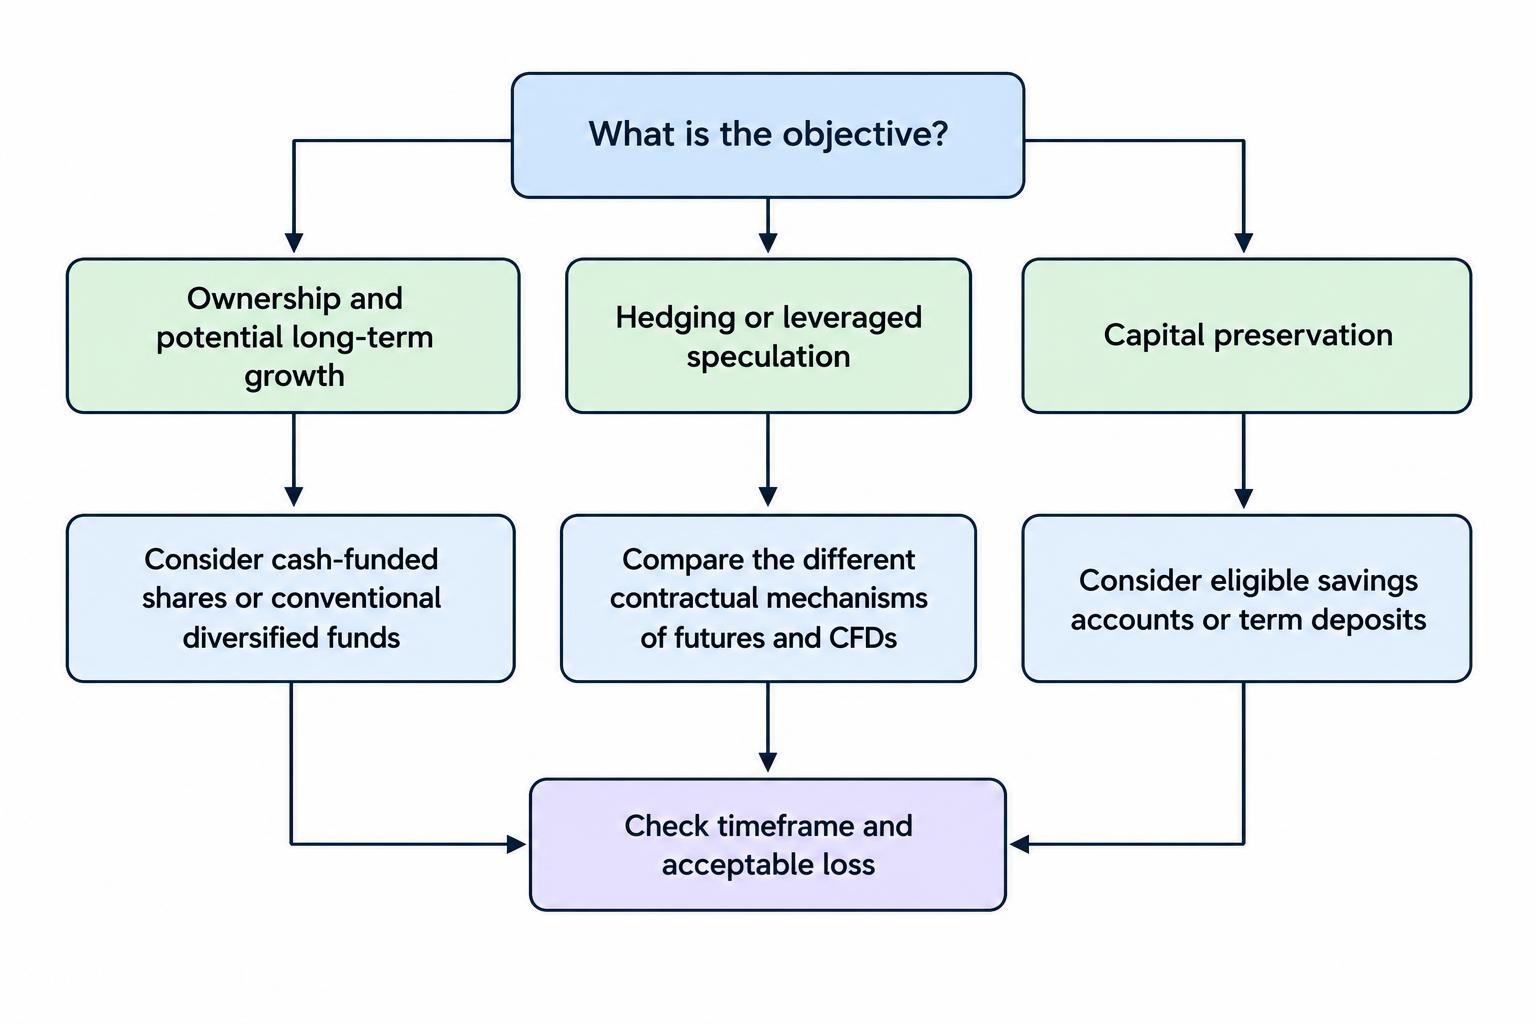
Match the product to the objective
For ownership and potential long-term growth, cash-funded shares and conventional diversified funds deserve consideration before complex derivatives. They can still suffer substantial declines, so money needed soon may be unsuitable for equity exposure.
For a defined directional view with an identifiable premium at risk, purchased standard options provide a structure worth understanding. Their expiry and pricing complexity remain important constraints.
For hedging or leveraged speculation, futures and CFDs provide different contractual mechanisms. Their low initial funding requirements should not be confused with low economic exposure.
A capital-preservation objective points towards a different comparison, including deposit accounts. Changing the objective from frequent speculation to saving is also a valid response to the limitations of binary options.
The available product should follow the objective and acceptable loss. Choosing a product because it offers the largest position for the smallest deposit reverses that process.
Cash-funded shares and exchange-traded funds
Shares provide ownership
A share represents part ownership in a company. Returns can come from changes in its price and dividends, although dividends are not assured. Moneysmart’s explanation of share dealing describes how shares are bought and sold through brokers and other arrangements.
For a purchase funded entirely with cash, an ordinary fully paid share position does not create a margin obligation simply because its market price falls. The investment can nevertheless lose all its value.
Consider a hypothetical purchase of 200 shares at $15 each. The initial purchase costs $3,000 before brokerage. A later sale at $16 produces a $200 gross gain; a sale at $14 produces a $200 gross loss.
There is no predetermined payout ratio in that example. The result depends on the price change, quantity and costs. A one-cent movement below the purchase price does not automatically eliminate the whole investment at a fixed expiry.
This does not make the shares appropriate for every timeframe. A company announcement, trading halt or poor liquidity can prevent an exit at the intended price. Keeping a losing position open also does not guarantee recovery.
The comparison of binary options and share dealing explains the ownership distinction.
ETFs provide portfolio exposure
An exchange-traded fund, or ETF, gives investors units in a fund. A conventional broad-market equity ETF may hold shares across many companies, reducing dependence on one issuer while retaining exposure to market declines.
Moneysmart’s ETF guide describes diversification, management costs and risks such as market, sector, currency and liquidity exposure. The holdings and strategy determine what the investor actually owns economically.
A narrowly focused technology or resources fund is different from a broad-market fund. An overseas fund can also expose an Australian investor to currency movements, depending on its hedging arrangements.
The ETF label alone does not establish simplicity. Leveraged, inverse and other specialised funds require separate assessment. Their behaviour can differ from an ordinary portfolio of shares, particularly over longer holding periods.
The guide comparing binary options and ETFs covers the difference between fund ownership and a contract settled on a single condition.
Trading frequency changes the cost calculation
Shares and ETFs can be traded actively, but the ability to buy and sell frequently is not a reason to do so. Brokerage, spreads and execution differences accumulate with turnover.
Suppose an illustrative $2,000 position incurs $10 to buy and $10 to sell. The $20 round-trip brokerage equals 1% of the initial position before any spread or price movement. A small favourable movement may therefore produce no net profit.
A longer holding period spreads entry and exit costs over more time, but also leaves the investment exposed for longer. Neither approach guarantees a better outcome.
Account arrangements need attention too. Investors should understand how ownership is recorded, who holds the assets and what transfer rights apply. An application displaying a company’s share price may be offering a CFD or another exposure rather than actual shares.
CFDs and margin forex
Flexible exits come with different obligations
A contract for difference, or CFD, is an agreement with an issuer based on the change in a reference price. A share CFD does not give the holder ownership of the referenced shares.
Unlike a conventional binary option, the result usually varies with the size of the price movement. A trader can generally request closure while the product is tradable, subject to liquidity, platform availability and the contract terms.
The issuer remains a counterparty. CFDs do not automatically move the customer into an exchange order book or eliminate conflicts of interest. Moneysmart’s CFD guide explains their structure and risks.
The word forex also needs clarification. Exchanging Australian dollars for another currency is different from opening a leveraged margin-forex position. A platform’s “spot forex” label should not be taken as proof of an unleveraged currency purchase.
The comparison of binary options and CFDs explains the different payout structures. Greater flexibility requires more decisions about exposure and exits.
Australian retail protections
ASIC’s CFD intervention limits the leverage providers may offer retail clients. The relevant maximum depends on the reference asset.
| CFD reference asset | Maximum retail leverage |
|---|---|
| Major currency pair | 30:1 |
| Minor currency pair, gold or major sharemarket index | 20:1 |
| Commodity other than gold or minor sharemarket index | 10:1 |
| Shares or other assets | 5:1 |
| Crypto-assets | 2:1 |
ASIC’s explanation of the measures also covers margin close-out, negative balance protection and restrictions on certain inducements. These are provider limits and protections, rather than recommended trading settings.
Negative balance protection operates at the covered retail CFD account level. It does not make the margin allocated to one position its maximum loss, and it does not prevent loss of all the money in that account.
The current order is due to expire on 23 May 2027. ASIC’s October 2026 consultation proposes a further extension and amendments. As at 22 October 2026, that proposal should not be described as an enacted extension.
Why leverage remains material
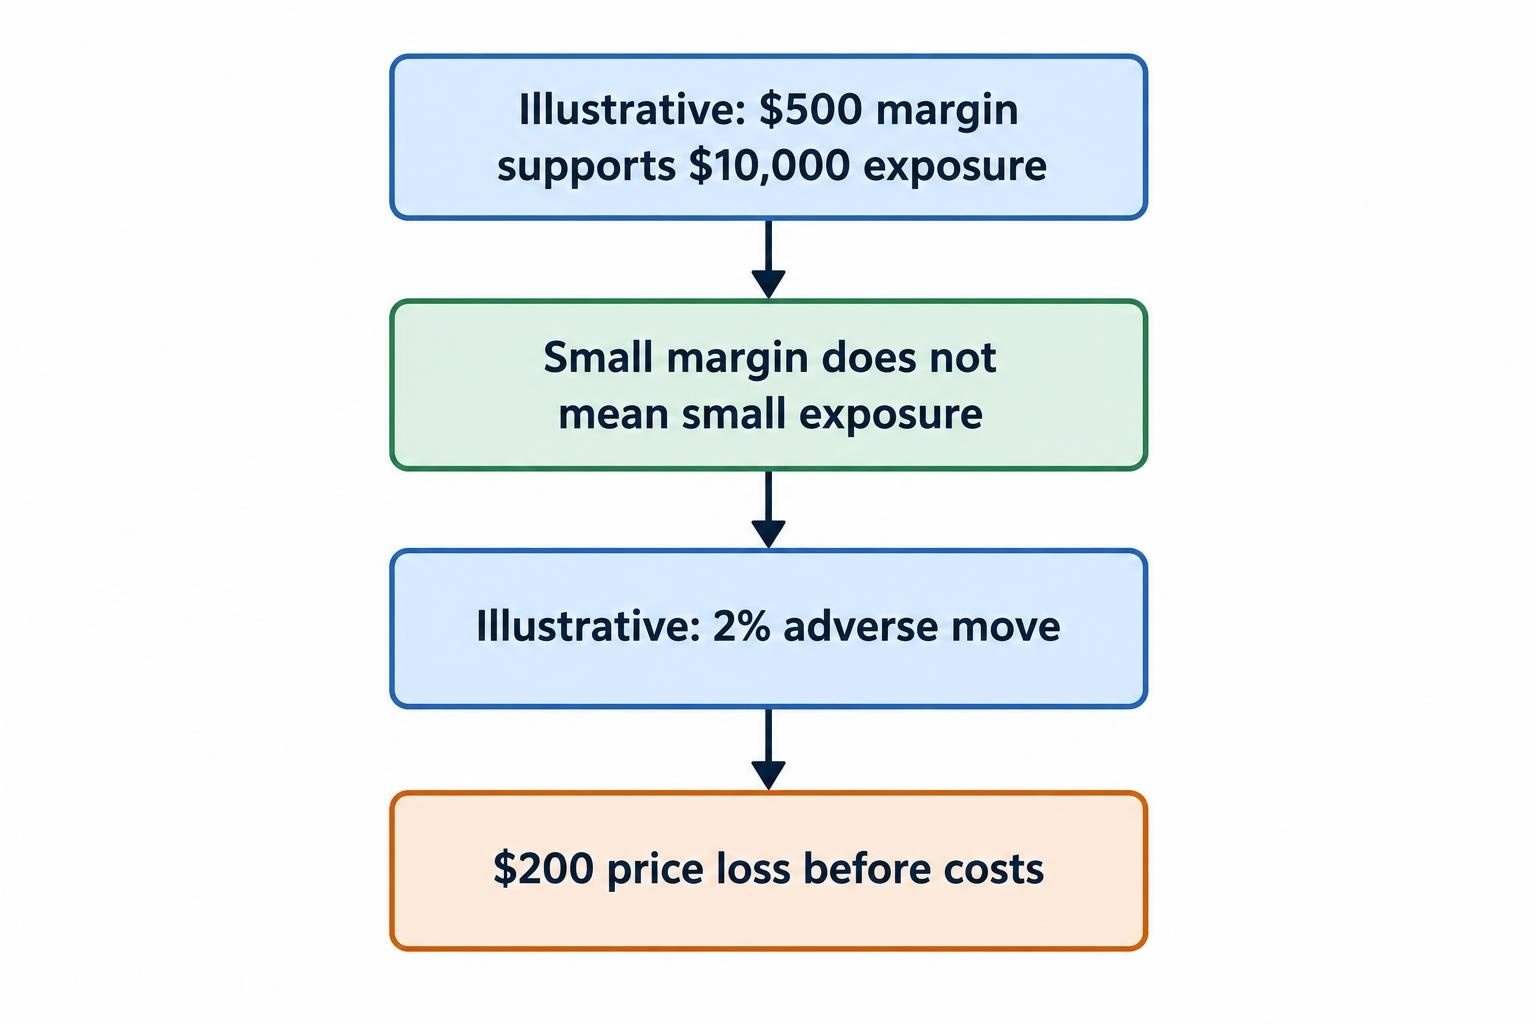
An illustrative $500 margin commitment supporting $10,000 of exposure produces a $200 price loss if the position moves 2% against the trader, before costs. The small margin does not make the economic position small.
An ordinary stop order does not guarantee an execution price. Gaps and fast markets can cause a worse exit than intended, while a stop-limit instruction may remain unfilled.
ASIC reported that 68% of retail CFD investors lost money in the 2024 financial year, with losses exceeding $458 million, including $73 million in fees. Those are CFD figures, not a universal failure rate for all trading products.
Moving to wholesale classification can remove retail protections. Higher available leverage is therefore not a neutral account upgrade. A small account is also not, by itself, a reason to choose CFDs.
Exchange-traded options
Buying a standard call or put
A standard call gives its buyer a right relating to purchase of the underlying at an agreed strike price; a put provides a corresponding right to sell. The precise exercise and settlement arrangements depend on the contract.
The buyer pays a premium. For a standard option closed without exercise or allowed to expire unexercised, the loss is limited to that premium and associated costs. This should not be extended into a claim that all option strategies have capped losses.
Options provide variable exposure rather than the fixed step payout of a conventional binary contract. Their prices also depend on remaining time and expected volatility. Correctly forecasting the underlying direction may still be insufficient to make a profit.
Moneysmart’s options guide distinguishes buying an option from writing one. The comparison of binary and vanilla options provides further context.
A simple expiry example
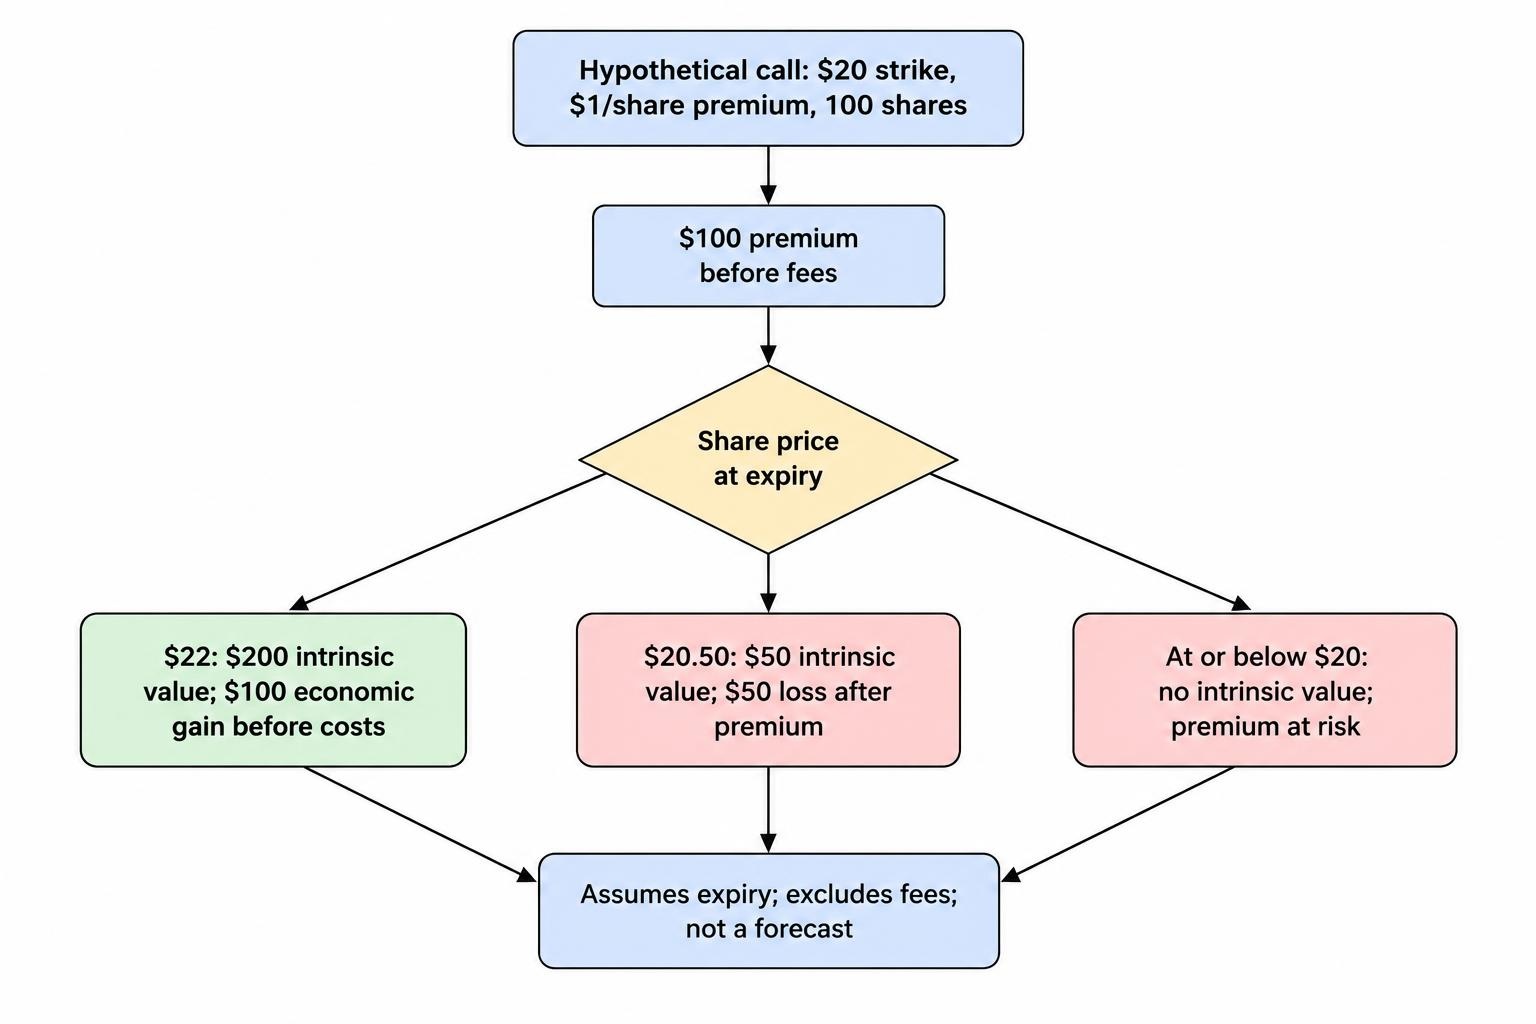
Assume a hypothetical call covering 100 shares has a $20 strike and costs $1 per share, or $100 before fees.
At expiry, a share price of $22 gives the call $200 of intrinsic value. After the $100 premium, the economic gain is $100 before costs, assuming that value is realised.
At $20.50, the intrinsic value is only $50. The underlying has finished above the strike, yet the position has lost $50 after allowing for the premium. At or below $20, the call has no intrinsic value at expiry.
Before expiry, its market price can also include time value. This makes an early sale different from the simplified expiry calculation.
Exercise and writing require separate attention
Exercise can create a share purchase or sale and associated funding requirements. A premium-limited option position can therefore lead to a separate underlying position with its own risks. Automatic-exercise policies and broker deadlines need to be understood.
ASX’s Understanding Options guide explains contract sizes, exercise and assignment. The actual specification should be checked rather than assuming every contract represents the same quantity.
Writing an option creates an obligation. An uncovered call can have theoretically unlimited loss potential; a written put can expose the writer to a large loss if the underlying falls.
Combining options can change the payoff, but introduces execution, assignment and position-management issues. Broker approval for options access does not establish that a particular strategy is appropriate or profitable.
Exchange-traded futures
Futures are standardised contracts with specified sizes, expiries and settlement arrangements. They can provide exposure to share indices, currencies, commodities and other reference markets.
Exchange trading and central clearing create a different structure from a bilateral CFD. They provide published contract rules and a framework for managing obligations between market participants. They do not guarantee liquidity at every price or protect the trader against market losses.
The amount posted as initial margin is security supporting the position. It is not the contract’s purchase price and generally does not cap the loss. Moneysmart’s futures guidance explains how losses can exceed initial margin.
Contract size determines the exposure
Suppose a hypothetical index futures contract is worth $5 per index point. A 40-point adverse movement produces a $200 loss per contract before fees. Trading three contracts makes the same movement a $600 loss.
A low advertised intraday margin does not change that calculation. The broker may also impose different requirements for overnight positions or volatile periods.
Smaller contract variants can reduce exposure per contract where available, but “micro” is a size description rather than a risk guarantee. The relevant question is whether the monetary movement fits the account’s loss capacity.
Expiry and settlement still matter to day traders
A trader intending to close before the end of the session still needs to understand what happens if the position remains open. Contract expiry may involve cash settlement or delivery obligations.
Trading hours, holidays, price limits and broker liquidation policies can also affect the exit. An order-book display does not guarantee that the displayed quantity will remain available.
The comparison of binary options and futures explains the funding and payoff differences. Futures offer a regulated market structure, but their obligations can be substantially larger than the initial cash posted.
Alternatives for preserving capital
A person looking to retain savings or earn interest may have little reason to replace binary options with another speculative derivative. Savings accounts and term deposits involve a different objective.
An eligible Australian-dollar deposit with an Australian-incorporated authorised deposit-taking institution can receive protection under the Financial Claims Scheme. APRA explains that the limit is $250,000 per account holder per ADI, across eligible accounts rather than separately for each account.
Brand names should not be assumed to represent separate ADIs. The institution and account’s eligibility need checking.
Deposit products also have trade-offs. Savings-account rates and bonus conditions may change. Term deposits can restrict access or reduce interest if money is withdrawn early. Inflation and tax affect the purchasing power of the return.
These products do not offer leveraged exposure or rapid speculative gains. Their relevance is that the goal may be preserving money rather than reproducing the frequency and excitement of binary trading.
Holding cash while deciding on an investment plan is also a decision. There is no requirement to move immediately into another product because one form of trading is unavailable.
Overseas products that are not automatic Australian substitutes
Event contracts and prediction markets
A contract paying a fixed amount if an event occurs can share the central features of a binary option even when it is traded on an overseas exchange.
Foreign supervision does not establish permission to offer the contract to Australian retail clients. The product terms, Australian legal classification and provider’s authority still matter.
As at the current review, Moneysmart states that no prediction-market operators are licensed as financial markets in Australia. It also warns about limited Australian protections when dealing with offshore providers.
An overseas event contract therefore should not be described as a general legal workaround or a low-cost training product for Australians. Small ticket sizes do not resolve the authorisation question or remove the possibility of losing the stake.
The comparison of binary options and prediction markets addresses their structural similarities.
Financial spread betting
Financial spread betting is associated with markets such as the UK. Its profit and loss depend on a stake per point multiplied by the price movement, making its exposure resemble other leveraged derivatives.
The UK FCA includes spread betting and rolling spot forex within its supervision of CFD products. UK availability and tax descriptions should not be transferred to an Australian resident’s circumstances.
A claim that a product is “tax-free” overseas does not establish Australian tax treatment. Nor does an overseas licence automatically authorise the provider’s Australian activities.
For an Australian comparison, the actual contract and authorised offering need to be identified. The label spread betting does not establish a safer or legally distinct route into the same economic exposure.
Crypto derivatives and tokenised products
Buying a crypto-asset, trading a crypto CFD and entering a perpetual derivative are different transactions. A tokenised representation of an asset also requires an explanation of the legal rights it carries.
A perpetual contract may have no fixed expiry, but can involve ongoing funding payments and forced liquidation. Continuous trading availability does not remove counterparty or operational risk.
ASIC’s guidance on digital assets explains that the applicable financial services protections depend on the asset and service involved. Overseas registration or the use of blockchain technology does not establish equivalent Australian protections.
The 2:1 retail leverage ceiling for crypto CFDs should not be interpreted as approval of every offshore crypto derivative. A named platform must be assessed through its actual Australian permissions and product terms.
Choosing a provider and understanding the total cost
Verify the account’s legal entity
The company named in the account agreement should match the entity whose authorisations are being checked. A group can operate several companies with different licences and client protections.
Moneysmart’s provider-checking guidance explains that an AFS licence is not an ASIC endorsement or a guarantee against losses. Contact details also need independent verification because scammers can impersonate licensed firms.
Commercial comparison services such as BrokerListings.com can help identify providers and compare advertised features. Their listings do not replace regulator-register checks or the provider’s current contractual documents.
For shares, clarify ownership and custody. For derivatives, clarify the counterparty, margin requirements, close-out rights and dispute process. A platform demonstration cannot establish those legal arrangements.
Compare complete transactions
A complete cost comparison includes entry and exit charges, spreads, financing where applicable, data subscriptions and currency conversion. A low headline commission can coexist with other material expenses.
The same holding period can create different costs across products. A funded shareholding and a leveraged CFD referencing that share have different financing arrangements, even when their charts look similar.
Foreign-market access adds conversion and timing considerations. The guide to currency conversion costs explains why the account currency and transfer process matter.
Liquidity also affects the realised price. A market order prioritises execution; a limit order constrains price but may not fill. No provider comparison should treat every intended exit as guaranteed.
Tax and performance records
Tax treatment depends on the instrument and circumstances. The ATO distinguishes share investment from a share-trading business in its guidance on share investing versus share trading. That distinction should not be automatically applied to every derivative.
Records should separate trading gains and losses from deposits, withdrawals, financing and other fees. An offshore account or a foreign product description does not by itself settle Australian reporting obligations.
A comparison of alternatives should finish with the exposure the person is prepared to accept. Ownership, premium-limited rights, margined obligations and deposits serve different purposes. Choosing an authorised provider is necessary, but the product must also fit the timeframe, capital and capacity for loss.
“`
This article was last updated on: October 22, 2026